Market Overview: Defining the Cutlery And Hand Tools Landscape
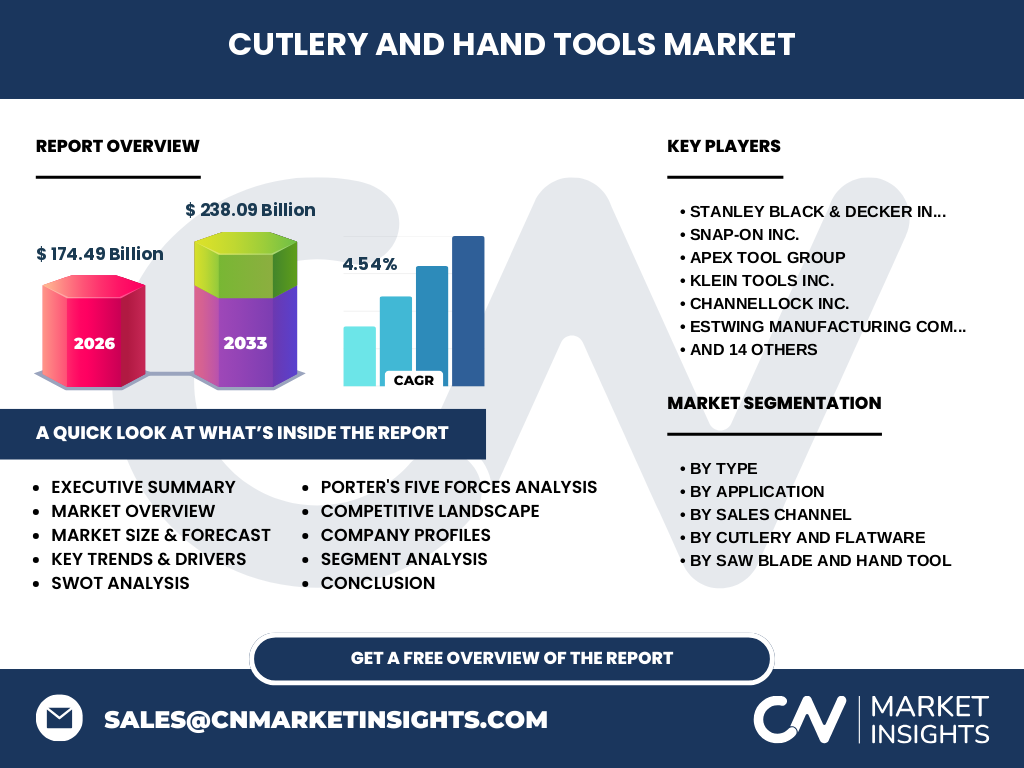
The Cutlery And Hand Tools Market encompasses a diverse ecosystem of manual implements and high-precision cutting blades. Valued at 174.49 Billion in 2026, this sector is integral to both domestic culinary functions and professional construction trades. It bridges the gap between artisanal craft and industrial manufacturing, serving as the backbone for infrastructure development and global gastronomic standards.
Structural Growth Drivers and Market Constraints
The market is propelled by a 4.54% CAGR, driven by rapid urbanization and the DIY housing renovation boom. However, volatility in raw material costs—specifically high-carbon steel and cobalt used in diamond blades—acts as a significant restraint. Logistical bottlenecks at major hubs like the Port of Los Angeles continue to challenge supply chain throughput for manufacturers like Stanley Black & Decker Inc.
Emerging Trends and Strategic Growth Patterns
A pivot toward ergonomic engineering and sustainability defines current trends. Professionals increasingly demand tools that reduce repetitive strain injury risk, favoring the designs of Fiskars Group and Channellock Inc. Furthermore, the integration of durable coatings to extend the service life of saw blades is redefining value propositions, pushing manufacturers to innovate beyond traditional metallurgy to maintain competitive relevance in a crowded space.
Analyzing the COVID-19 Impact and Recovery Trajectory
The pandemic triggered a paradoxical disruption: supply chains faced severe labor shortages, yet demand for DIY hand tools surged as household renovations became the primary outlet for locked-down consumers. Recovery remains anchored in digital transformation, with companies leveraging Online Sales channels to mitigate physical retail closures, ensuring that market performance remained resilient despite volatile macroeconomic conditions and shifting consumer behavior.
Competitive Benchmarking and Strategic Dynamics
The landscape is dominated by high-concentration players like Snap-on Inc. and Apex Tool Group, who emphasize brand equity and professional-grade certification. In contrast, firms like Zwilling J. A. Henckels AG focus on premium kitchen segments. The core dynamic is a tug-of-war between high-volume mass production strategies and niche artisan branding, forcing mid-tier companies to choose between aggressive pricing or specialized product differentiation.
Executive Summary: Synthesis of Research Findings
The Cutlery And Hand Tools Market is poised for substantial expansion, reaching a projected 238.09 Billion by 2033. This growth is underpinned by sustained demand in both the residential renovation sector and specialized professional manufacturing. Success in this market now requires a strategic blend of operational agility, robust e-commerce integration, and high-quality material sourcing to navigate global trade complexities effectively.
Market Forecast: Growth Trajectory from 2027 to 2033
Based on our modeling, the sector will evolve from its 2026 baseline of 174.49 Billion to 238.09 Billion by 2033. This consistent 4.54% growth rate reflects a long-term shift toward high-performance tools in emerging economies and persistent replacement cycles for established toolkits in North America and Europe, supported by consistent institutional investment in infrastructure maintenance and global culinary development.
Segmentation Analysis: Categorization and Market Utility
Segments are divided by Type (Cutlery/Flatware vs. Saw Blade/Hand Tool) and Application (Household vs. Commercial). The Saw Blade segment remains the primary engine for industrial revenue, while Flatware Sets and Kitchen Knives command consistent household retail volume. Our data indicates that understanding these specific utility roles—from Diamond Blades in construction to Steak Knives in hospitality—is critical for targeted market penetration.
Regional Market Analysis: Geographic Distribution
North America and Europe remain the hubs of high-value innovation, while the Asia-Pacific region dominates in manufacturing capacity and raw material processing. Regional performance is heavily influenced by construction spend and localized regulatory standards, such as ANSI/ISEA or EU safety directives. Companies like Morakniv AB and Victorinox Swiss Army Inc. continue to leverage regional identity to command premium pricing in diverse global markets.
In-depth Regional Review: Examining Key Markets
The North American market is characterized by a strong DIY culture, bolstering sales of Tape Measures, Levels, and Hammers. Meanwhile, the Asian market is seeing accelerated growth in commercial construction, increasing the demand for heavy-duty band saw blades. Understanding these regional nuances allows players like Klein Tools Inc. to tailor their distribution logistics to match local contractor preferences and regulatory requirements for tool durability and safety.
Company Profiles: Strategic Positioning of Industry Leaders
Leaders like Stanley Black & Decker Inc. capitalize on massive distribution networks, whereas Buck Knives Inc. and Spyderco Inc. thrive on collector-grade craftsmanship. Estwing Manufacturing Company maintains a distinct advantage in steel-forged tools, emphasizing durability. These strategic postures dictate market share; the giants compete on Sales Channel diversity, while boutique firms leverage specific, high-intent consumer niches to protect their margins from aggressive pricing competition.
Porter’s Five Forces: Competitive Intensity Assessment
Competitive rivalry is intense, moderated only by strong brand loyalty. The threat of substitutes is low for professional-grade hand tools but higher for low-end household cutlery. Supplier power is centered on raw steel availability, while the bargaining power of buyers is increasing due to the transparency of Online Sales platforms, forcing manufacturers to compete heavily on both product quality and price-to-value ratios.
SWOT Analysis: Strategic Outlook
Strengths: Long-term brand trust and essential utility. Weaknesses: Sensitivity to steel price fluctuations and supply chain inertia. Opportunities: Leveraging AI-driven demand forecasting to optimize inventory for Company Direct Sales. Threats: Rising geopolitical trade barriers that impact the cost of cross-border manufacturing. Our research suggests that mitigation of these threats requires localized production hubs to bypass high import tariffs and logistics volatility.
Value Chain Analysis: Flow from Raw Materials to End-Users
The value chain initiates with metallurgical raw material acquisition, flows through precision forging and casting, and culminates in multi-channel distribution. Significant value is captured at the assembly and finishing stages, where proprietary heat-treatment processes differentiate major brands. For Hultafors Group or Vaughan & Bushnell, success hinges on maintaining strict quality control throughout this flow to ensure performance reliability at the end-user construction or kitchen site.
Investment Insights: Strategic Recommendations
Investors should prioritize companies investing in smart-tool technology and e-commerce dominance. High-potential areas include firms producing specialized professional blades and those with robust Company Direct Sales infrastructure, which bypasses retail margin erosion. Our analysis indicates that companies effectively diversifying their geographic production footprint are better positioned to weather the volatility inherent in the global Cutlery And Hand Tools Market.
Conclusion and Key Takeaways
The Cutlery And Hand Tools Market is undergoing a technological and distribution evolution. With a market trajectory reaching 238.09 Billion by 2033, the path forward requires a focus on durability, ergonomics, and digital agility. Leading players who successfully integrate these elements while managing regional supply chain risks will capture the most significant share of the projected growth, setting the standards for the industry's next decade.
Research Methodology: How Baseline Estimates Are Triangulated
Our methodology utilizes a triangulation approach, synthesizing trade registry data from major ports, primary stakeholder interviews with industry CEOs, and secondary macroeconomic indicators regarding global construction output. We cross-reference historical revenue reports from firms like Acme United Corporation with Consumer Price Index shifts in raw materials to calibrate our forecasts and ensure the precision of our 4.54% CAGR projections across all segments.
Scope of the Report: Coverage Parameters and Limitations
This report covers the global Cutlery And Hand Tools Market, specifically focusing on the 2026-2033 window. It examines all identified Type and Application segments. Limitations include inherent market fluctuations due to geopolitical instability, which may impact material costs. The analysis prioritizes professional and industrial segments, providing granular data on major industry participants while maintaining a focus on actionable insights for strategic decision-makers.
Recent Developments: Industry Announcements and Strategic Moves
Recent strategic moves show a clear trend toward consolidation and digital expansion. Notable developments include new product launches in Diamond Blades and Cordless Hand Drills, alongside strategic partnerships aimed at strengthening Online Sales presence. These shifts indicate that firms like Columbia River Knife & Tool Inc. and Cold Steel Inc. are aggressively pivoting to meet the modern demand for high-performance, easily accessible professional tools.