Understanding the Steel Fiber Market: Scope and Significance
The Steel Fiber Market represents a critical pillar in global construction material science. By integrating metallic fibers into concrete matrices, manufacturers enhance tensile strength, ductility, and crack resistance. Our scope covers the lifecycle from raw wire drawing to specialized applications, serving as a foundational technology for modern civil engineering and high-temperature refractories, ensuring structural longevity in extreme environments.
Structural Growth Drivers and Market Constraints
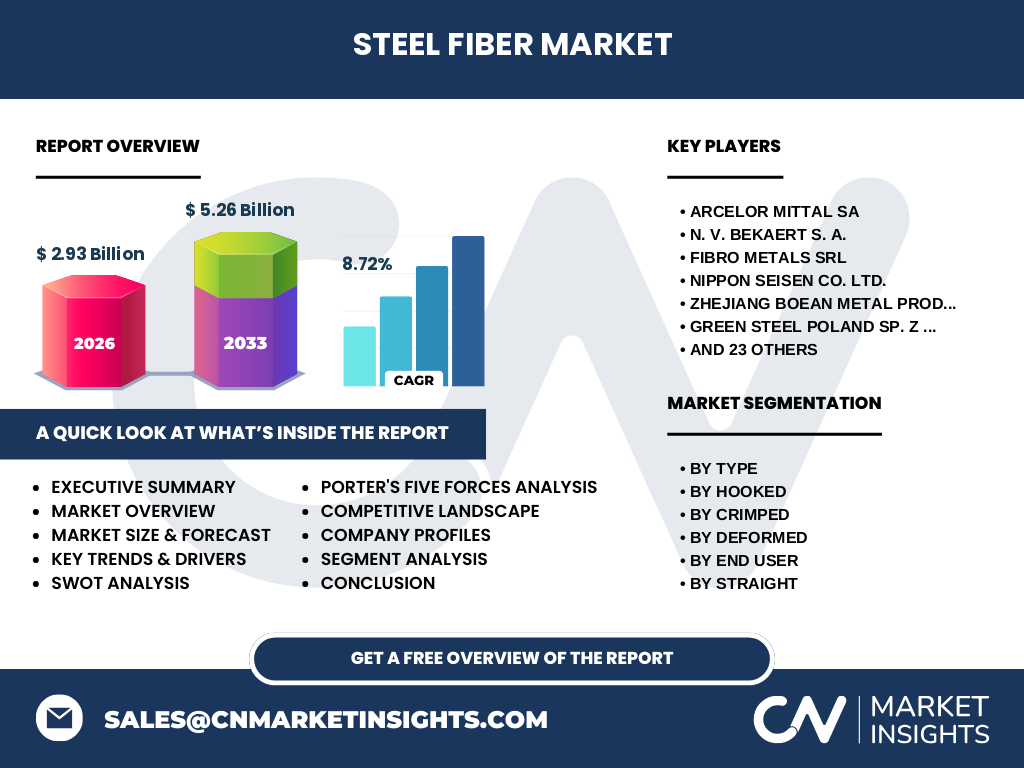
The market is propelled by a CAGR of 8.72%, driven by the global need for seismic-resistant infrastructure. Growth is bolstered by demand for high-performance industrial flooring and tunneling projects. Conversely, the market faces constraints from volatile raw material prices—specifically steel scrap and ore—and stringent localized environmental regulations, such as those imposed by the EU Green Deal on heavy metal processing.
The Shift Toward High-Performance Fiber Architectures
Current trends indicate a pivot toward specialty hooked fibers and micro-reinforcements. We observe that firms like N. V. Bekaert S. A. and Arcelor Mittal SA are prioritizing innovation in fiber geometry to optimize bond efficiency. This shift represents a transition from commodity, bulk-supply models to value-engineered solutions that reduce the overall volume of concrete required, lowering the carbon footprint for end-users.
COVID-19 Impact and Recovery Trajectory
The pandemic caused temporary supply chain paralysis, particularly impacting logistics through major hubs like Shanghai and Rotterdam. However, the recovery trajectory has been robust. Post-pandemic, the Steel Fiber Market benefited from increased government stimulus packages focused on massive infrastructure revitalization. By 2026, the market stabilized at 2.93 Billion, with a rapid rebound led by the construction and manufacturing sectors.
Competitive Benchmarking and Strategic Dynamics
The market features a tiered competitive landscape where global leaders like Bekaert and Maccaferri SpA leverage economies of scale against regional specialists like Zhejiang Boean Metal Products. Strategic success relies on vertical integration; firms that control wire rod production, such as Ugitech S. A., maintain superior margin stability compared to independent distributors during periods of metal price volatility.
Executive Summary: Strategic Market Synthesis
Our analysis projects the Steel Fiber Market to reach 5.26 Billion by 2033. The industry is entering a high-growth phase defined by technological maturity and increased integration into smart cities. While competitive pressure remains high, the shift toward standardized, high-performance reinforcement remains the primary catalyst for long-term valuation expansion, necessitating strategic capital allocation by key stakeholders.
Market Forecast: 2027 to 2033 Growth Outlook
Between 2027 and 2033, the market will accelerate from its current valuation to 5.26 Billion. This expansion is underpinned by a CAGR of 8.72%, reflecting the sustained demand for reinforced concrete in developing urban centers. We expect emerging economies to contribute disproportionately to this growth, driven by rapid industrialization and the adoption of modern structural safety codes.
Segmentation Analysis: Categorizing Value Drivers
We categorize the market by Type (Hooked, Straight, Deformed, Crimped) and Application (Concrete, Composite, Refractories). Hooked fibers command the largest share due to their superior anchoring in hardened concrete. Specialty Hooked Fibers are witnessing the fastest adoption rates, serving high-end civil works, while Straight Fibers remain the volume-driver for consistent industrial manufacturing floorings.
Geographic Distribution and Performance Mapping
Regional performance is dictated by urbanization rates. The APAC region currently dominates, led by players like Hunan Sunshine steel fiber co. Ltd. and Nippon Seisen Co. Ltd., due to intensive infrastructure spending. Europe and North America follow, with mature markets focusing on sustainability and recycled steel integration, forcing regional manufacturers like Green Steel Poland to align with strict environmental governance standards.
In-Depth Regional Review of Key Markets
APAC remains the epicenter of the Steel Fiber Market, supported by heavy domestic demand for tunnels and bridges. Meanwhile, the European market is defined by high-performance Refractories and High-Temperature Applications. In North America, companies like Nycon Corp. focus on specialized fiber blends that meet specific DOT standards, demonstrating how local building codes fundamentally shape regional segment adoption.
Company Profiles: Strategic Positioning of Industry Leaders
Leading entities like Arcelor Mittal SA utilize global supply chain networks to maintain cost leadership. In contrast, firms such as Ribbon Technology Corporation differentiate through proprietary metal-shaping processes for niche high-temperature environments. We also track regional innovators like Stewols India Ltd., which are capturing market share by aligning manufacturing processes with local, price-sensitive infrastructure bidding cycles.
Porter's Five Forces Assessment
The Steel Fiber Market experiences high competitive rivalry, yet low supplier power for large players who control their wire rod inputs. Barriers to entry are moderate, requiring significant investment in metal fabrication technology. Threat of substitutes remains low, as steel fiber provides a unique combination of tensile and crack-bridging properties that polymer alternatives cannot currently match in heavy-load infrastructure.
SWOT Analysis of the Steel Fiber Landscape
Strengths include superior mechanical bonding, while weaknesses center on potential corrosion in high-salinity environments. Opportunities exist in smart-fiber integration (e.g., self-monitoring concrete), and threats include price fluctuations in global steel indices. Strategic firms are mitigating these threats by diversifying their product portfolios into deformed and crimped variants to capture diverse architectural specifications.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with scrap and iron ore mining, followed by wire drawing and fiber shaping. Companies such as Junwei Metal Fiber Co. Ltd. occupy the manufacturing midstream. The final flow reaches construction OEMs and EPC contractors. Logistical efficiency at ports—such as the movement of finished fiber from Zibo Tenran facilities—is a critical factor in determining end-user price competitiveness.
Investment Insights and High-Potential Areas
We identify specialty hooked fiber manufacturing as the highest ROI investment area. Current data suggests that capital allocated to automated quality-assurance systems—which verify fiber geometry post-production—yields the best long-term margins. Investors should monitor firms that are actively securing green-energy power purchase agreements to offset the high carbon footprint associated with traditional steel manufacturing processes.
Conclusion and Strategic Takeaways
The Steel Fiber Market is transitioning from a niche commodity to a technologically essential component of global development. With a projected 5.26 Billion valuation by 2033, industry participants must prioritize vertical integration and innovation in high-durability fiber designs. Success hinges on balancing cost-effective raw material procurement with the ability to meet increasingly stringent structural and sustainability-focused regulatory standards globally.
Research Methodology and Data Triangulation
Our findings are triangulated through primary stakeholder interviews with regional manufacturing directors and cross-referenced with trade registry data from major global ports. We synthesized this with secondary macroeconomic indicators regarding infrastructure budgets. By reconciling production output reports from key manufacturers with actual consumption patterns in the construction sector, we ensure high confidence in our 8.72% CAGR estimation.
Scope of the Report and Coverage Parameters
This report encompasses the global Steel Fiber Market, focusing on all key geographies and segmentations including Hooked, Straight, Deformed, and Crimped types. Limitations of the research include the inability to fully account for localized black-market production in fragmented regions; however, our coverage remains exhaustive for all commercial-grade production and legitimate international trade flows through 2033.
Recent Developments in the Sector
Recent strategic moves include partnerships between steel producers and chemical admixture providers to improve fiber-concrete bonding efficiency. Several companies, including Fabpro Polymers Inc. and Euclid Chemical Co., have launched hybrid-fiber solutions. These product launches demonstrate a industry-wide push to combine traditional metallic strength with modern, high-durability synthetic properties to meet the evolving demands of aerospace and high-performance infrastructure projects.