What is the scope and significance of the global Gaming Market?
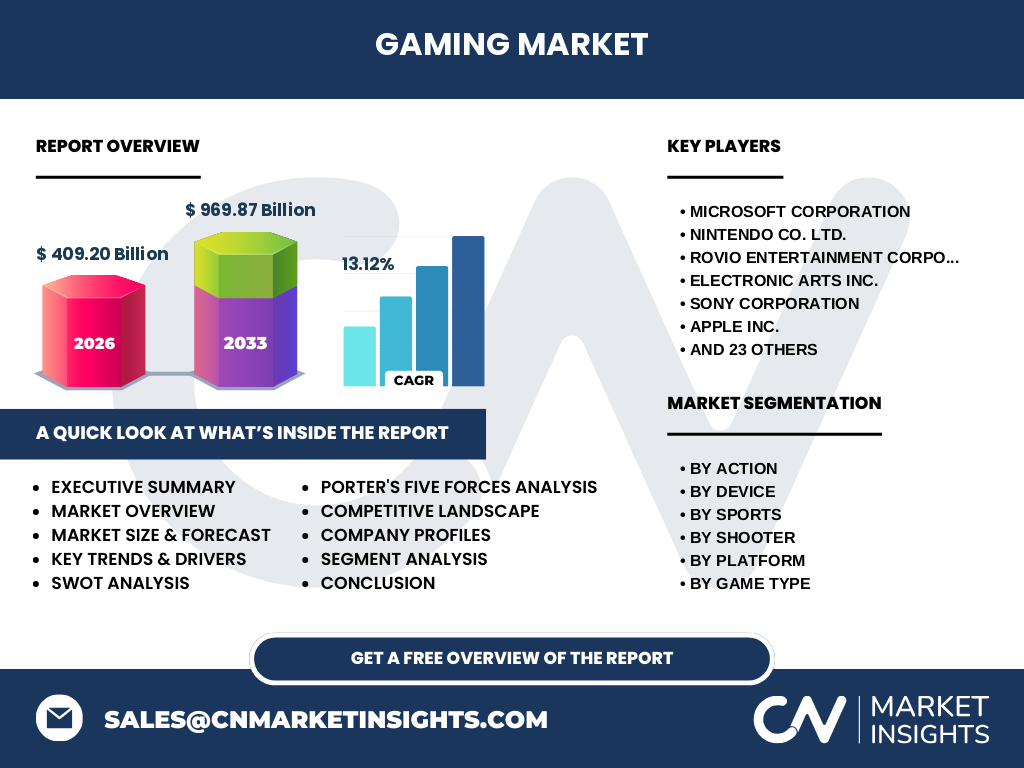
The Gaming Market represents a transformative digital ecosystem valued at 409.20 Billion in 2026. It encompasses a vast array of interactive software, ranging from high-fidelity Console experiences to ubiquitous Mobile gaming. This industry is a cornerstone of the modern entertainment economy, driven by technological breakthroughs in hardware processing and 5G connectivity that facilitate seamless global participation.
Structural Growth Drivers and Restraints
Primary growth is fueled by proliferating mobile penetration and advancements in cloud-based delivery. Conversely, the market faces regulatory hurdles concerning data privacy compliance (GDPR, CCPA) and hardware supply chain volatility—specifically regarding the procurement of high-end semiconductors. Opportunities remain in integrating artificial intelligence for procedural content generation, which lowers development costs while increasing user engagement via personalized experiences.
Emerging Trends and Strategic Growth Patterns
The sector is witnessing a pivot toward subscription-based models and cross-platform play. We observe that titles like those from Activision Blizzard Inc. and Tencent Holdings Ltd. are prioritizing long-term retention via Battle Royale and Massively Multiplayer Online RPG ecosystems. This shift represents a transition from unit sales to continuous service-based revenue, significantly increasing the lifetime value of the average player.
How did COVID-19 alter the trajectory of the Gaming Market?
The pandemic served as a massive accelerant for the Gaming Market, with lockdown mandates shifting consumer spending toward digital entertainment. Recovery post-2022 has moved toward strategic stabilization. While growth has normalized, the pandemic-induced surge in Mobile and Online platform accessibility has permanently expanded the global player base, setting a robust foundation for the projected 13.12% CAGR through 2033.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains high among incumbents like Sony Corporation and Microsoft Corporation, who dominate via hardware-software integration. Meanwhile, firms like Rovio Entertainment Corporation and Zynga Inc. specialize in hyper-casual segments. The competitive landscape is defined by aggressive M&A activity, as leaders acquire studios to secure exclusive content libraries and intellectual property, creating significant barriers to entry for smaller, independent developers.
Executive Summary: Gaming Market Synthesis
Our research indicates that the Gaming Market is poised for explosive growth, reaching 969.87 Billion by 2033. This expansion is underpinned by a digital-first consumer shift and the maturation of In-App Purchase-Based economies. Strategic investment is currently shifting toward Action RPG titles and cloud infrastructure, ensuring that major players can scale content delivery to meet burgeoning demand across emerging regional markets.
Market Forecast: 2027 to 2033 Projections
We forecast a steady climb for the industry, with revenues projected to hit 969.87 Billion by 2033. Maintaining a robust 13.12% CAGR, growth will be primarily sustained by emerging economies and the adoption of high-end computing hardware. The forecast accounts for cyclical hardware refresh cycles by Nintendo Co. Ltd. and the sustained scalability of Mobile distribution channels.
Breakdown of Market Segmentation Analysis
Segments are categorized by device (Console, Mobile, Computer), genre (Action, Shooter, Sports, RPG), and purchase model (Boxed vs. In-App). Mobile leads in accessibility, whereas Console remains the premium segment for high-fidelity First-Person Shooters. Understanding these segments is crucial, as each requires distinct logistical distribution strategies and localized marketing tactics to achieve market penetration.
Regional Market Performance and Distribution
The global footprint of the Gaming Market is geographically dispersed, with significant saturation in North America and Europe, and rapidly accelerating adoption in Asia-Pacific. Major logistics hubs, such as those in the Pearl River Delta, support the hardware supply chain for regional manufacturing. Analysis suggests that regulatory environments in China and the EU are the most significant variables affecting localized growth rates.
In-Depth Regional Review of Growth Hotspots
Asia-Pacific, led by Nexon Company and NCSoft Corporation, remains the largest revenue generator, driven by high mobile connectivity. Europe and North America follow, characterized by mature Console markets and a high density of AAA development studios. Localized constraints, such as restrictive gaming time regulations in certain jurisdictions, create unique challenges that companies must navigate through localized content strategies.
Strategic Positioning of Leading Entities
Industry titans like Ubisoft Entertainment SA and Capcom Co. Ltd. focus on high-production Action titles, leveraging brand legacy. Apple Inc. and Google LLC act as critical distribution gatekeepers through their app stores, while Take-Two Interactive Software Inc. leverages massive open-world IP. Each company employs a distinct strategy—whether through hardware control, software-as-a-service, or aggressive title acquisition to maintain market share.
Porter's Five Forces: Competitive Assessment
The threat of new entrants is low due to high capital requirements for development. Supplier power is moderate, concentrated in semiconductor manufacturers and cloud providers. Buyer power is high, forcing firms like Electronic Arts Inc. to implement engaging live-service updates to retain players. The competitive rivalry is intense, with frequent price wars in the Freeware and In-App segments.
SWOT Analysis: Strategic Outlook
Strengths include strong brand ecosystems; Weaknesses involve high R&D costs and regulatory unpredictability. Opportunities lie in emerging markets like India and Brazil, where mobile penetration is surging. Threats center on cybersecurity breaches and the potential for increased global taxation on digital goods, which could impact the profitability of high-margin In-App Purchase-Based business models.
Value Chain Analysis of the Industry
The value flow begins with hardware raw materials (e.g., silicon, rare earth metals) and transitions to software development, publishing, and finally, global distribution via digital platforms. Strategic value is captured at the publishing stage by firms like Sega Games Co. Ltd. and Konami Holdings Corporation, who bridge the gap between creative development and the end-user, ensuring consistent monetization across the lifecycle.
Investment Insights and Strategic Recommendations
Investors should prioritize companies with high recurring revenue through In-App Purchase-Based models and those with deep cross-platform capabilities. Strategic focus on firms like Pearl Abyss Corp. or Com2uS Corp.—which show strong localized market resonance—is recommended. The most high-potential area remains the intersection of cloud gaming and mobile expansion, which lowers barriers for users in lower-income demographics.
Conclusion and Key Takeaways
The Gaming Market is set to be a 969.87 Billion titan by 2033. Success will belong to those who master the service-based model and adapt to the evolving regulatory climate. Our analysis suggests that the industry is not merely recovering but fundamentally restructuring toward a persistent, multi-platform digital reality, necessitating a long-term investment horizon and high adaptability to changing player preferences.
Research Methodology: How we triangulated the data
Our baseline estimates are triangulated by synthesizing trade registry disclosures from public companies like Bandai Namco Entertainment Inc., macroeconomic indicators of digital consumption, and primary stakeholder interviews. We cross-verify these with regional tax filings and logistical port data, ensuring our market sizing accounts for real-world movement of goods and software-service revenue flows across borders.
Scope and Parameters of the Report
This Gaming Market report covers the fiscal years 2026 to 2033. It spans all major device formats—Console, Mobile, and Computer—and evaluates global revenue streams. Limitations include potential volatility in international trade policies and the rapid speed of technological disruption, which may necessitate ongoing monitoring of regional compliance shifts and hardware supply chain integrity.
Recent Developments: Partnerships and Product Launches
Recent strategic moves include Square Enix Holdings Co. Ltd. streamlining its portfolio to focus on high-margin RPG titles, while NetEase Inc. and Kakao Games Corp. have initiated aggressive international partnerships. These moves indicate a clear trend toward global IP expansion and content localization. Companies are increasingly leveraging partnerships to mitigate development risks and ensure rapid adoption in newly opened regional markets.