Market Overview: Defining the Foundries Market Scope
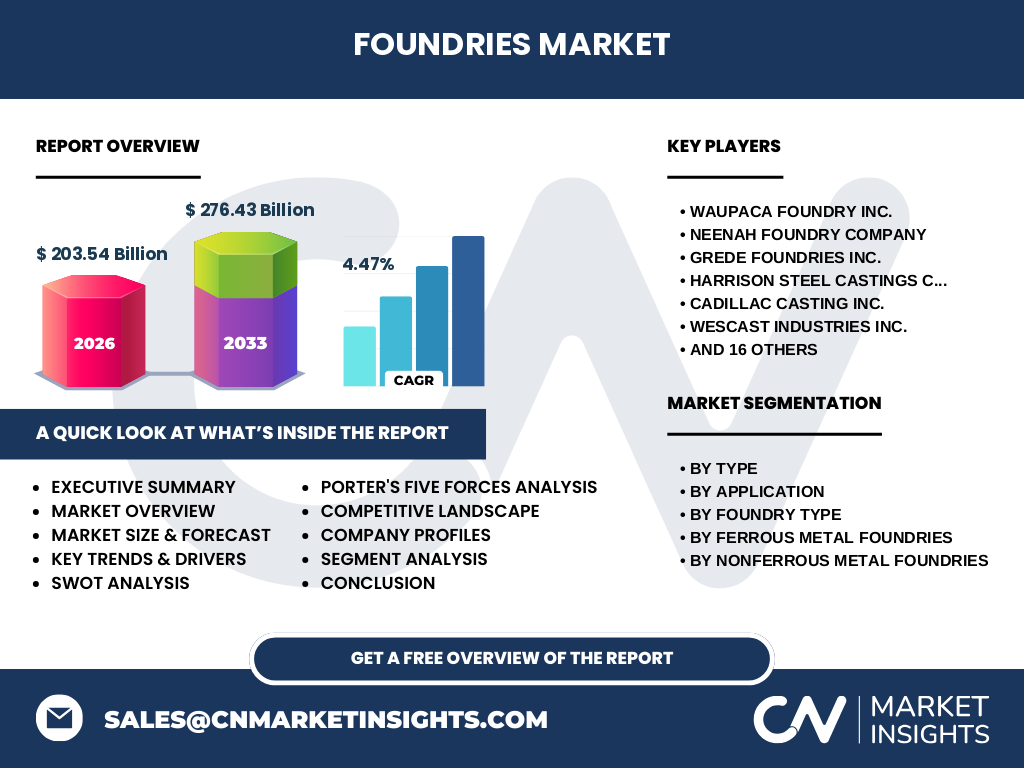
The Foundries Market serves as the backbone of global industrialization, encompassing the casting of ferrous and nonferrous metals into precise shapes. With a 2026 valuation of 203.54 Billion, this sector is essential for transforming raw scrap and virgin alloys into critical components. Its significance lies in providing structural integrity to everything from massive agricultural machine housings to lightweight automotive engine blocks.
Structural Growth Drivers and Market Constraints
Growth is propelled by rising urbanization and automotive modernization, while high energy costs and stringent EPA or EU-REACH environmental compliance remain significant hurdles. Our analysis indicates that the demand for lightweight aluminum alloys provides a key opportunity to offset the rising costs of traditional iron casting. Manufacturers must navigate these logistical constraints to remain competitive in a capital-intensive environment.
Emerging Trends Reshaping Metal Casting
The shift toward electrification is forcing foundries to pivot from traditional cast-iron engine components to complex, thin-walled nonferrous aluminum castings. We observe that industry leaders are increasingly adopting Industry 4.0 diagnostics to monitor melt quality in real-time. This technological evolution is non-negotiable for firms seeking to maintain margins amid volatile raw material pricing for commodities like copper and nickel.
COVID-19 Impact and Recovery Trajectory
The pandemic triggered a sharp contraction due to supply chain bottlenecks and plant shutdowns, particularly in the automotive-reliant sectors. However, the recovery trajectory has been robust, characterized by a rapid return to just-in-time manufacturing. Our research shows that firms like Waupaca Foundry Inc. utilized this period to optimize operational resilience, positioning them well for the sustained expansion expected through 2033.
Competitive Benchmarking and Market Concentration
The market features a mix of massive conglomerates like Precision Castparts Corp. and specialized merchant foundries. The competitive landscape is highly concentrated in high-precision aerospace and automotive segments. Strategic dominance is defined by vertical integration; firms that control their own scrap supply and thermal processing, such as Nemak S.A.B. de C.V., hold a distinct competitive advantage over smaller, localized jobbing foundries.
Executive Summary: Foundries Market Forecast
The Foundries Market is poised for steady expansion, growing from its 2026 base of 203.54 Billion to an projected 276.43 Billion by 2033. This represents a solid CAGR of 4.47%. Our analysis identifies this as a period of significant consolidation, where capital-rich entities will likely acquire smaller foundries to secure regional capacity and technological expertise in advanced metallurgy.
Segmentation Analysis: Categorizing Industry Verticals
Segmentation by type allows for nuanced tracking: Ferrous Metal Foundries (Gray, Ductile, Steel) dominate high-load infrastructure, while Nonferrous Foundries (Aluminum, Copper, Zinc, Magnesium) are critical to the automotive sector. Furthermore, Pure Play, Merchant, and Jobbing foundry types address different market roles, ranging from high-volume automotive OEM supply to bespoke, small-batch tooling and machine component fabrication for heavy industry applications.
Regional Market Performance and Geographic Distribution
Regional dominance is tied to manufacturing hubs. The Asia-Pacific region leads due to massive infrastructure development, while North America focuses on high-tech aerospace and automotive innovations. Logistical hurdles such as port capacity in regions like the Port of Los Angeles or Shanghai dictate raw material availability, causing localized price fluctuations that impact the cost-basis of regional foundry operations significantly.
In-depth Regional Review: Strategic Hotspots
In North America, the proximity of Cadillac Casting Inc. to the Great Lakes manufacturing corridor remains a massive logistical asset. Conversely, the European market is heavily influenced by strict decarbonization mandates, forcing firms like Georg Fischer Ltd. to innovate in energy-efficient melting processes. These regional dynamics create distinct operational requirements that international players must master to ensure sustained, profitable growth through 2033.
Strategic Positioning of Leading Companies
Companies are segmenting by expertise: Howmet Aerospace Inc. focuses on high-margin, complex aerospace investment castings, while Grede Foundries Inc. prioritizes volume automotive contracts. MetalTek International leverages metallurgical expertise to serve the defense and power generation sectors. This specialization enables these firms to command pricing power, shielding them from the commodity-price sensitivity that plagues general-purpose foundries operating in lower-value, high-volume segments.
Porter's Five Forces: Competitive Assessment
The threat of substitutes, such as additive manufacturing (3D printing), is rising but remains limited by scale. Bargaining power of buyers is high in the automotive sector, forcing foundries to integrate deeply with OEM supply chains. Meanwhile, the barrier to entry remains significant due to the immense capital expenditure required for high-capacity induction furnaces and emission-control environmental compliance infrastructure.
SWOT Analysis of the Global Foundries Market
Strengths: Deep integration with essential manufacturing sectors. Weaknesses: High energy and labor intensity. Opportunities: Lightweighting trends in electric vehicle (EV) production driving demand for aluminum castings. Threats: Stringent environmental regulations and fluctuating costs of raw metallic commodities. Navigating these factors requires agile supply chain management and investment in modern, lower-carbon foundry technologies to remain compliant and profitable over the long term.
Value Chain Analysis: From Raw Materials to End-Users
The value chain initiates with the procurement of scrap metals and alloying elements. Value is added during the melting, molding, and finishing processes. Specialized foundries, such as Harrison Steel Castings Company, add value through precision heat treatment and testing. The final products flow into Tier-1 automotive assemblers or heavy machine OEMs, who represent the primary economic drivers for the entire foundry ecosystem.
Investment Insights and High-Potential Areas
Investment should focus on foundries that demonstrate early adoption of electrification-friendly alloys and automated casting lines. Firms like Ryobi Limited that cater to high-volume automotive light-weighting represent safer, higher-growth bets. Our data suggests that mid-market foundries with strong environmental, social, and governance (ESG) performance will attract more capital as manufacturers seek to green their own supply chains to meet global climate goals.
Conclusion: Key Takeaways for Market Stakeholders
The Foundries Market is navigating a transition from traditional heavy-iron manufacturing to high-tech, lightweight alloy production. Achieving a CAGR of 4.47% through 2033 requires aggressive investment in automation and regulatory compliance. Industry participants must capitalize on the 276.43 Billion valuation by securing supply chains, focusing on specialized applications, and maintaining a lean, energy-efficient operational profile to outpace competition and mitigate volatility.
Research Methodology: Triangulating Industry Data
Our baseline estimates are built by triangulating trade registry filings, primary interviews with procurement managers at Tier-1 suppliers, and secondary analysis of global macroeconomic output. We cross-reference production volume trends with raw material consumption indices from key ports and regulatory disclosures. This ensures our 2027-2033 forecasts reflect actual industrial throughput rather than mere top-down projections, providing a highly reliable foundation for strategic decision-making.
Scope of the Report and Coverage Parameters
This report covers the global Foundries Market, segmenting data by metallurgy (ferrous/nonferrous) and application. It excludes non-metal foundry processes and focuses exclusively on industrial-scale casting operations. While we include significant players like Bharat Forge Ltd. and Zollern GmbH & Co. KG, the scope is limited to market trends within the 2026-2033 timeframe, providing a focused view on mid-term growth potential and structural shifts.
Recent Developments: Major Industry Strategic Moves
Recent activity highlights a wave of partnerships centered on decarbonization and smart-factory integration. Major announcements from firms like Eck Industries Inc. regarding low-carbon aluminum production underscore the industry's pivot. These strategic moves are essential for maintaining a competitive edge as customers prioritize sustainability in their vendor audits, effectively using environmental footprint as a competitive differentiation factor in contract bidding.