What is the current state and industry scope of the Hot Dip Galvanizing Market?
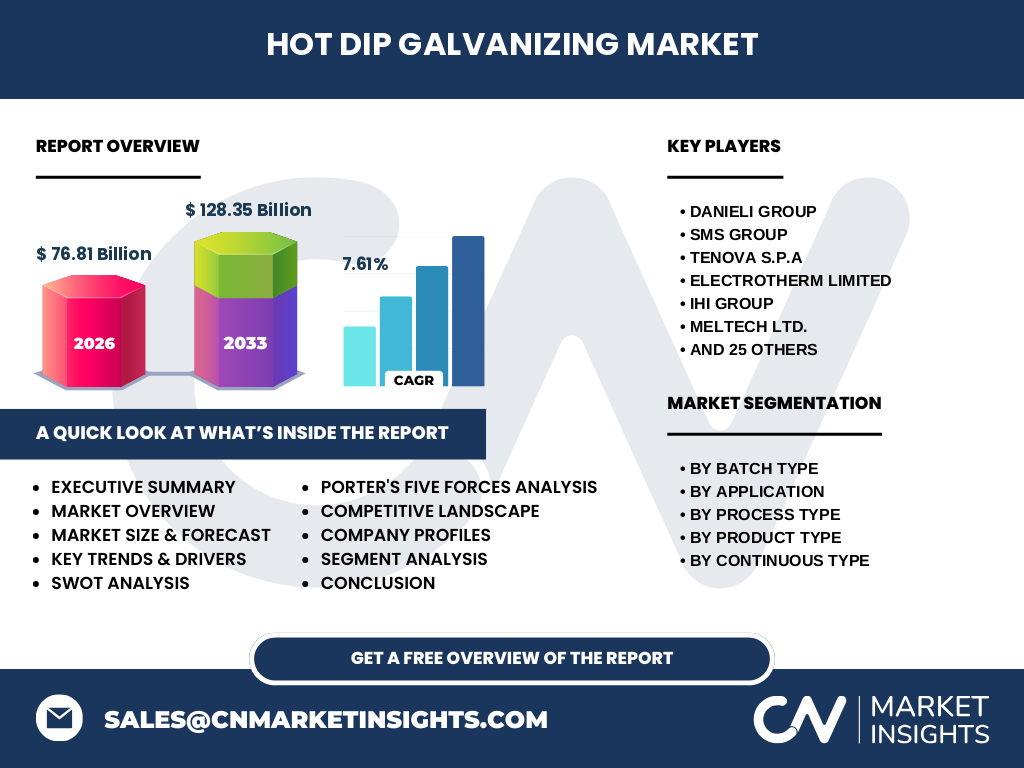
The Hot Dip Galvanizing Market represents a critical pillar in global corrosion prevention, currently valued at 76.81 Billion in 2026. This sector encompasses the metallurgical application of molten zinc to steel products, essential for extending the lifespan of infrastructure. As a foundational industrial process, it serves as the ultimate barrier against oxidation in harsh environments, vital for maintaining structural integrity across energy, civil engineering, and transportation sectors.
Structural Growth Drivers and Market Constraints
Growth is propelled by urbanization and the resurgence of infrastructure spending globally, expected to push the market to 128.35 Billion by 2033. A major constraint remains the volatility of zinc prices and stringent environmental compliance standards enforced by regulatory bodies like the EPA or EU REACH. However, technological shifts toward sustainable, zero-waste fluxing processes offer lucrative opportunities for companies to capture high-margin, environmentally conscious segments.
Emerging Innovation Trends in Galvanizing Technology
Our research identifies a pivot toward automated continuous line efficiency. Innovators like Tenova S.p.A and Danieli Group are leading the transition to energy-efficient induction heating, which minimizes metallic dross formation. This shift toward Multi-Line Continuous Galvanizing allows for higher throughput and superior coating uniformity, addressing the increasing demand for high-strength, thin-gauge steel sheets required by modern automotive manufacturers to reduce vehicle curb weight.
How did COVID-19 redefine the Hot Dip Galvanizing Market trajectory?
The pandemic caused a temporary supply chain paralysis in 2020 due to logistical hurdles at major ports like Shanghai and Rotterdam. However, the subsequent V-shaped recovery was catalyzed by government-led stimulus packages focusing on heavy infrastructure. Our analysis shows that this volatility forced manufacturers to prioritize local sourcing strategies and digitization of shop-floor monitoring, ultimately creating a more resilient and tech-forward industry baseline entering 2027.
Competitive Benchmarking and Market Concentration
The market landscape is defined by a dichotomy between integrated metallurgical giants and niche induction furnace specialists. Players like Inductotherm Group, SMS Group, and IHI Group hold significant competitive moats due to their proprietary furnace technologies. Concentration is moderate, with top-tier players leveraging global service footprints to secure long-term contracts with regional steel producers, while smaller, regional players compete on specialized batch-galvanizing services and local logistical advantages.
Executive Summary of Global Market Prospects
The Hot Dip Galvanizing Market is poised for a CAGR of 7.61% through 2033. This growth is underpinned by robust demand in emerging markets and high-end industrial modernization in developed economies. Firms that integrate advanced automation and energy-saving induction technologies are set to outperform. Strategic focus on vertical integration and supply chain risk mitigation will be the defining features of winning organizations in this 128.35 Billion industry.
Projected Market Forecast for 2027-2033
The market is projected to reach 128.35 Billion by 2033, growing from its 2026 base of 76.81 Billion. This trajectory is driven by aggressive adoption of continuous galvanizing lines in the automotive sector and sustained investment in civil architecture. We forecast that the Asia-Pacific region will maintain the highest growth velocity, fueled by rapid industrialization and large-scale government-backed civil infrastructure projects that require long-term durability provided by galvanized coatings.
Segmentation Analysis of the Galvanizing Landscape
The market is segmented by Process Type (Batch vs. Continuous), Product Type (Sheet/Coil, Tubes, Wires), and Application (Automotive, Civil, etc.). Continuous lines dominate the high-volume sheet/coil market for automotive use, while Batch Galvanizing remains essential for complex, irregular structural steel shapes. Understanding this segmentation is crucial, as the capital expenditure (CAPEX) requirements for Continuous systems significantly exceed those of Small-Scale Batch Galvanizing units.
Geographic Distribution and Regional Performance
Regional performance is stratified by industrial output. Asia-Pacific leads due to rapid expansion in China, India, and Southeast Asia, whereas North America and Europe focus on quality-centric, high-throughput continuous lines to support advanced automotive and aerospace manufacturing. Regional disparities are exacerbated by local regulatory hurdles and availability of base materials, making localized production capacity a significant competitive advantage over pure import-dependent models.
Detailed Review of Key Regional Markets
In North America, the shift toward electrification in transport is driving demand for specific high-strength galvanized coils. Conversely, the Middle East and Africa, led by entities like Amir Industrial Equipments, are seeing a surge in structural demand for desalination and utility infrastructure. Our data suggests that the European market is prioritizing low-carbon intensity production, heavily favoring firms that invest in cleaner energy sources for furnace operations.
Company Profiles and Strategic Positioning
Major industry participants such as Danieli Group, SMS Group, and Tenova S.p.A are repositioning as full-service technology providers. These companies no longer just sell equipment; they provide integrated software platforms for energy management and predictive maintenance. Meanwhile, firms like Inductotherm Group and ABP Induction Systems leverage deep technical expertise in induction heating to dominate the bespoke and high-efficiency furnace segment, catering to both batch and continuous process facilities.
Porter’s Five Forces Assessment
The market experiences moderate competitive rivalry, intensified by the capital-intensive nature of furnace installations. Buyer power is high for large steel mills, while supplier power is concentrated regarding specialized induction technology components. The threat of substitution is low, given that hot dip galvanizing remains the gold standard for corrosion resistance, and entry barriers are significantly bolstered by complex environmental permits and the need for significant engineering expertise.
SWOT Analysis of the Industry
Strengths: Proven reliability and long-term durability. Weaknesses: High energy consumption and reliance on raw zinc price cycles. Opportunities: Integration of Industry 4.0 for process optimization and new high-performance alloys. Threats: Rising cost of environmental waste management and potential disruption from new nanotechnology-based coating substitutes. Companies like Shandong Huaxin Electric Furnace Co. Ltd. are already pivoting to mitigate these weaknesses through improved furnace thermal efficiency.
Industry Value Chain and Flow
The value chain begins with raw zinc sourcing and steel mill production. It flows through equipment providers like JP Steel Plantech Co. or ECM Technologies, who supply the induction and process lines to galvanizing plants. These plants then provide finished, corrosion-resistant products to final end-users in the Automotive and Architecture sectors. Efficiency at each stage—from metal pre-treatment to final coating thickness control—determines the profitability of the entire value stream.
Investment Insights and Strategic Recommendations
We recommend investment in high-throughput continuous galvanizing technology in rapidly developing industrial zones. Investors should prioritize partnerships with firms like EFD Induction Ltd or Ajax Tocco Magnethermic that specialize in decarbonization equipment. These firms are well-positioned for the shift toward Green Steel initiatives, where energy efficiency is no longer optional but a regulatory and competitive requirement for survival in the global supply chain.
Conclusion and Key Market Takeaways
The Hot Dip Galvanizing Market is entering a high-growth phase, projected to reach 128.35 Billion by 2033. The industry is moving beyond basic coating services toward value-added, sustainable manufacturing. Winners will be defined by their ability to integrate advanced automation and navigate tightening environmental regulations while maintaining operational flexibility to serve diverse sectors like automotive and civil infrastructure.
How is the baseline data for this research triangulated?
Our research methodology triangulates data from official trade registries, primary stakeholder interviews with CTOs of major furnace manufacturers, and macroeconomic output data from the World Steel Association. We reconcile these inputs against regional energy price trends and environmental compliance costs. This dual-layer approach ensures our 7.61% CAGR estimates and 128.35 Billion valuation account for both supply-side technological constraints and demand-side industrial growth patterns.
Scope and Parameters of the Research Report
This report evaluates the global Hot Dip Galvanizing Market with a focus on equipment, process technologies, and end-user segments. It covers developments across key global hubs through 2033. The scope includes batch and continuous galvanizing, excluding cold-dip or electrolytic methods where they do not overlap with hot-dip processes. The analysis is bounded by current technological readiness levels and projected global infrastructure spending patterns through 2033.
Recent Developments and Market Strategic Moves
Recent activity is marked by strategic acquisitions and R&D focus on energy reduction. Companies such as Elterma S.A. and Electrometalurgica S.A. have recently announced partnerships aimed at increasing the automation of zinc bath temperature control. These moves signal a broader industry trend toward precision manufacturing, where small adjustments in furnace efficiency result in significant cost reductions for end-users operating in the highly competitive Automotive and Architecture supply chains.