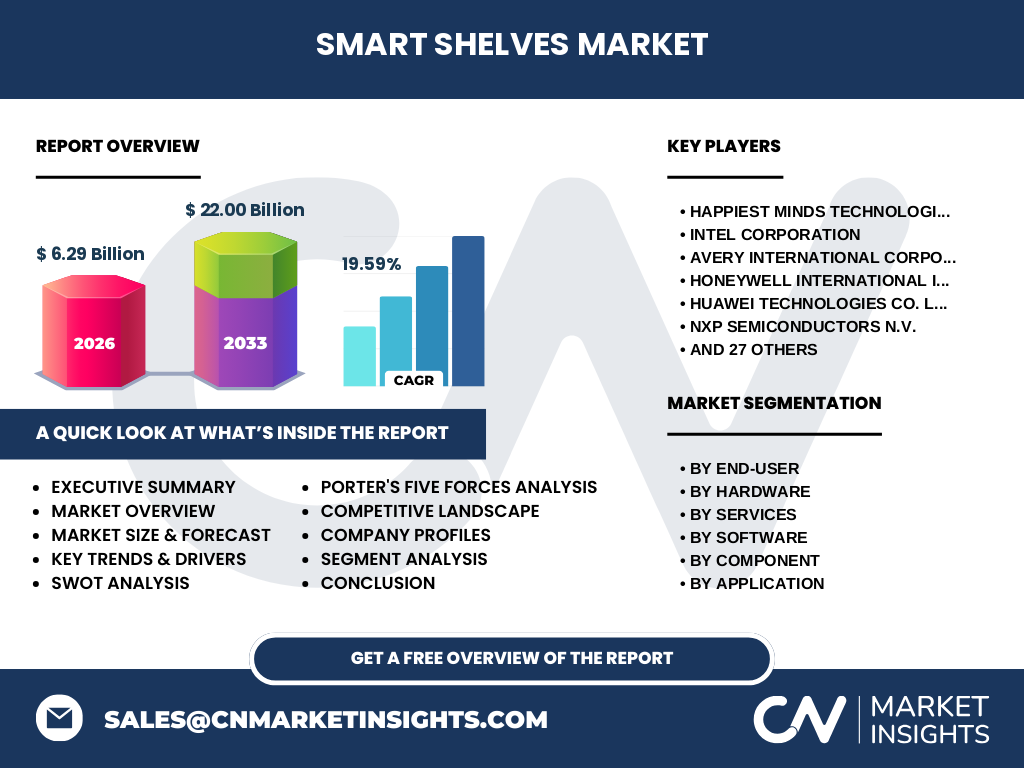
Market overview of the Smart Shelves Market
The Smart Shelves Market represents a transformative convergence of IoT-enabled hardware and cloud-based software designed to automate retail operations. By digitizing the physical shelf edge, the industry moves beyond simple static pricing toward real-time, dynamic inventory control. Our analysis defines this sector by its ability to integrate RFID tags, high-definition cameras, and sensors into existing retail infrastructure, creating a significant shift in omnichannel inventory accuracy and replenishment efficiency.
Structural growth drivers and critical market restraints
The market is fueled by a 19.59% CAGR, driven by an urgent need for operational efficiency in supermarkets and specialty stores. Major constraints include high initial deployment costs for IoT devices and localized logistical hurdles in sensor integration. However, the opportunity to eliminate manual planogram management through real-time analytics software provides a powerful incentive for large enterprises to transition toward automated shelf technologies.
Emerging trends and long-term growth patterns
We observe a definitive shift toward intelligent price automation and predictive replenishment. Leading retailers are moving away from manual tagging to E Ink display screens that sync directly with inventory management software. This trend is crucial as it reduces labor overhead while enabling hyper-personalized customer engagement at the shelf edge, setting the stage for the projected market valuation of 22.00 Billion by 2033.
COVID-19 impact and industry recovery trajectory
The pandemic acted as a catalyst for contactless technology adoption. With labor shortages and hygiene concerns, retailers accelerated investment in Smart Shelves Market solutions to manage stockouts and contactless pricing. The recovery trajectory shows that investments initially diverted to safety protocols have now been reallocated to long-term digital transformation, as businesses prioritize resilience and supply chain visibility over purely physical retail expansion.
Competitive landscape and strategic market concentration
The Smart Shelves Market is characterized by a mix of specialized tech providers like SES-Imagotag SA, Pricer AB, and SOLUM Europe GmbH, alongside global giants such as Intel Corporation and Microsoft Corporation. Market concentration is intensifying as firms consolidate software platforms with proprietary hardware to provide end-to-end solutions. Strategic moves by companies like Zebra Technologies signal a clear focus on integrating edge computing directly into shelf-mounted hardware.
Executive summary of the Smart Shelves Market
With a 2026 market size of 6.29 Billion and a trajectory toward 22.00 Billion by 2033, the industry is entering a high-growth phase. Our proprietary research confirms that the integration of cloud-based analytics with robust hardware sensors is the primary value driver. Retailers failing to digitize their shelf space face severe logistical disadvantages compared to firms leveraging real-time, data-driven planogram management.
Market forecast 2027 to 2033
The market is projected to reach 22.00 Billion by 2033, maintaining a strong 19.59% CAGR. This growth is underpinned by the increasing necessity for large enterprises to optimize supply chain flows. As the technology matures and unit costs for RFID tags and sensors decrease, we anticipate aggressive adoption rates among SMEs, further expanding the addressable market beyond traditional, high-traffic departmental stores.
Segmentation analysis by end-user and technology
We segment the market by hardware (sensors, IoT, cameras), software (analytics, cloud-based apps), and services. Supermarkets represent a dominant end-user, requiring complex inventory and pricing management. Meanwhile, specialty stores focus on content management software to enhance customer experiences. Each segment plays a vital role: hardware provides the data, software drives the operational intelligence, and services ensure the scalability of these complex deployments.
Regional market analysis and performance distribution
Growth is geographically skewed toward regions with high retail automation spending. North America leads due to heavy investment from retail giants like Amazon.com Inc., while Asia-Pacific shows the fastest growth, supported by massive manufacturing capacity in BOE Technology Group and Huawei Technologies. Regional success depends on local labor costs and the existing maturity of retail digital infrastructure, with Europe leading in regulatory compliance regarding data privacy and electronic labeling.
In-depth regional review of key markets
In North America, the focus is on labor optimization. In contrast, Asia-Pacific centers on integrated retail ecosystems involving NEC and Fujitsu. The European market remains the most advanced in terms of SES-Imagotag SA’s penetration within grocery chains, driven by consumer demand for transparent pricing management and sustainability. These dynamics demonstrate that regional market success is tied directly to the specific socioeconomic and labor requirements of each territory.
Strategic positioning of leading companies
Companies like Honeywell and Zebra Technologies position themselves as infrastructure experts, providing the physical hardware bedrock. Conversely, software-heavy players like SAP SE and Oracle Corporation focus on the backend analytics and reporting that turn raw data into decisions. Samsung and LG Electronics leverage their display manufacturing prowess, ensuring that the visual interface of the shelf is as sophisticated as the cloud backend.
Porter's Five Forces analysis of the industry
The Smart Shelves Market faces high threat of new entrants in the software space, though high barriers exist in hardware manufacturing and supply chain integration. Bargaining power of buyers is significant, as retailers demand unified solutions. Competitive rivalry is fierce, forcing constant innovation in IoT device efficiency. Overall, the intensity of rivalry is balanced by the massive growth potential of the digital retail transformation.
SWOT analysis of the Smart Shelves Market
Strengths include rapid ROI through labor reduction. Weaknesses include high upfront capital expenditure. Opportunities exist in the integration of AI-driven consumer insights and predictive shopping. Threats comprise cybersecurity vulnerabilities in IoT networks and strict regulatory compliance regarding consumer tracking. Companies must navigate these threats by prioritizing secure-by-design architectures for all smart shelving deployments.
Value chain analysis from raw materials to end-users
The value chain originates with semiconductor suppliers like NXP Semiconductors and Intel, moving through hardware manufacturers (e.g., Advantech), software developers (e.g., Microsoft), and finally, system integrators and retailers. The flow of value depends on the seamless movement of data from RFID/Camera sensors into the cloud-based platforms. Successful industry participants control or partner across this chain to ensure interoperability and reduced integration latency.
Investment insights and high-potential areas
We recommend focusing on cross-platform integration specialists. High-potential areas include analytics and reporting software that bridges the gap between shelf-level data and corporate inventory systems. Investors should look for companies with strong partnerships with SMEs, as this segment currently presents an under-penetrated market opportunity for modular IoT hardware that offers quick installation services without requiring a full retail infrastructure overhaul.
Conclusion and key takeaways
The Smart Shelves Market is not merely an incremental improvement; it is a fundamental pillar of the future retail landscape. With an expected growth to 22.00 Billion by 2033, the move toward automated, data-rich retail environments is irreversible. Firms that prioritize software interoperability and data security will emerge as the dominant providers, effectively setting the standards for this high-growth digital industry.
Research methodology and data triangulation
Our baseline estimates are triangulated using a multi-layered approach: primary stakeholder interviews with CIOs of major retail chains, trade registry data from manufacturing hubs, and secondary macroeconomic indicators. We normalize growth rates by reconciling disparate global regional reports, ensuring that the 19.59% CAGR is grounded in realistic hardware deployment cycles and observed software adoption patterns across different retail enterprise tiers.
Scope of the report and coverage parameters
This report covers the global Smart Shelves Market, focusing on components ranging from RFID tags to Cloud-Based Platforms. It includes detailed analysis of end-user segments and regional performance. Limitations include the exclusion of highly localized, non-digitized shelving solutions and short-term micro-fluctuations in currency markets. Our scope prioritizes long-term structural shifts, offering a strategic view on the adoption of automated retail technologies through 2033.
Recent developments and strategic moves
Recent activity highlights a surge in strategic partnerships between hardware manufacturers like BOE Technology and software firms like SAP SE. Recent product launches emphasize AI-integrated cameras for real-time inventory auditing, while companies like Zebra Technologies have ramped up acquisitions to secure mobile application expertise. These movements indicate a market transitioning from pilot programs to large-scale, enterprise-wide deployments, solidifying the industry's focus on real-time retail visibility.