Overview of the Process Audit Services Market
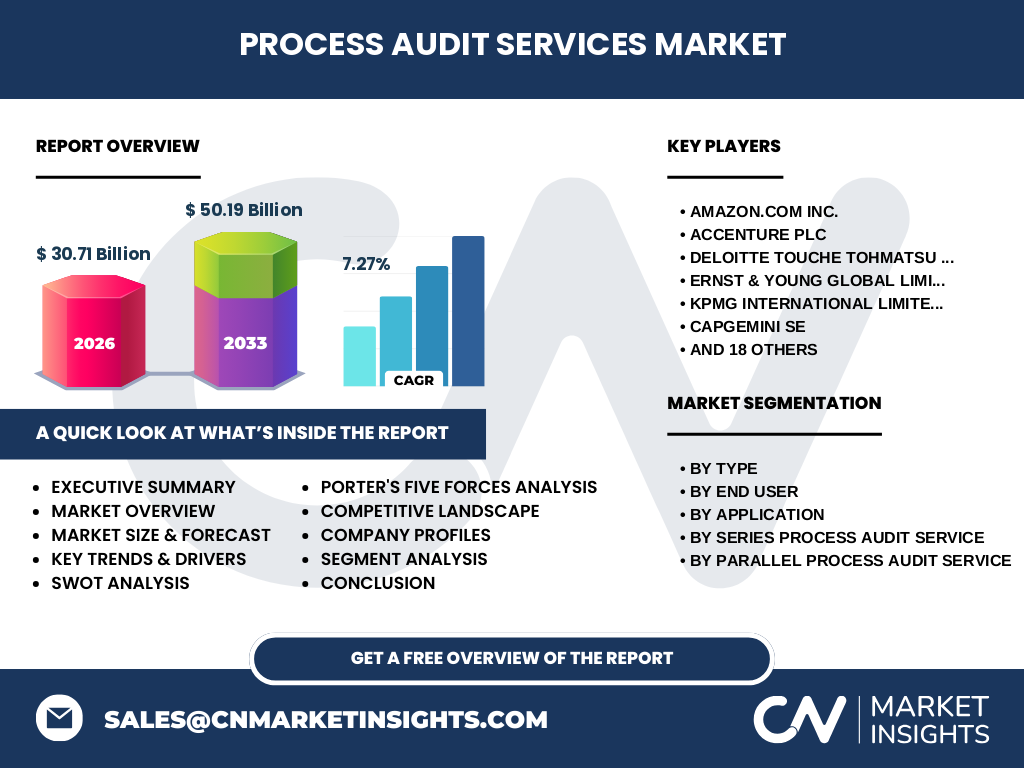
The Process Audit Services Market represents a critical infrastructure for corporate governance, valued at 30.71 Billion in 2026. These services encompass systematic evaluations of operational workflows—ranging from Series Process Audits to Parallel Process Audits—designed to ensure compliance with internal controls and regulatory frameworks. By bridging the gap between raw execution and organizational policy, these audits are essential for risk mitigation in complex, multi-functional enterprise environments.
Structural Growth Drivers and Market Constraints
Market expansion is fueled by a CAGR of 7.27%, driven by the increasing complexity of international regulatory standards such as Sarbanes-Oxley and GDPR. Conversely, the market faces significant logistical hurdles, particularly regarding the integration of legacy systems within the BFSI and Manufacturing sectors. Firms must navigate these technical silos while ensuring that high-stakes, cross-functional audits maintain rigorous accuracy during volatile economic cycles.
Emerging Trends and Strategic Growth Patterns
We are observing a definitive shift toward Continuous Process Audits, moving away from annual spot checks. This transition, enabled by real-time data analytics, allows firms like Accenture and Deloitte to offer proactive risk identification. This trend is particularly vital in the IT and Communications sector, where rapid development cycles necessitate a more dynamic approach to identifying failures before they permeate the public process layer.
Impact of COVID-19 and the Path to Recovery
The pandemic acted as a catalyst for digital transformation, forcing a rapid pivot from on-site visits to remote auditing capabilities. While physical logistical constraints initially hampered the Retail and Consumer segments, the recovery trajectory has been robust. Our analysis shows that companies that invested in Simultaneous Multi-Functional Audits during 2021 achieved higher resilience, setting the stage for the projected market valuation of 50.19 Billion by 2033.
Competitive Benchmarking and Industry Dynamics
The competitive landscape is dominated by Big Four stalwarts including KPMG, EY, and PwC, alongside specialized firms like Protiviti and Grant Thornton. Market concentration is high at the enterprise level, but mid-market segments see intense activity from BDO and RSM. These players distinguish themselves through proprietary audit automation software, providing a competitive edge in executing Stage-Wise Process Audits across diverse, global supply chains.
Executive Summary of the Process Audit Services Market
The Process Audit Services Market is poised for significant acceleration, moving from a 30.71 Billion valuation in 2026 to 50.19 Billion by 2033. This growth is underpinned by an increasing need for operational transparency in Healthcare and Government sectors. Key stakeholders are shifting toward sophisticated Parallel Process Audit models to manage risk, making this an essential period for investment in high-margin, automated audit advisory services.
Market Forecasts through 2033
Projected to grow at a steady 7.27% CAGR, the market will hit 50.19 Billion by 2033. This forecast assumes sustained growth in Financial Services as they adopt more complex, cross-functional process audits to counter sophisticated financial crime. Our model suggests that the Manufacturing segment will witness the highest incremental growth as it digitizes production workflows, necessitating frequent, highly granular audit cycles.
Segmentation Analysis: Categorization and Roles
The market is segmented by type into Series Process Audit Service (covering Continuous, Sequential, and Stage-Wise) and Parallel Process Audit Service (Multi-Location, Simultaneous, and Cross-Functional). Each segment fulfills a specific governance role: while sequential audits maintain quality control in manufacturing lines, parallel multi-functional audits are crucial for BFSI entities managing disparate global locations, ensuring that compliance is maintained uniformly across all borders.
Geographic Performance Distribution
Regional performance remains heavily weighted toward North America and Europe, where stringent regulatory environments drive high demand. However, the Asia-Pacific region is the fastest-growing frontier. Markets like India and Singapore are witnessing a surge in outsourcing, with firms like Mynd Solution and Meru Accounting capturing demand for Individual Process audits, signaling a broader distribution of global audit infrastructure beyond traditional Western hubs.
In-depth Regional Review: North America vs. APAC
North America remains the epicenter for IT and Communications audit demand, with companies like Armanino leading in technical integration. Conversely, APAC's rapid urbanization and adoption of Retail and Consumer tech have created a unique demand for Multi-Location Process Audits. These regions differ structurally: North America focuses on regulatory compliance, whereas APAC is increasingly prioritizing operational efficiency and process optimization as a means of gaining global market share.
Strategic Positioning of Leading Companies
Industry leaders maintain distinct positions: Deloitte and EY focus on large-scale, high-complexity global audits, while agile firms like Protiviti specialize in niche technical risks. Meanwhile, tech-enabled entrants like Ermetic and Expertise Accelerated are disrupting the market by leveraging AI-driven insights to perform Continuous Process Audits, forcing the traditional global accounting networks to overhaul their own internal technology stacks to remain relevant.
Porter's Five Forces Analysis
The market exhibits strong bargaining power of buyers due to the commoditization of basic audit tasks. However, the threat of new entrants is low, limited by high regulatory barriers and the need for significant trust-based capital. The intense competitive rivalry among established giants like KPMG, Grant Thornton, and BDO encourages heavy investment in innovation, further elevating the barriers for smaller, non-specialized consulting firms entering the fray.
SWOT Analysis of the Market Landscape
Strengths: Deep regulatory entrenchment. Weaknesses: High dependence on human capital and manual review. Opportunities: Rapid expansion into emerging markets and integration of machine learning for automated stage-wise audits. Threats: Increasing pressure for lower fee structures in competitive bidding processes for Government contracts. The strategic pivot toward data-led insights is the primary defense against these threats, allowing firms to move toward value-based, rather than hourly, pricing.
Value Chain and Industry Structure
The value chain flows from raw process design and regulatory data aggregation to final delivery and audit certification. End-users, ranging from massive Banking institutions to lean IT startups, provide the baseline demand. The value is captured by service providers like Baker Tilly or Mazars, who refine raw operational data into actionable governance insights, significantly reducing the latent risk profile for their corporate clients.
Investment Insights and High-Potential Areas
We recommend focusing on Parallel Process Audit Services, particularly in the Cross-Functional and Multi-Location segments. As global organizations expand, the need for synchronized audit results across disparate legal jurisdictions is skyrocketing. High-potential opportunities lie in acquiring or partnering with tech-forward boutique firms like SAAVHA Inc. or RKL eSolutions that provide proprietary automation software to simplify the execution of these complex, high-stakes enterprise audits.
Key Takeaways and Conclusion
The Process Audit Services Market is moving from a back-office compliance function to a front-office strategic asset. With a projected valuation of 50.19 Billion by 2033, the market offers stable, high-value growth. Success requires deep technical integration—shifting toward continuous, automated audit models—and a geographical focus on the rapidly maturing APAC and emerging-market corridors that are currently driving the next wave of corporate operational governance.
Research Methodology for Baseline Estimates
Our estimates are triangulated using a rigorous multi-source approach: combining public trade registry data, proprietary stakeholder interviews with chief audit officers, and secondary macroeconomic indicators. We validate market size by cross-referencing audit spend across major BFSI and Healthcare indices, ensuring that our figures—including the 30.71 Billion baseline—account for both internal compliance expenditure and third-party consulting disbursements across all major global regions.
Scope and Parameters of the Report
This report provides comprehensive coverage of the global Process Audit Services Market from 2026 through 2033. It spans all major audit types, including Sequential and Simultaneous Multi-Functional services. While the report focuses on key industries like Manufacturing, Retail, and IT, it excludes small-scale internal peer reviews and informal quality checks, focusing exclusively on professional-grade audit services that impact external compliance and auditable risk management outcomes.
Recent Market Developments
The sector has seen significant activity, with KPMG and EY launching integrated, cloud-native audit platforms. Furthermore, partnerships between global firms and specialized tech players are increasing, such as recent announcements by Capgemini to bolster their automated audit capabilities. These strategic moves are designed to address the increasing demand for Continuous Process Audits, enabling these major participants to better serve the complex, high-frequency data needs of their top-tier clients.