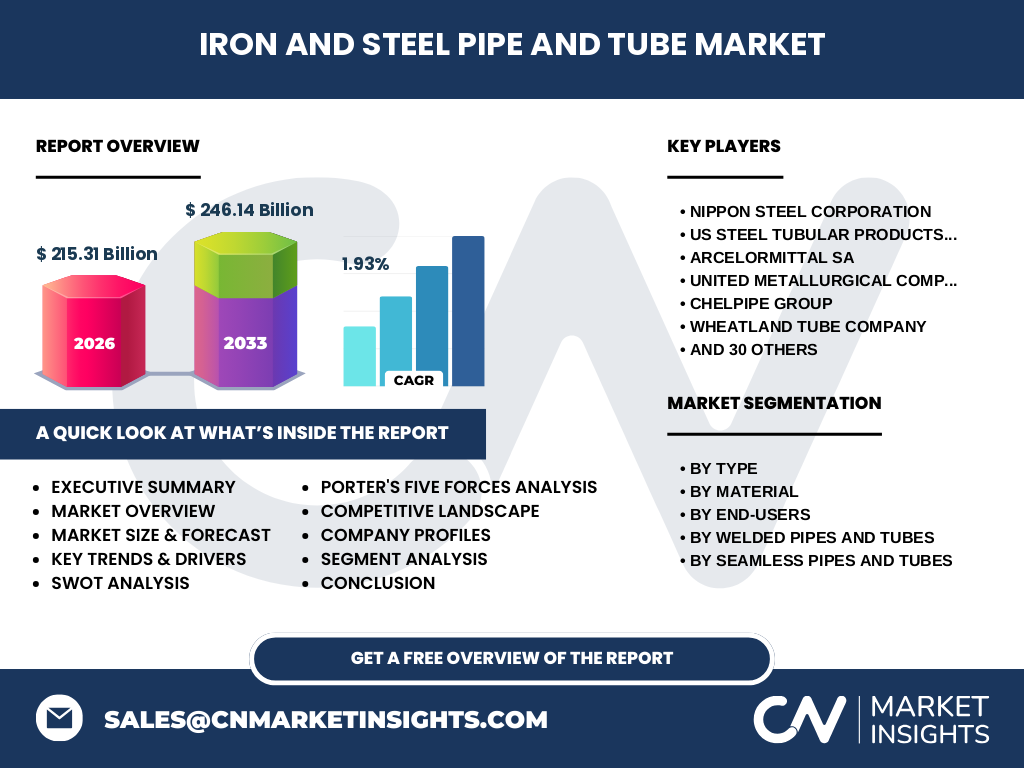
Market overview and industry significance of the Iron And Steel Pipe And Tube Market
The Iron And Steel Pipe And Tube Market serves as the industrial backbone for global energy, infrastructure, and automotive sectors. With a 2026 valuation of 215.31 Billion, this market encompasses complex manufacturing processes ranging from seamless to welded pipe production. These products are critical for fluid transport, structural integrity in high-pressure environments, and essential mechanical applications that drive international trade and regional urbanization efforts.
Structural Growth Drivers, Restraints, and Opportunities
Growth is largely dictated by infrastructure expansion and the energy transition. While rising demand for Carbon Steel and Alloy Steel pipes creates a robust opportunity, the market faces significant headwinds from raw material price volatility and stringent environmental regulations imposed by the EPA or EU. Opportunities lie in developing specialized, corrosion-resistant pipes that meet the demands of hydrogen transport and deeper offshore oil drilling projects.
Emerging trends and growth patterns in the Iron And Steel Pipe And Tube Market
The shift toward high-performance Stainless Steel and technologically advanced manufacturing is unmistakable. Industry leaders like Tenaris S.A. and Vallourec S.A. are increasingly focusing on digital pipe tracking and Industry 4.0 integration within their mills. This trend toward smarter, more durable steel products is optimizing life-cycle costs for end-users in the volatile Oil And Gas sector.
How did COVID-19 impact the sector and define the recovery trajectory?
The pandemic caused a disruption in global supply chains and a sharp contraction in demand for automotive-grade tubing. However, the recovery trajectory has been steady, bolstered by a post-pandemic surge in public infrastructure spending. Producers like ArcelorMittal SA adapted by diversifying their distribution channels, ensuring that supply could meet the rebound in demand for construction and power generation materials despite lingering logistical hurdles at key ports.
Competitive landscape and strategic dynamics
The market is highly fragmented with a mix of state-owned enterprises and private giants like Nippon Steel Corporation and JFE Holdings Inc. Competition is driven by production scale, technological intellectual property, and proximity to raw material sources. Strategic dynamics show a clear movement toward regionalization, where players like Nucor Corporation emphasize domestic sourcing to mitigate geopolitical risks and minimize import tariffs.
Executive summary of key findings
Our analysis reveals an Iron And Steel Pipe And Tube Market poised for steady growth. With a 2026 size of 215.31 Billion and a projected 2033 valuation of 246.14 Billion, the 1.93% CAGR reflects a mature but essential industry. Key findings highlight the dominance of welded pipes in construction and the increasing reliance on alloy-based metallurgical innovations to address harsher operational environments.
Projected growth from 2027 to 2033
The forecast suggests a total market valuation of 246.14 Billion by 2033, driven by a CAGR of 1.93%. This trajectory assumes consistent demand from the Power Generation and Construction sectors. Despite potential raw material fluctuations, our research indicates that investment in advanced ERW and SAW technology will sustain value creation for established manufacturers throughout this decade.
Segmentation analysis by type, material, and end-user
The market bifurcates into Seamless and Welded categories. Materially, it spans Carbon, Alloy, and Stainless Steel, plus Cast Iron. End-user applications are led by the Oil And Gas segment, which dictates demand for high-strength casing. Furthermore, ERW, Longitudinally Welded, Spiral, and SAW sub-segments provide technical diversity, ensuring specialized pipes exist for everything from high-pressure water transmission to automotive structural components.
Regional market analysis and geographic performance
Market performance is heavily localized, with Asia-Pacific holding a dominant share due to massive infrastructure projects in China and India. North American performance is largely correlated with shale energy output and local construction cycles. European markets are focusing on regulatory compliance and decarbonization of steel production, influencing trade patterns for participants like TMK Group and local specialty manufacturers.
In-depth regional review of key markets
In China, entities like Baoshan Iron and Steel benefit from vertically integrated supply chains. Conversely, the United States market, served by US Steel Tubular Products, faces unique cost pressures from labor and energy inputs. Emerging markets in Southeast Asia are seeing rapid adoption of imported high-grade tubes for regional power grid expansion, providing a growth vector for suppliers like Jindal Steel & Power Ltd.
Strategic positioning of leading companies
Companies are strategically positioning themselves through niche specialization. Ratnamani Metals & Tubes Ltd. thrives on Stainless Steel precision, while United States Steel Corporation leverages its legacy manufacturing footprint to maintain market share. Borusan Mannesmann exhibits strategic flexibility in the European market by focusing on high-value, medium-diameter pipes, demonstrating that operational agility is as vital as total output capacity in this competitive landscape.
Porter's Five Forces analysis
The industry experiences high rivalry due to commoditization and intense pricing pressure. Supplier power is moderate, resting on iron ore availability. Buyer power is significant, particularly in the bulk construction sector. The threat of substitutes is low, as iron and steel remain unparalleled in cost-to-strength ratios, while the threat of new entrants is constrained by high capital expenditure requirements for primary steel production mills.
SWOT analysis of the Iron And Steel Pipe And Tube industry
Strengths: Long-standing structural necessity. Weaknesses: High energy intensity in production. Opportunities: Sustainable green steel manufacturing and specialized alloys for hydrogen infrastructure. Threats: Volatile global trade policies and the risk of overcapacity from large, export-oriented players. Our analysis identifies that firms balancing ESG commitments with technical excellence will emerge as the long-term winners in this shifting global landscape.
Value chain analysis
The value chain originates from upstream raw material extraction (iron ore, coal) and moves through primary smelting and rolling mills. It progresses to pipe fabrication (welding/seamless processes) and ends at distribution centers or direct-to-site delivery for end-users. Efficiency is gained through vertical integration, a strategy masterfully employed by China Baowu Steel Group, which controls costs from the mine site all the way to final pipe fabrication.
Investment insights and high-potential areas
We identify high-potential growth in the Renewable Energy sector, specifically for pipes used in geothermal and solar thermal installations. Investors should focus on companies with high ESG transparency and R&D capability in alloy development. Furthermore, the maintenance and replacement cycle for aging global pipeline infrastructure in North America presents a reliable, long-term revenue stream for producers specializing in high-durability, corrosion-resistant steel products.
Conclusion and key takeaways
The Iron And Steel Pipe And Tube Market is fundamentally stable but shifting toward higher technological standards. With a market size of 215.31 Billion in 2026, the sector's evolution hinges on innovation in material sciences and the ability to navigate global trade complexities. Key takeaways include the necessity of regionalizing supply chains and the competitive advantage gained by early adoption of digital production technologies.
Research methodology for the Iron And Steel Pipe And Tube Market report
Our research methodology triangulates data from official trade registries, annual reports of publicly listed entities like Tata Steel Limited, and proprietary primary stakeholder interviews. We cross-reference these findings with macroeconomic indicators and sector-specific capacity utilization data to ensure accurate sizing and forecasting. This multi-layered approach filters out transient noise to provide a reliable, ground-truth perspective on the global pipe and tube industry.
Scope of the report
This report covers the global Iron And Steel Pipe And Tube Market, analyzing production, consumption, and trade flows. It includes segmentation by type, material, and end-user, with a specific focus on regional dynamics across North America, Europe, and Asia-Pacific. Limitations include the exclusion of non-ferrous metal pipes, focusing exclusively on iron-based products to ensure the precision and depth required for strategic executive decision-making.
Recent developments in the market
Significant recent developments include strategic partnerships between major producers to develop carbon-neutral pipe production. Announcements from companies like Maharashtra Seamless Limited and Tenaris S.A. regarding the expansion of their seamless pipe capacity indicate a bullish outlook for high-pressure application markets. Furthermore, increased M&A activity, particularly in the mid-tier steel segment, is consolidating power and optimizing logistical footprints across competitive regional hubs.