Market Overview: Defining the Home Furnishings Stores Market landscape
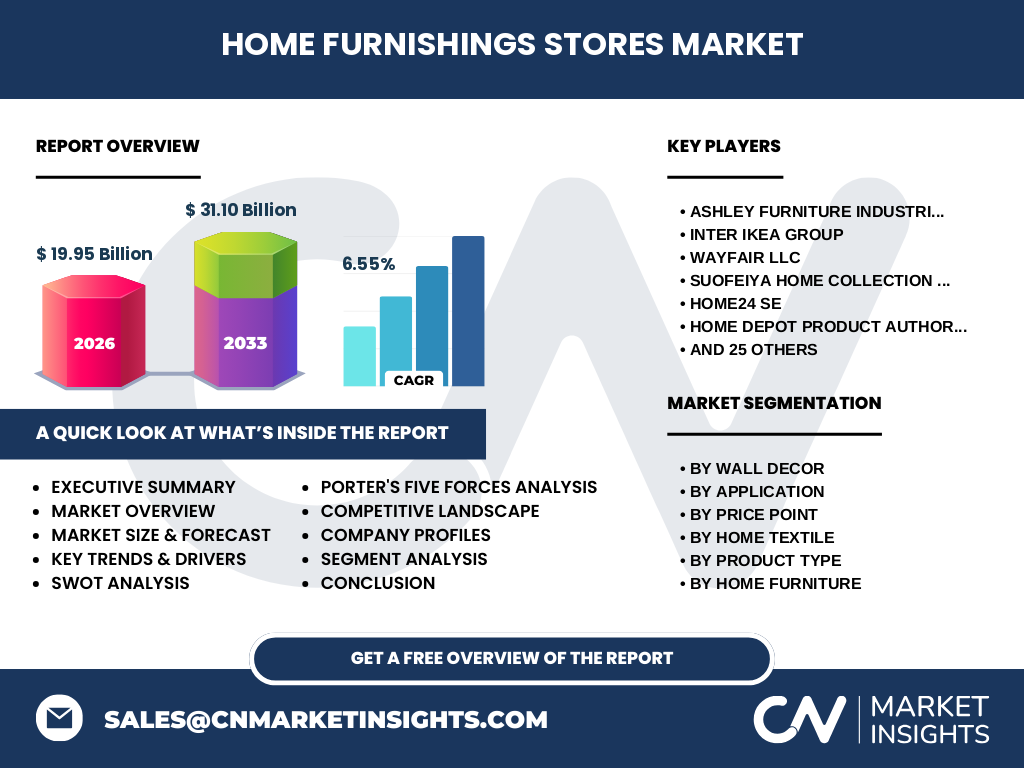
The Home Furnishings Stores Market encompasses retail entities specializing in essential domestic assets, from living room furniture to textiles. Our analysis defines this sector as a critical pillar of consumer discretionary spending, currently valued at 19.95 Billion in 2026. The scope includes brick-and-mortar storefronts and digital-first retailers facilitating domestic interior transformation, serving as a vital barometer for broader real estate and economic stability.
Structural Growth Drivers and Market Constraints
The market is anchored by a 6.55% CAGR, fueled by urbanization and the rise of remote work requiring specialized office furniture. However, growth faces headwinds from supply chain volatility at major ports and fluctuating raw material costs. Strategic opportunities exist in technological integration, specifically for players like Wayfair LLC or Inter IKEA Group, who are leveraging digital tools to mitigate the challenges of traditional inventory-heavy logistical models.
Emerging Trends and Strategic Growth Patterns
A pivot toward personalized home curation is redefining industry trends. We observe a rise in premium home decor segments as consumers seek long-term investment pieces over disposable items. Sustainable material sourcing and circular economy initiatives are no longer optional but core competitive advantages, forcing firms to align with evolving regulatory standards regarding timber sourcing and chemical safety protocols.
COVID-19 Impact and Recovery Trajectory
The pandemic catalyzed an unprecedented demand spike, fundamentally altering household consumption of bedroom furniture and office setups. Following the initial surge, the market experienced a supply-side crunch. Our assessment indicates a normalized, resilient recovery trajectory, with firms like Williams Sonoma Inc. successfully pivoting to hybrid models to manage the long-term impact of supply chain disruptions while maintaining customer loyalty.
Competitive Benchmarking and Market Concentration
The landscape is a high-stakes arena featuring giants like Ashley Furniture Industries Ltd, Ethan Allen, and RH. Concentration is split between specialized retailers and broad-market behemoths like Home Depot Product Authority LLC. Success depends on proprietary omni-channel logistics and regional density. Smaller players increasingly focus on niche wall décor segments to differentiate themselves from high-volume, low-cost incumbents.
Executive Summary: Key Findings in the Home Furnishings Stores Market
The Home Furnishings Stores Market is poised for sustained expansion, projected to reach 31.10 Billion by 2033. This growth is underpinned by digital sales acceleration and a structural shift in home-centric lifestyle preferences. Our findings suggest that firms prioritizing brand equity in home textiles and storage solutions will outperform, provided they can master the complexities of global logistics and changing consumer sentiment.
Market Forecast: 2027 to 2033 Projections
Based on quantitative modeling, we project the sector to grow from its 2026 valuation to 31.10 Billion by 2033. The 6.55% CAGR represents a steady maturation phase as E-Commerce Sales continue to capture greater market share. Investors should expect high volatility in short-term cycles, but the long-term outlook remains bullish due to rising demand for multifunctional dining room furniture.
Segmentation Analysis: Breaking Down the Industry
The market is segmented by Product Type (Home Furniture, Home Textile, Wall Décor), Application, and Price Point. Wall décor—covering paintings, stickers, and mirrors—serves as a high-margin gateway, while Home Furniture remains the volume driver. This segmentation allows retailers like Crate & Barrel to capture distinct customer profiles across varying economic cycles, from mass-market buyers to luxury connoisseurs.
Regional Market Performance and Distribution
Geographic performance is heavily tied to housing starts and consumer confidence indices. North America leads due to home ownership rates and significant retail infrastructure. Europe follows with high demand for curtains, drapes, and rugs, driven by interior aesthetic trends. Emerging Asian markets are seeing aggressive expansion from companies like Suofeiya Home Collection Co Ltd, reflecting a shift toward modern, modular residential design.
In-Depth Regional Review of Key Markets
The US market remains dominant, supported by regional leaders like Nebraska Furniture Mart and Living Spaces, who utilize massive distribution hubs. Conversely, European markets face stringent sustainability regulations, favoring companies that adopt eco-certified bed linens and towels. Our analysis shows that success in these regions requires localized logistics to navigate domestic zoning and labor-cost variations.
Company Profiles: Strategic Positioning
Leading entities like La Z Boy and Bassett Furniture leverage strong brand legacies to dominate the comfort segment. Meanwhile, Wayfair LLC prioritizes data-driven inventory turnover. Arhaus and Ballard Designs command the premium tier through curated craftsmanship. Each company’s strategy reflects a deliberate choice: scale through mass-market retail versus brand-led differentiation in the high-end home furnishings space.
Porter’s Five Forces Analysis
Competitive rivalry is intense, with low switching costs for consumers in the mass segment. The threat of substitutes is moderate, primarily from second-hand markets. Bargaining power of suppliers is significant for specialized rugs and carpets, while the power of buyers is amplified by the transparency of online price comparison tools, putting constant pressure on retail margins.
SWOT Analysis: Home Furnishings Stores Market
Strengths include robust omni-channel infrastructure; weaknesses center on capital-intensive inventory management. Opportunities abound in smart furniture integration and AI-driven personalization, while threats include macroeconomic inflation and global shipping bottlenecks. This analysis confirms that companies adept at supply chain agility and digital-physical integration possess the strongest defensive moats against market uncertainty.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with raw timber, textile fibers, and plastics. Manufacturers transform these into finished goods before moving them through regional ports to distribution centers. Retailers like Leons Furniture or Dufresne Furniture & Appliances serve as the final touchpoint. Our model reveals that value is increasingly captured at the final mile delivery and design consultation stages rather than manufacturing.
Investment Insights and High-Potential Areas
Investors should scrutinize companies demonstrating technological proficiency in supply chain transparency. High-potential areas include modular storage solutions and sustainable textile sourcing. Given the 6.55% CAGR, we recommend prioritizing firms with strong balance sheets that can withstand higher interest rate environments, as these players are best positioned to acquire smaller, niche competitors in the fragmented wall decor market.
Conclusion and Key Takeaways
The Home Furnishings Stores Market is undergoing a radical digital-first transition. With a target valuation of 31.10 Billion by 2033, the industry rewards those who balance high-touch customer service with efficient automated logistics. The winning strategy involves deep integration between home furniture product lines and seamless e-commerce experiences, ensuring brands remain relevant in the evolving consumer landscape.
Research Methodology: Triangulation of Data
Our estimates are triangulated through a rigorous three-pillar approach: proprietary stakeholder interviews with retail executives, trade registry data analysis of regional import-export volumes, and secondary macroeconomic indicators. This methodology ensures our projections for the Home Furnishings Stores Market reflect both real-world logistical constraints and high-level economic shifts, providing a validated basis for strategic planning.
Scope of the Report: Parameters and Limitations
This report covers the global Home Furnishings Stores Market, focusing on retail distribution of furniture, textiles, and wall décor. While it examines major players like Raymour & Flanigan and Bernie & Phyls Furniture, it excludes small-scale artisanal craft markets. The projections are based on current market dynamics and assume continued international trade stability, acknowledging potential risks related to global geopolitical volatility.
Recent Developments in the Sector
Recent strategic moves emphasize digital-first pivots. Major announcements involve partnerships between e-commerce innovators and traditional furniture retailers to optimize delivery speed. Furthermore, investments in sustainable packaging and blockchain-based supply chain tracking are increasing among top-tier brands. These developments signal a wider industry commitment to modernizing the customer experience while addressing long-standing inefficiencies in furniture transportation and handling.