Market overview of the Rigid Mine Dumper Market
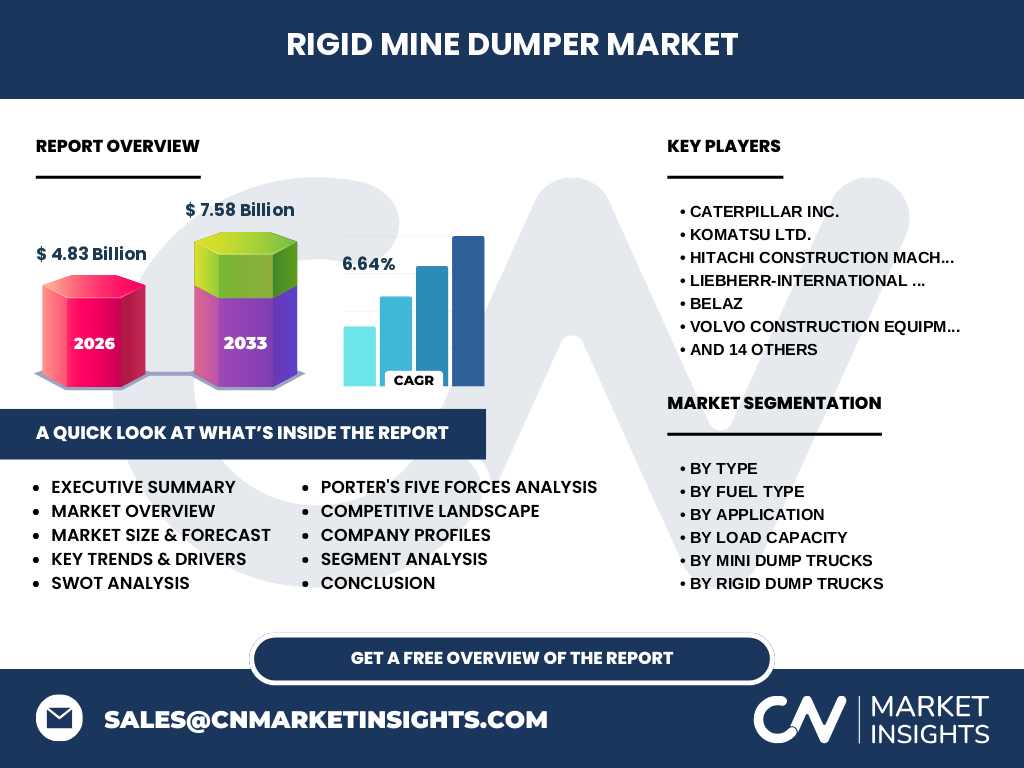
The Rigid Mine Dumper Market constitutes a critical pillar of global extractives, valued at 4.83 Billion in 2026. It encompasses the design and deployment of specialized heavy-duty haulage equipment, primarily utilized in open-pit operations. This sector serves as the backbone for commodity transport, facilitating the movement of iron ore, copper, and coal. Its significance lies in its mechanical durability under extreme geological conditions and high-stress operational environments.
Structural growth drivers and core market challenges
Growth is primarily driven by rising mineral demand and the transition toward autonomous hauling systems. However, the industry faces significant logistical hurdles, including severe supply chain constraints for specialized steel components and rigorous environmental mandates from bodies like the EPA and EU mining regulators. Opportunities lie in scaling high-capacity rigid dump trucks that optimize the cost-per-ton metrics for tier-one mining firms operating in remote, high-altitude sites.
The shift toward electrification and automation trends
The market is witnessing a fundamental pivot toward electric and hybrid haulage solutions to mitigate carbon footprints. Key innovators like Epiroc AB and Sandvik AB are spearheading the transition to battery-electric drivetrain technology. This trend is not merely environmental; it is a strategic operational shift aimed at reducing long-term maintenance costs and noise pollution, which is essential for compliance in increasingly regulated quarrying and mining zones.
COVID-19 impact analysis and recovery trajectory
The COVID-19 pandemic introduced severe supply chain bottlenecks and labor shortages that stalled capital expenditure in mining projects. Recovery has been robust, driven by a surging commodity supercycle. Our analysis shows that manufacturers, including Caterpillar Inc. and Komatsu Ltd., have since successfully pivoted to modular production, enabling a swifter delivery cadence despite lingering macroeconomic volatility in global shipping logistics.
Competitive benchmarking and strategic dynamics
The landscape is dominated by heavyweights like Caterpillar Inc., Komatsu Ltd., and BelAZ, which hold significant market concentration. Strategic dynamics are defined by high barriers to entry due to the immense R&D required for autonomous technology. Tier-two players such as Shaanxi Tonly Heavy Industries are rapidly gaining traction by offering localized, cost-effective alternatives in emerging markets, forcing established incumbents to accelerate their own innovation pipelines.
Executive summary of the Rigid Mine Dumper Market
The Rigid Mine Dumper Market is poised for substantial expansion, with a forecasted value of 7.58 Billion by 2033, reflecting a steady CAGR of 6.64%. This growth is underpinned by technological advancements in super high capacity vehicles and the strategic modernization of mining fleets. Our research highlights that capital investment remains concentrated in large-scale infrastructure projects and high-intensity mining hubs requiring superior payload efficiency.
Market forecast 2027-2033
Our projections indicate that the market will maintain a steady growth trajectory, escalating from 4.83 Billion in 2026 to reach 7.58 Billion by 2033. This CAGR of 6.64% is supported by the sustained demand for large capacity rigid dump trucks. As mining companies replace aging, inefficient fleets with high-capacity, low-emission models, we anticipate a sharp uptick in revenue for manufacturers capable of scaling production to meet global demand.
Segmentation analysis of the industry
The market is segmented by Type (Articulated, Rigid, Mini), Fuel Type (Diesel, Electric, Hybrid), and Load Capacity. The Rigid Dump Truck segment remains the most vital for large-scale operations. Meanwhile, the Electric Powered segment is expected to see the highest growth rate as mining operators strive to meet international sustainability goals, effectively reducing the reliance on volatile fossil fuel prices while improving site-specific energy management.
Regional market analysis and performance trends
Geographically, the Asia-Pacific region remains the market leader, fueled by massive infrastructure projects and robust mining sectors in China and Australia. North America and Latin America follow, with significant investment in copper and iron ore extraction. Localized regulatory frameworks and geographical accessibility (such as port proximity) dictate regional demand, with players like SANY and Hitachi Construction Machinery optimizing their regional supply chains to capture share in these high-growth environments.
In-depth regional review
The Australian market is characterized by a demand for super high capacity dump trucks due to vast, isolated iron ore operations. Conversely, European markets prioritize electrified, compact equipment for tighter, regulation-heavy quarrying applications. Our research shows that Caterpillar Inc. maintains its dominant footprint by tailoring its product portfolio to meet these specific, localized legislative requirements and demanding geological terrain, effectively outperforming regional competitors who lack similar global distribution capabilities.
Strategic positioning of leading companies
Leading companies leverage unique strategic moats: Caterpillar Inc. and Komatsu Ltd. dominate through integrated autonomous software ecosystems. BelAZ maintains a niche advantage with ultra-large haulers, while Volvo Construction Equipment leverages its extensive R&D in hybrid systems. XCMG and SANY are aggressively expanding their footprint through price-competitive, feature-rich hardware, creating a highly competitive environment that pushes incumbents to prioritize total cost of ownership improvements over initial purchase price alone.
Porter's Five Forces analysis
The Rigid Mine Dumper Market faces high supplier power regarding electronic control modules and raw steel components. Competitive rivalry is fierce, intensified by technological parity among incumbents. The threat of substitutes is low, given the unmatched productivity of rigid dumpers in mining. Meanwhile, high capital requirements act as a formidable entry barrier, protecting the current landscape and ensuring that market dynamics remain focused on technological innovation rather than simple commoditization.
SWOT analysis of the sector
Strengths: Established global infrastructure and high-utility product demand. Weaknesses: High manufacturing costs and reliance on specific raw materials. Opportunities: Rapid integration of autonomous navigation systems and electric drivetrain adoption. Threats: Fluctuating commodity prices and tightening global emission regulations. Our SWOT assessment suggests that firms focusing on modular design and long-term service contracts are best positioned to neutralize threats and capitalize on growth opportunities in the coming decade.
Value chain analysis
The value chain originates with raw material suppliers (steel, rare earth magnets for motors) feeding into component manufacturers. Original Equipment Manufacturers (OEMs) like Terex Corporation and Doosan Infracore assemble these units, distributing them via global dealer networks to the end-users. The downstream segment—maintenance, predictive servicing, and software updates—is becoming a primary value generator, shifting the industry model from hardware sales to lifecycle fleet management.
Investment insights and high-potential areas
Investors should target companies leading in autonomous, zero-emission hauling. The data suggests that firms prioritizing low-capacity, electric-ready platforms for emerging quarrying markets will see faster ROI. Furthermore, strategic investment in aftermarket predictive analytics providers represents a high-potential area, as major miners seek to maximize the uptime and efficiency of their heavy-duty fleets to navigate the increasing complexity of modern mining operations and site management.
Conclusion and key takeaways
The Rigid Mine Dumper Market is set for transformative growth through 2033. Key takeaways emphasize the move toward automation and electrification as primary competitive differentiators. Stakeholders should focus on the 7.58 Billion market valuation target by aligning product development with the industry's shift toward operational efficiency, sustainability, and data-driven fleet management. Success will require balancing local regulatory compliance with global technological consistency.
Research methodology overview
Our methodology utilizes triangulation between trade registry data, annual reports, and primary interviews with Chief Technology Officers at major mining firms. We cross-reference macroeconomic indicators, such as global commodity price indices, with supply chain throughput data. This rigorous analytical approach ensures that our estimates account for both historical market behavior and forward-looking trends, providing a highly accurate baseline for our 2027 to 2033 forecasts.
Scope of the report
This report covers the Rigid Mine Dumper Market globally, analyzing segments including Articulated, Rigid, and Mini dump trucks. It examines impacts across mining, construction, and quarrying applications. The research scope includes major geographic regions and a comprehensive profile of key industry participants. Constraints include data limitations in specific emerging markets; however, our projections rely on localized, verified data points to maintain a high degree of confidence.
Recent developments and strategic moves
Recent industry news highlights a surge in joint ventures between traditional heavy-machinery OEMs and software firms to accelerate AI-based mining solutions. Major players like HD Hyundai Infracore and Ashok Leyland have recently announced significant expansions into modular, electric, and autonomous haulage lines. These developments signify a strategic race to market for the next generation of eco-friendly, highly autonomous, and efficient mine dumper equipment.