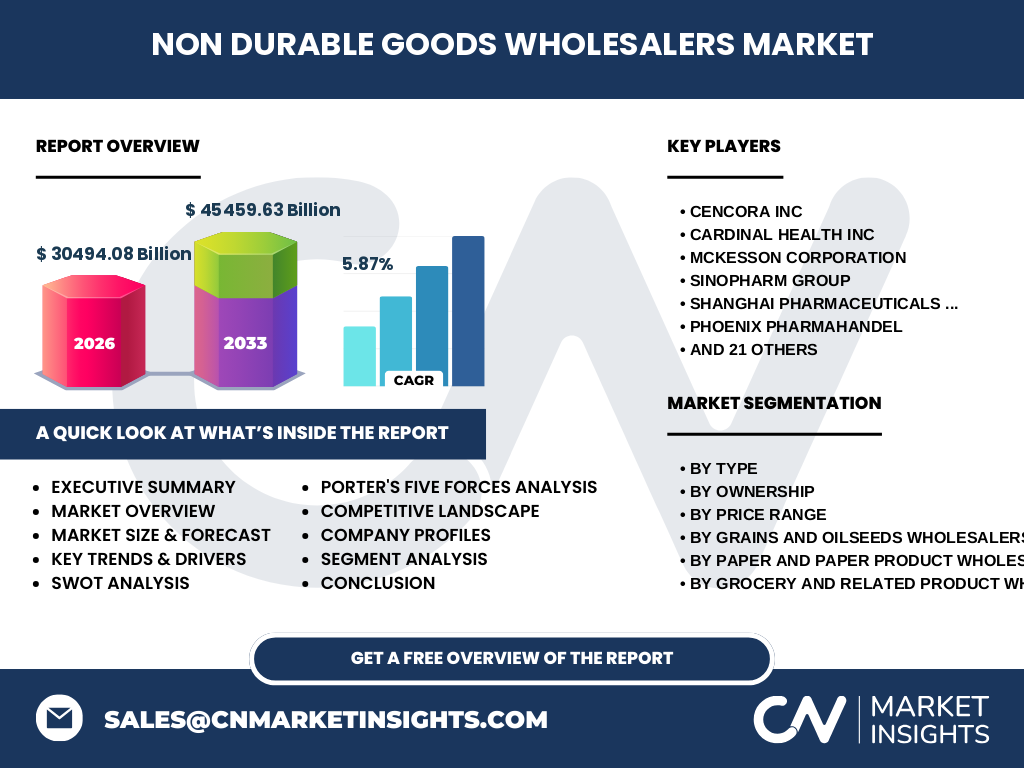
Overview of the Non Durable Goods Wholesalers Market scope
The Non Durable Goods Wholesalers Market functions as the critical circulatory system of the global economy, facilitating the movement of products with a shelf life of under three years. Valued at 30494.08 Billion in 2026, this sector bridges producers of perishable commodities, such as food and chemicals, with retail and industrial end-users. It is characterized by high-volume, low-margin operations where logistical precision and inventory turnover rates dictate overall financial viability.
Structural Growth Drivers and Market Constraints
Growth is primarily propelled by rapid urbanization and rising middle-class consumption, necessitating sophisticated cold-chain logistics. Conversely, the market faces significant restraints from volatile commodity prices in agriculture and petroleum. Key challenges include maintaining compliance with stringent FDA and USDA regulations, while the primary opportunity lies in digital transformation, as wholesalers integrate predictive analytics to optimize stock levels and reduce the fiscal burden of spoilage in fresh produce and pharmaceutical lines.
Emerging Trends Reshaping Wholesale Dynamics
We observe a distinct shift toward transparency, where end-to-end traceability is becoming the industry standard. Automation and robotics in high-density distribution centers are enabling faster throughput for Drugs and Druggists Sundries Wholesalers. Additionally, there is a marked trend toward sustainability-focused procurement, as major distributors respond to consumer demand for ethically sourced apparel and eco-friendly packaging materials within the Paper and Paper Product Wholesalers segment.
COVID-19 Impact and Recovery Trajectory
The pandemic acted as a violent stress test, exposing systemic vulnerabilities in global supply chains. While Grocery and Related Product Wholesalers saw explosive short-term demand, they struggled with labor shortages and port congestion. Our analysis shows a robust recovery characterized by increased resilience investments. Companies have shifted from 'just-in-time' to 'just-in-case' inventory strategies, heavily supported by diversified supplier networks to mitigate future disruptions in critical sectors like chemical and medical supplies.
Competitive Landscape and Strategic Dynamics
The market displays a tiered concentration with global giants like McKesson Corporation and Cencora Inc dominating the pharmaceutical space, while Sysco Corporation maintains a strong hold on food distribution. Smaller independent wholesalers compete by specializing in niche regional commodities. The competitive dynamic is shifting toward M&A activity, as firms like Bunzl plc acquire smaller regional players to achieve economies of scale and geographic dominance in the fragmented miscellaneous non-durable goods market.
Executive Summary: Synthesis of Market Findings
The Non Durable Goods Wholesalers Market is positioned for steady expansion, with a projected value of 45459.63 Billion by 2033. This growth, reflecting a CAGR of 5.87%, is underpinned by the resilience of essential goods supply chains. Strategic success will hinge on operational agility, technological adoption in warehouse management, and the ability of firms to navigate inflationary pressures while maintaining optimal distribution efficiency across diverse product categories.
Market Forecast for 2027 to 2033
Projected data indicates the market will reach 45459.63 Billion by 2033, growing at a CAGR of 5.87%. This trajectory assumes consistent demand for essential raw materials and finished non-durable consumer goods. We anticipate that Petroleum and Petroleum Products Wholesalers will experience fluctuations linked to energy transition trends, whereas Drugs and Druggists Sundries Wholesalers will likely sustain the most stable growth due to aging global demographics.
Segmentation Analysis: Breaking Down the Industry
Market segmentation includes highly specialized categories ranging from Farm Product Raw Material Wholesalers to Beer, Wine, and Distilled Alcoholic Beverage Wholesalers. These segments represent distinct functional roles: raw materials fuel manufacturing, while Grocery and Apparel wholesalers drive the retail value chain. Ownership structures—divided between Wholesale Chains and Independent entities—further segment the competitive landscape, influencing pricing models from economy-focused to premium distribution services.
Regional Market Analysis: Geographic Performance
Regional performance is dictated by infrastructure maturity and proximity to major trade hubs. North America and Europe remain the largest markets, heavily reliant on sophisticated intermodal logistics. In contrast, the Asia-Pacific region demonstrates the fastest growth, driven by rapid industrialization in the chemical sector and expanding middle-class consumption. Our analysis suggests that regional regulatory alignment remains the greatest hurdle for cross-border expansion in the non-durable goods sector.
In-depth Regional Review: Key Geographic Markets
In North America, US Foods and Performance Food Group leverage mature cold-chain networks. Europe focuses on sustainability compliance, impacting how METRO AG manages its wholesale operations. Meanwhile, the Asia-Pacific market—led by players like Zuellig Pharma and Sinopharm Group—is undergoing rapid digital integration. These regions remain distinct: one prioritized by operational scale, the other by rapid market penetration and infrastructure development in emerging economies.
Company Profiles: Strategic Positioning
Key market participants such as Cencora Inc and Cardinal Health Inc demonstrate clear focus on high-value pharmaceutical distribution. Conversely, Sysco Corporation and Performance Food Group emphasize logistics optimization for food services. Brenntag SE leads in chemical distribution, showcasing the value of deep technical expertise. Each entity maintains its market share by focusing on vertical integration and proprietary logistics networks that are difficult for new entrants to replicate.
Porter's Five Forces: Competitive Forces Assessment
The Non Durable Goods Wholesalers Market faces intense internal rivalry among established incumbents. The threat of new entrants is moderate, restricted by high capital requirements for warehousing. Bargaining power of buyers is significant due to retail consolidation, while bargaining power of suppliers is tempered by the high volume of goods moved. Threat of substitutes is low for essential goods, but technological disruption is changing how buyers interact with wholesalers.
SWOT Analysis: Strategic Outlook
Strengths lie in deep supply chain expertise and established logistics networks. Weaknesses include high operational costs and sensitivity to fuel prices. Opportunities are abundant in digital integration, such as AI-driven inventory forecasting and B2B e-commerce platforms. Threats include rising protectionist trade policies, stricter environmental regulations regarding single-use plastics, and the potential for direct-to-consumer models to bypass traditional wholesale distribution channels in specific, high-margin product segments.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates at primary production—farms, chemical plants, or refineries. Wholesalers like World Fuel Services or Associated Wholesale Grocers add value through aggregation, storage, and breaking bulk. The flow continues to secondary manufacturers or retail outlets. The critical value-add provided by wholesalers is not merely transport, but the risk mitigation of inventory management, financing the gap between supplier payment and retail collection.
Investment Insights: Strategic Recommendations
Investors should target wholesalers investing in proprietary technology platforms that enable real-time inventory visibility. We recommend prioritizing sectors with high barrier-to-entry, specifically Pharmaceutical and Healthcare supply chains, given their growth resilience. High-potential areas also exist in cold-chain infrastructure modernization within emerging markets. Avoiding segments heavily exposed to volatile raw commodity pricing without hedging capabilities is a primary recommendation for maintaining portfolio stability.
Conclusion and Key Takeaways
The Non Durable Goods Wholesalers Market is evolving from a traditional logistics provider into a technology-driven supply chain partner. With a projected value of 45459.63 Billion by 2033, the market offers significant opportunities for firms that prioritize operational visibility and sustainability. Success requires balancing regional regulatory complexities with the agility to adopt digital innovations that reduce waste and optimize distribution across the entire global non-durable ecosystem.
Research Methodology for Baseline Estimates
Our estimates are triangulated through a robust methodology combining primary interviews with C-suite stakeholders at leading distributors, analysis of trade registry data, and secondary macroeconomic indicators. We cross-reference import-export volumes across major global ports with industry-specific growth rates. This proprietary approach ensures that our CAGR of 5.87% accounts for both structural market shifts and short-term economic fluctuations in the non-durable goods landscape.
Scope and Parameters of the Report
This report covers global Non Durable Goods Wholesalers operations, including Paper, Drugs, Grocery, Petroleum, and Chemical segments. It excludes long-lived durable assets such as machinery or consumer electronics. The scope is limited to wholesale-level transactions and does not explicitly analyze retail or direct manufacturing sales, except where such entities perform wholesale functions. Geographies include North America, Europe, APAC, and RoW, providing a comprehensive view of industry performance.
Recent Developments: Strategic Moves
The industry is seeing aggressive M&A activity to bolster regional footprints. Recent announcements reflect a focus on digital supply chain tools, with companies like United Natural Foods Inc and SpartanNash investing heavily in logistics software. Strategic partnerships between Chemical Wholesalers and local logistics providers are becoming standard to navigate local regulatory constraints. These developments underscore the industry-wide shift toward tech-enabled resilience and localized operational efficiency.