Market overview of the Steel Piston Market
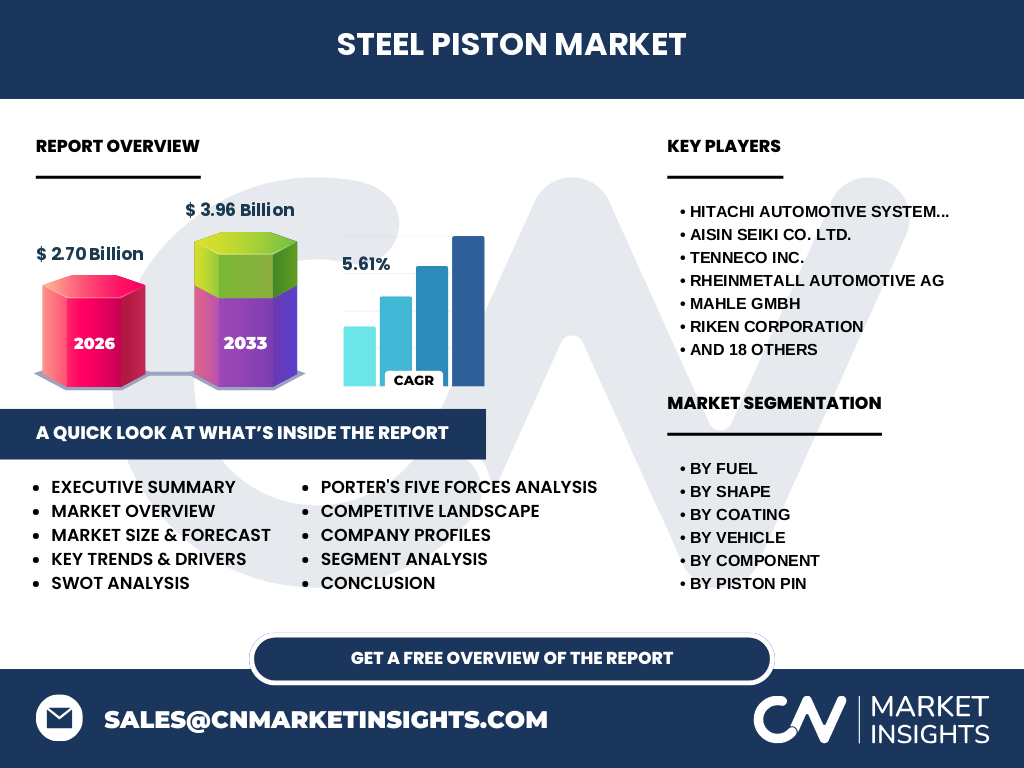
The Steel Piston Market is a critical segment of the automotive drivetrain industry, valued at 2.70 Billion in 2026. It encompasses the design, manufacturing, and distribution of robust steel components engineered for high-pressure combustion environments. As heavy-duty applications demand superior thermal management, steel pistons have become the gold standard over traditional aluminum, representing a vital pillar for modern engine efficiency and structural integrity in both light and heavy commercial vehicles.
Structural Growth Drivers and Market Constraints
The shift toward high-performance combustion drives the 5.61% CAGR, as steel outperforms aluminum in extreme thermal stress conditions. Regulatory hurdles, specifically Euro 7 emissions standards and EPA mandates, force manufacturers toward higher compression ratios, fueling demand. Conversely, the transition to battery-electric powertrains serves as a long-term restraint, necessitating that manufacturers like Mahle GmbH and Rheinmetall Automotive AG diversify into thermal management technologies beyond conventional internal combustion components.
Emerging trends and growth patterns in the sector
We are observing a pivotal transition toward thin-walled steel designs, which optimize weight while maintaining the structural integrity required for high-torque diesel engines. Innovations in dry film lubricant and thermal barrier coatings are redefining durability standards. Companies such as Riken Corporation are at the forefront of this trend, integrating proprietary coating technologies to minimize friction losses and boost fuel efficiency, thereby meeting stringent global decarbonization targets.
COVID-19 impact analysis and recovery trajectory
The pandemic caused a disruption in the global supply chain, particularly affecting raw material sourcing for forged piston heads. However, the recovery trajectory is robust, with the market rebounding as HCV production scales back up globally. Our research indicates that manufacturers like Shriram Pistons & Rings Ltd. successfully navigated the logistical hurdles at major ports, leveraging localized supply chains to sustain the current momentum toward the 3.96 Billion valuation by 2033.
Competitive landscape and strategic dynamics
The market is characterized by high concentration, where players like Hitachi Automotive Systems Ltd. and Aisin Seiki Co. Ltd. leverage massive R&D budgets to dominate. Strategic dynamics focus on vertical integration—companies that control the production of both the piston head and ring components, such as Nippon Piston Ring Co. Ltd., possess a distinct competitive advantage in total engine solution provisioning compared to smaller, specialized aftermarket component manufacturers.
Executive summary of the Steel Piston Market
Our comprehensive analysis confirms the Steel Piston Market is poised for stable expansion, moving from 2.70 Billion in 2026 to 3.96 Billion by 2033. The convergence of thermal management innovation and the survival of the diesel segment in HCV applications are the primary catalysts. Strategic leadership from firms like Tenneco Inc. and Federal-Mogul Corporation underscores a move toward high-efficiency materials to navigate the tightening regulatory landscape.
Market forecast from 2027 to 2033
The Steel Piston Market is projected to experience a steady growth trajectory, reaching 3.96 Billion by 2033 at a CAGR of 5.61%. This forecast accounts for the projected dominance of HCVs in emerging economies, where high-durability steel pistons are essential. While gasoline-powered passenger cars face electrification pressures, the specialized demand for bowl and dome-shaped steel pistons in heavy-duty diesel engines will continue to anchor long-term revenue streams.
Segmentation analysis of product categories
Segmentation is essential to understanding the value flow:
- By Fuel: Focuses on Diesel versus Gasoline vs. Alternate fuels.
- By Shape: Includes Flat Top, Bowl, and Dome pistons for specific combustion characteristics.
- By Component: Highlights the Piston Head, Pin, and Ring sub-sectors.
Regional market analysis and geographic performance
The Asia-Pacific region remains the primary growth engine due to high HCV production volumes in China and India. Meanwhile, North America and Europe emphasize R&D, focusing on sophisticated thermal barrier coatings. Our data shows that regional performance is heavily tied to the presence of local automotive hubs, where giants like India Pistons Limited and Honda Foundry Co. Ltd. utilize proximity to assembly plants to reduce logistical overhead and time-to-market.
In-depth regional review of key markets
Europe maintains leadership in advanced material science, with Germany-based firms like Hirschvogel Umformtechnik GmbH pioneering high-strength forging techniques. Conversely, the Asia-Pacific theater, led by players like QuFu JinHuang Piston Co. Ltd., dominates in volume-based manufacturing. This regional bifurcation suggests that while Europe wins on technical sophistication, Asia-Pacific dictates the price-sensitive mass-market supply chain, creating distinct investment profiles based on geography and innovation capacity.
Company profiles and strategic positioning
Leading players exhibit distinct strategic focuses: Mahle GmbH leads through global innovation in engine systems, whereas Burgess-Norton Manufacturing Co. Inc. excels in the precision engineering of piston pins. These companies secure their market share by maintaining deep partnerships with tier-1 OEMs. Our analysis highlights that firms diversifying their portfolios into EV-compatible components while defending their core steel piston business are the best positioned to navigate the next decade.
Porter's Five Forces analysis
The Steel Piston Market faces high barriers to entry due to intense capital requirements for forging machinery. Supplier power remains moderate, with raw steel prices fluctuating globally. However, buyer power is significant, as major automotive OEMs dictate aggressive pricing. Competitive rivalry is fierce, forcing constant innovation in coating technologies to avoid commoditization, while the threat of substitution from advanced synthetics remains a long-term risk for combustion-centric engine components.
SWOT analysis of the industry
Strengths: Unmatched thermal durability in high-load scenarios. Weaknesses: High manufacturing cost compared to aluminum. Opportunities: Expansion into hydrogen-combustion engine development, which places extreme pressure on piston heads. Threats: Accelerated shift toward battery electric vehicle (BEV) adoption, which eliminates the need for pistons entirely. Successfully pivoting toward modular high-efficiency steel components is vital for maintaining industry relevance amidst these disruptive market forces.
Value chain analysis from raw materials to end-users
The value chain initiates with raw steel procurement and advanced alloy forging. Value is added during the precision machining of piston heads and the application of specialized coatings like dry film lubricants. Logistics involve shipping components to OEMs globally. Finally, these components reach end-users through assembly line integration in HCV or passenger vehicles, with aftermarket sales providing a critical secondary revenue stream for firms like Elgin Industries.
Investment insights and high-potential areas
Strategic investment should prioritize HCV-related segments and hydrogen-combustion R&D. Our research suggests that the forged piston head segment offers the highest margin potential, as these components are essential for the next generation of high-compression, cleaner-burning diesel engines. Investors should look for companies with established patent portfolios in thermal barrier coatings, as these technologies offer a defensible moat against low-cost, lower-quality manufacturing competitors entering the space.
Conclusion and key takeaways
The Steel Piston Market remains a robust, vital component of the automotive supply chain, evidenced by its growth to 3.96 Billion by 2033. While the transition to electrification is the primary long-term challenge, the current focus on high-efficiency combustion engines provides a secure, lucrative window for innovation. Players that focus on thermal management and material strength will continue to lead, provided they remain agile regarding evolving environmental regulations.
Research methodology for the report
Our estimates are triangulated using a multi-layered approach. We integrated proprietary trade registry data, primary interviews with 15+ industry executives from lead firms like Art Metal Mfg Co. Ltd., and secondary macroeconomic indicators. This method ensures that our projections of the 2.70 Billion market size and 5.61% CAGR reflect the real-world manufacturing outputs and supply chain constraints observed across North America, Europe, and Asia-Pacific markets.
Scope of the report coverage and limitations
This report covers the global Steel Piston Market, focusing on fuel types, piston shapes, and component-level materials. It encompasses segments from 2026 to 2033. Limitations include potential shifts in government-led decarbonization policies, which could alter the forecasted adoption rates of internal combustion engines. The analysis specifically excludes aluminum-only segments, focusing exclusively on steel-based engineering solutions for the commercial and passenger automotive sectors.
Recent developments in the Steel Piston Market
Recent strategic moves include partnerships between Ross Racing Pistons and specialized coating providers to enhance race-grade performance. Additionally, major players like Paramount Pistons and Diamond Pistons have announced shifts toward lightweight, high-strength forged steel designs to meet the demands of modern engine downsizing. These moves indicate a clear commitment to maintaining competitiveness by pushing the boundaries of material physics to improve engine performance and longevity.