Understanding the Cement And Concrete Products Market landscape
The Cement And Concrete Products Market serves as the foundational pillar for global infrastructure. Valued at 444.45 Billion in 2026, the sector encompasses the manufacturing of structural binders and precast elements. By integrating materials like Portland cement and specialty cement, industry stakeholders satisfy critical demand for residential and non-residential construction, operating as the essential nexus between raw mineral extraction and the built environment.
Structural Growth Drivers and Market Constraints
Market expansion is fueled by rapid urbanization and industrial infrastructure mandates. Key growth drivers include high-strength ready-mix concrete adoption and government infrastructure stimulus. However, the industry faces stiff constraints such as strict decarbonization regulations enforced by bodies like the EPA or EU Commission, and volatile logistics costs tied to clinker transport, which challenge margin stability across the 4.68% CAGR trajectory.
Emerging Innovation Patterns in Concrete Technology
Industry participants are pivoting toward sustainable construction solutions. Autoclaved Aerated Concrete (AAC) blocks and Self-Consolidating Concrete are trending due to their superior thermal efficiency and labor-saving properties. Our analysis indicates that companies like LafargeHolcim Ltd. and Cemex SAB de CV are increasingly prioritizing low-carbon binders to align with global environmental mandates, significantly altering the composition of standard product offerings.
Post-Pandemic Market Trajectory
The COVID-19 pandemic caused temporary supply chain disruptions in 2020-2021, yet the recovery trajectory has been robust and V-shaped. As construction projects resumed, pent-up demand for residential and infrastructure projects surged. The market has effectively absorbed these shocks, moving past previous output hurdles to stabilize a valuation of 444.45 Billion as of 2026, marking a resilient rebound.
Competitive Benchmarking and Market Dynamics
The Cement And Concrete Products Market is characterized by high concentration among global giants. Players like CRH plc, UltraTech Cement Limited, and China National Building Material Group Co.Ltd. exert significant influence through massive production scale. Strategic dynamics center on geographic diversification and vertical integration, where companies control everything from limestone quarries to the ready-mix delivery fleet to capture maximum value.
Executive Summary of the Market Outlook
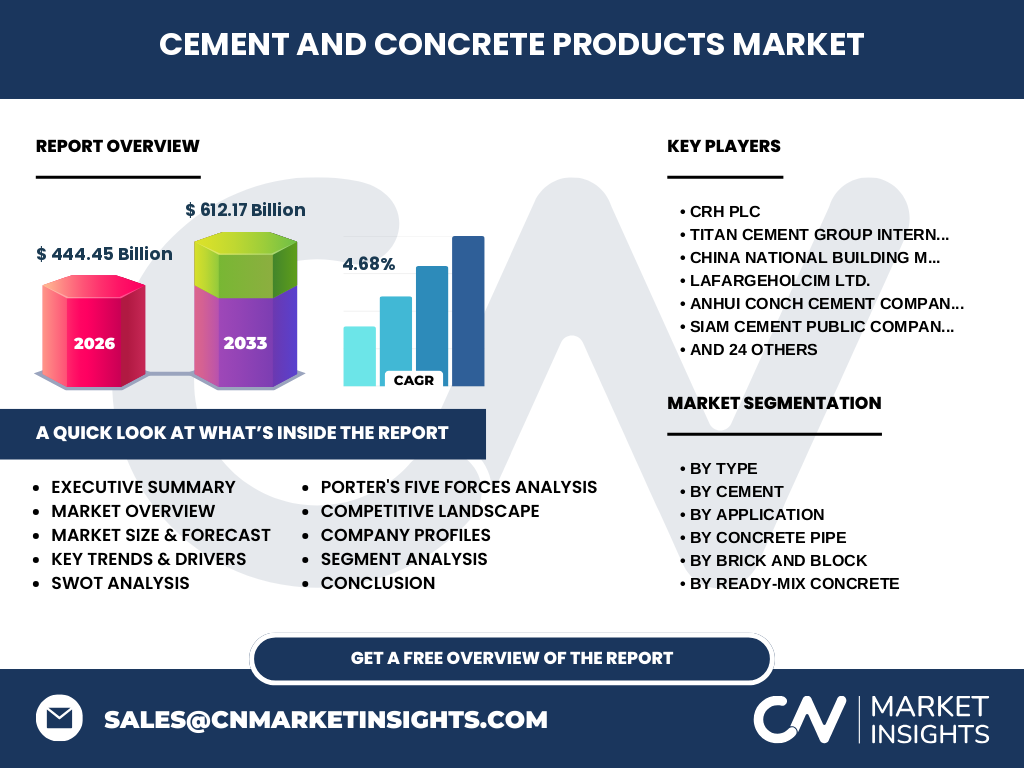
Our comprehensive analysis reveals a healthy forecast where the market will scale from 444.45 Billion in 2026 to 612.17 Billion by 2033. This consistent growth is driven by a 4.68% CAGR, underpinned by sustained investment in emerging markets and high-performance precast solutions. Investors should focus on companies aggressively transitioning their portfolios toward green cement technology and high-margin specialty products.
Projected Market Valuation and CAGR Forecast
Projections indicate a steady upward trend for the global market, reaching 612.17 Billion by 2033. This forecast reflects a CAGR of 4.68% through the 2027-2033 period. The data suggests that sustained industrialization and modernization of regional infrastructure will be the primary catalysts for hitting these targets, particularly in dense urban corridors requiring rapid-hardening cement solutions.
Segmentation Analysis of Concrete and Cement Products
The market is bifurcated into core segments including Cement, Ready-Mix Concrete, Concrete Pipe, Brick And Block, and other precast products. Each segment plays a vital role: Ready-Mix Concrete caters to high-speed commercial builds, while AAC Blocks serve the energy-efficient residential sector. Understanding these segments is critical for assessing how companies like Siam Cement Public Company Limited optimize their product mix to capture regional market share.
Regional Performance Distribution
The geographic distribution is led by Asia-Pacific, driven by massive urbanization in China and India. Europe and North America remain critical hubs for specialty and high-strength concrete innovations. Regional performance is heavily dictated by local building codes and the availability of raw materials like fly ash and blast furnace slag, which are essential for producing modern blended cement.
In-depth Examination of High-Growth Regions
Key regions such as the ASEAN corridor and South Asia are witnessing the fastest adoption of Precast Concrete Products. Conversely, established markets in the EU prioritize high-tech solutions like Hydrophobic Cement to improve building durability. Our regional review highlights that companies like Dangote Cement plc are strategically positioned to leverage rising industrial demand in high-growth, developing economies.
Strategic Positioning of Leading Industry Players
Major players maintain competitive advantages through massive logistical networks and specialized product portfolios. Heidelberg Cement AG leverages its global footprint, while Taiheiyo Cement Corporation focuses on regional technical leadership. Strategic positioning now involves deep integration into the digital construction ecosystem, ensuring that supply chains for essential materials like Portland Pozzolana Cement remain uninterrupted regardless of regional volatility.
Porter's Five Forces Analysis
The industry faces intense competitive rivalry and moderate threat of substitutes. Supplier power is high regarding limestone and energy costs, while buyer power remains strong due to the commoditized nature of standard cements. However, firms differentiate through proprietary chemical formulations, effectively reducing the impact of competitive pricing pressure by focusing on higher-margin specialty cement grades.
SWOT Analysis of the Cement and Concrete Sector
Strengths include robust demand and essential product necessity. Weaknesses involve high energy dependence and logistical bottlenecks. Opportunities lie in green manufacturing, specifically for White Cement and low-carbon blends. Threats include stringent carbon taxation and the slow adoption of circular economy models for recycling demolished concrete, which could impede future growth if regulatory hurdles are not navigated effectively.
Value Chain and Industry Structure
The value chain starts with raw material extraction (limestone, clay) followed by intensive kiln-based production. Value flows through distribution hubs to end-users in residential or infrastructure construction. Companies like Ambuja Cements Limited manage this chain by optimizing kiln efficiency, effectively translating raw material inputs into specialized Rapid Hardening Cement that meets the precise demands of large-scale, high-velocity infrastructure projects.
Strategic Investment Insights
High-potential areas exist in the transition to carbon-neutral manufacturing and the production of lightweight concrete solutions. Strategic recommendations include identifying regional markets where infrastructure deficits meet government subsidies. Investors should prioritize firms that are aggressively investing in R&D for specialty binders, as these provide a defensible market moat in an increasingly commoditized environment.
Conclusion and Strategic Takeaways
The Cement And Concrete Products Market is set for a strong trajectory toward 612.17 Billion by 2033. Success in this sector requires balancing large-scale operational efficiency with agility in adopting green manufacturing standards. Key takeaways emphasize that companies focusing on value-added products like self-consolidating concrete will outperform those remaining tethered to legacy, low-margin standard production models.
Methodology for Market Baseline Estimation
Our baseline estimates are triangulated via a proprietary research framework. We synthesize data from national trade registries, primary stakeholder interviews with site managers, and global macroeconomic indicators. By cross-referencing company-reported annual revenues with construction activity indices, we ensure our growth projections for the 444.45 Billion base year provide a highly accurate foundation for future forecasts.
Scope of the Market Report
This report covers global production, consumption, and trade dynamics of cement and concrete, excluding downstream decorative finishes outside the masonry segment. Coverage includes major manufacturers and regional market specifics from 2026 through 2033. It provides a detailed breakdown of segment-specific trends, focusing on core materials, while acknowledging that localized regulatory constraints in varying markets act as primary scope limitations.
Recent Market Developments and Strategic Shifts
Recent activity shows a shift toward strategic partnerships for carbon capture implementation and increased investments in automated masonry production. Announcements from leaders like JK Cement Ltd. and Buzzi Unicem SpA suggest that product launches are increasingly focusing on sustainable, low-heat cement variants. These moves illustrate the industry's proactive response to regulatory pressures and changing architectural preferences for durable, modern urban infrastructure.