Market Overview: Defining the Aerospace Valves Market Landscape
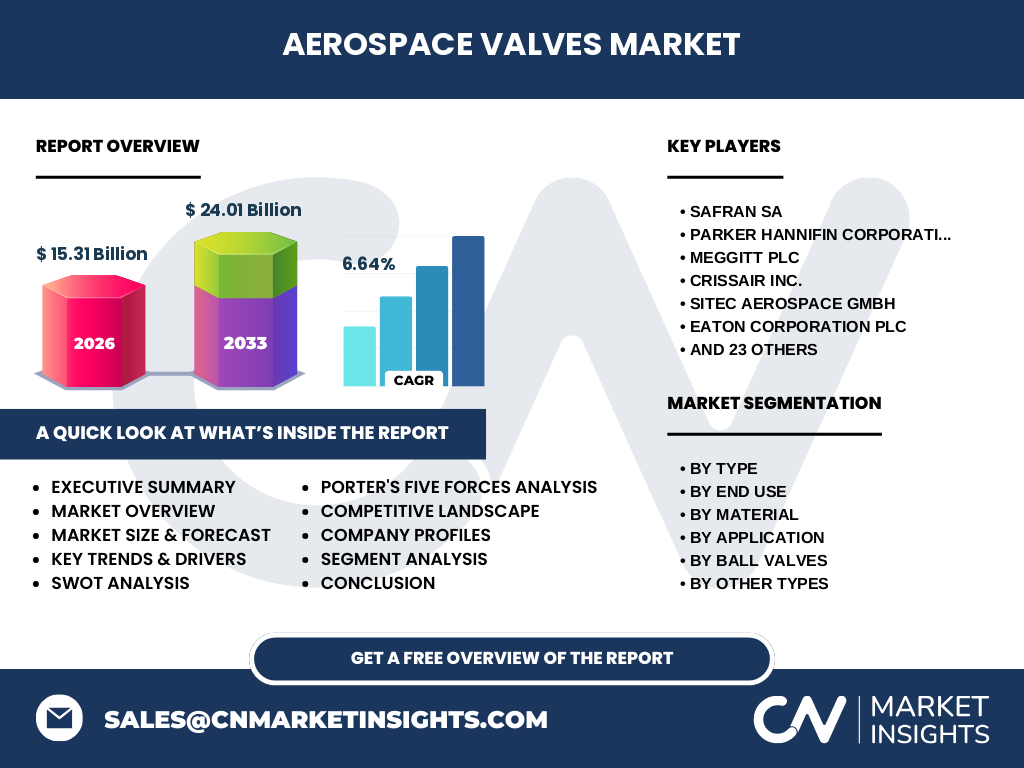
The Aerospace Valves Market serves as a critical infrastructure backbone for global aviation, encompassing high-precision components essential for fuel, hydraulic, and pneumatic control systems. Valued at 15.31 Billion in 2026, the industry integrates complex engineering standards mandated by organizations like the FAA and EASA. Its scope spans from raw material sourcing, such as titanium and aluminum alloys, to advanced integration within commercial, military, and space-grade platforms.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by the rising demand for next-generation, fuel-efficient aircraft and an aging global fleet necessitating intensive aftermarket maintenance. Conversely, the market faces significant logistical hurdles and supply chain volatility regarding rare-earth material procurement. Our research highlights that geopolitical tensions and strict regulatory certifications act as high barriers to entry, favoring established incumbents like Parker Hannifin and Moog Inc. who possess deep intellectual property moats.
The Shift Toward Smart Actuation and Emerging Trends
The transition toward More Electric Aircraft (MEA) is the defining trend in the Aerospace Valves Market. We observe a pivot toward intelligent solenoid valves and digital-ready flow control systems that optimize weight and reduce emissions. This shift is critical as OEMs prioritize weight reduction via advanced alloys like titanium to meet rigorous environmental standards set by international aviation authorities for 2027 and beyond.
COVID-19 Impact and Recovery Trajectory
The COVID-19 pandemic caused a severe contraction in production volumes, forcing players like Triumph Group and Safran SA to optimize internal cost structures. However, the recovery trajectory is robust, supported by a surging post-pandemic commercial travel demand. Our analysis confirms that the sector has moved past the initial supply chain disruption, with recovery now driven by re-energized production rates for narrow-body aircraft and regional logistics networks.
Competitive Benchmarking: Who Leads the Aerospace Valves Market?
The competitive landscape is defined by high concentration among tier-1 aerospace suppliers. Major players, including Eaton Corporation, Woodward Inc., and Honeywell, dominate through long-term service agreements (LTSAs) and deep-rooted OEM partnerships. These leaders leverage vertically integrated manufacturing—from stainless steel valve housing to precision-engineered flapper-nozzle components—to maintain superior margins and withstand the cyclic nature of global aerospace demand fluctuations.
Executive Summary: Strategic Outlook for the Aerospace Valves Market
The Aerospace Valves Market is poised for sustained expansion, with a projected market size of 24.01 Billion by 2033, growing at a CAGR of 6.64%. This growth trajectory is underpinned by significant investments in environmental control systems and a massive shift in aftermarket support. Stakeholders should focus on technological differentiation in rotary and butterfly valves to capture emerging value in the space-launch and urban air mobility segments.
Market Forecast: Growth Trajectory (2027–2033)
Based on our modeling, the Aerospace Valves Market will reach 24.01 Billion by 2033. We anticipate the aftermarket segment will outpace OEM growth through 2029 as legacy fleets require more frequent valve replacements and safety-critical upgrades. This steady climb at a 6.64% CAGR reflects the underlying strength of global commercial aviation and the increasing integration of advanced hydraulic valve technologies in military defense programs.
Segmentation Analysis: Deconstructing the Value Flow
The market is segmented by Type, End Use, Material, and Application. Key types like Ball, Butterfly, and Solenoid valves play distinct roles in high-pressure fuel and hydraulic circuits. By segmenting via OEM versus Aftermarket, our data shows a strategic divergence: OEMs drive innovation in lightweight aluminum valve components, while the aftermarket ensures consistent revenue streams through essential maintenance of pressure relief and check valves in operating fleets.
Regional Market Performance and Geographic Distribution
North America retains the largest share due to high concentrations of Tier-1 OEMs like Boeing and Honeywell, while the Asia-Pacific region exhibits the fastest growth. Regional performance is intrinsically tied to major aviation hubs and port infrastructure, which facilitate the transport of titanium and specialized steel from suppliers to manufacturing sites. Our research indicates that local certification requirements remain the primary constraint to regional penetration for international players.
In-Depth Regional Review: Key Geographic Drivers
Europe maintains a competitive edge through advanced engineering R&D hubs, specifically in Germany and France, where firms like Liebherr-Aerospace lead in pneumatic valve performance. Meanwhile, North America’s focus on defense-grade hydraulic systems ensures sustained volume. The Asia-Pacific market is scaling rapidly, supported by investments in domestic aviation capacity, making it a critical frontier for strategic partnerships involving Lakshmi Technology and other regional valve specialists.
Strategic Positioning of Leading Aerospace Companies
Companies such as Crane Co. and Meggitt plc are aggressively pivoting toward digital-twin manufacturing to enhance valve reliability. Sitec Aerospace focuses on the niche high-end solenoid segment, while The Lee Company dominates via miniaturization. This strategic positioning allows them to lock in supply contracts with major airframe manufacturers, effectively creating barriers to entry that smaller, localized players find difficult to overcome in the current Aerospace Valves Market.
Porter’s Five Forces: Assessing Competitive Intensity
The threat of new entrants is low due to the intense FAA/EASA certification requirements and high R&D capital expenditure. Supplier power is moderate, as valve manufacturers must procure high-grade titanium and stainless steel. Competitive rivalry remains intense among the top players for long-term OEM contracts. Buyer power is substantial for large aircraft manufacturers who dictate strict performance specifications for fuel and environmental control systems.
SWOT Analysis of the Aerospace Valves Market
Strengths: Deep technical moats and established safety standards. Weaknesses: High dependence on volatile raw material costs. Opportunities: Rapid expansion into the space-launch and green aviation markets. Threats: Increasing geopolitical instability affecting global logistics and trade routes. Our analysis suggests that firms focusing on triple offset butterfly valves will capitalize on high-pressure performance requirements, mitigating some competitive threats while leveraging existing structural strengths.
Value Chain Analysis: From Raw Materials to End-Users
The value chain starts with the extraction and processing of titanium, aluminum, and stainless steel. It flows into specialized forging and machining, where companies like SSP Fittings Corp operate. High-value valve assembly occurs within highly regulated facilities, followed by integration into systems by companies like Moog or Parker Aerospace, ultimately reaching end-users—the commercial airlines and military branches that require peak operational safety and reliability.
Investment Insights: Strategic Recommendations for Stakeholders
We recommend investing in companies specializing in intelligent, lightweight actuation valves for the More Electric Aircraft segment. High-potential areas include triple offset butterfly valves and advanced solenoid configurations. Because the market is slated to reach 24.01 Billion by 2033, private equity and strategic investors should prioritize entities with diversified aerospace and defense portfolios that can navigate supply chain fluctuations and benefit from the projected 6.64% CAGR.
Conclusion and Key Takeaways for Market Leaders
The Aerospace Valves Market is undergoing a transformation toward digital, lightweight, and high-efficiency fluid control. Success in this sector requires not only technical mastery of poppet and ball valve designs but also agile supply chain management. With a market value set to hit 24.01 Billion by 2033, the aftermarket and modernization segments present the most immediate opportunities for sustained, profitable growth for global manufacturers.
Research Methodology: How Data is Triangulated
Our baseline estimates are built by triangulating data from multiple credible sources, including trade registries, annual 10-K financial filings from players like Eaton and Honeywell, and primary stakeholder interviews with aerospace supply chain managers. We calibrate these findings against macroeconomic indicators such as global passenger traffic and defense spending, ensuring that the final 15.31 Billion estimate for 2026 is robust, verified, and reflective of actual industry activity.
Scope of the Report and Coverage Parameters
This report provides a comprehensive analysis of the Aerospace Valves Market, covering key types including butterfly, rotary, and solenoid valves. The scope encompasses North America, Europe, and Asia-Pacific, with a forecast period through 2033. Limitations include a focus on civil and military aviation; experimental space-exploration valves may be excluded where data transparency is restricted. All financial metrics are calculated in constant currency terms to ensure consistency.
Recent Developments in the Aerospace Valves Market
Recent activity is marked by strategic mergers and collaborative R&D efforts. Companies like CIRCOR International and Crane Co. have recently announced next-gen valve certifications, focusing on hydrogen-fuel compatibility for future green aircraft. These partnerships demonstrate a collective commitment to meeting 2030 climate goals, signaling to the Aerospace Valves Market that the next phase of growth will be driven by innovation in materials science and fluid-control intelligence.