An overview of the Metal Furniture Market and its strategic industry significance
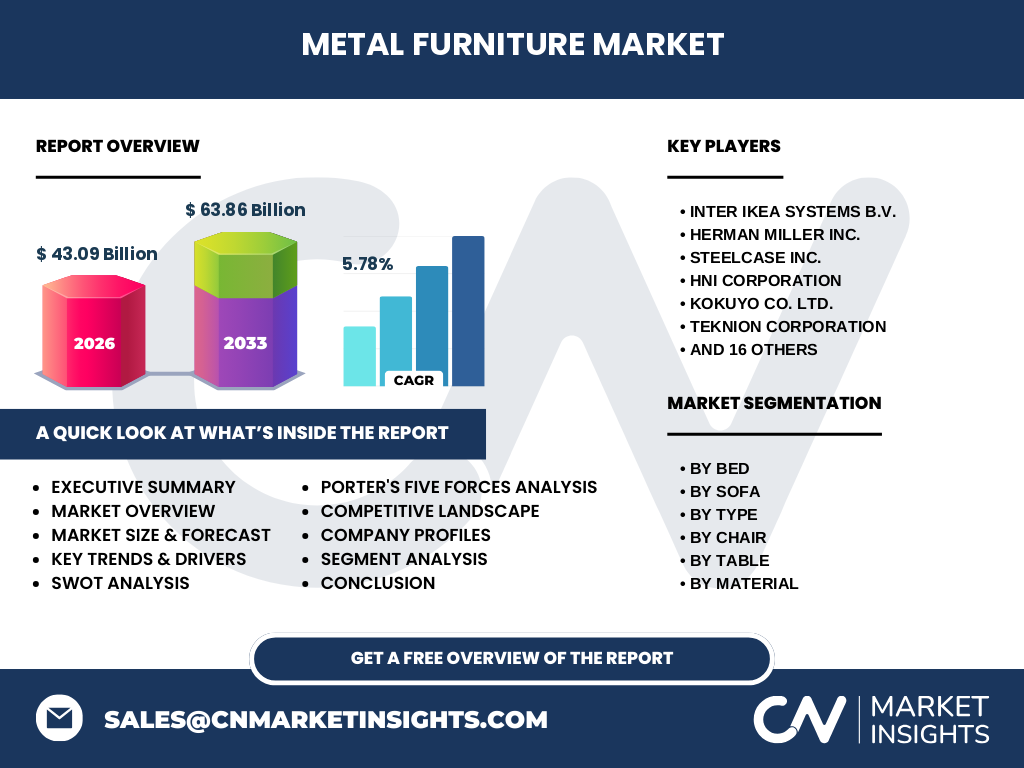
The Metal Furniture Market serves as a cornerstone of both residential and commercial infrastructure. With a valuation reaching 43.09 Billion in 2026, this sector encompasses durable goods ranging from ergonomic steel office chairs to high-end wrought iron outdoor sets. Its significance lies in the balance between material longevity and design scalability, providing essential solutions for space-efficient metal storage solutions and resilient commercial seating that withstands high-traffic environments.
Structural Growth Drivers, Restraints, and Market Opportunities
Growth is primarily fueled by the 5.78% CAGR driving the move toward sustainable, recyclable materials like aluminum. Conversely, supply chain volatility and fluctuating raw steel prices act as major market restraints. However, massive opportunities exist in the direct sales model, as institutional buyers increasingly bypass traditional middlemen to secure bulk procurement of metal shelving units and desks directly from manufacturers to optimize operational costs.
Emerging trends and long-term growth patterns in the sector
We observe a pivot toward modular industrial design, where metal furniture is no longer restricted to clinical settings but is increasingly featured in hybrid living spaces. Innovations in powder coating technology are enhancing corrosion resistance, while the rise of e-commerce channels is enabling boutique brands to compete with giants like Inter IKEA Systems B.V., democratizing access to high-design metal products globally.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe logistical bottlenecks at key maritime ports, initially stalling the Metal Furniture Market. However, the subsequent work-from-home boom accelerated demand for durable metal office chairs and cabinets. Our data indicates a robust recovery trajectory, as organizations transitioned to hybrid setups requiring heavy-duty, long-lasting furniture, effectively offsetting earlier losses and stabilizing the supply chain against post-pandemic demand spikes.
Competitive landscape: Strategic dynamics and market concentration
The market remains highly competitive with a mix of global titans like Steelcase Inc., HNI Corporation, and Godrej Interio. Concentration is elevated in the commercial segment, where firms compete on ergonomic innovation and global reach. Strategic dynamics are defined by vertical integration, with players like Ashley Furniture Industries Inc. leveraging economies of scale to dominate mass-market distribution channels while maintaining competitive pricing across diverse material segments.
Executive summary: Synthesis of the Metal Furniture Market outlook
The Metal Furniture Market is poised for significant expansion, with market size projected to climb from 43.09 Billion in 2026 to 63.86 Billion by 2033. This growth is underpinned by rapid urbanization and the increased demand for durable, aesthetic furniture in commercial offices and residential segments. Investors should note the shift toward high-margin customizable storage solutions and the efficiency gains inherent in modern global distribution networks.
Market forecast: Projected growth trajectory for 2027 to 2033
We project a steady upward climb for the industry, reaching 63.86 Billion by 2033 at a CAGR of 5.78%. This forecast accounts for the maturing of emerging economies where infrastructure investment drives commercial demand for metal tables and shelving. We anticipate that as manufacturing technologies improve, margins will expand, allowing for sustained growth despite potential macroeconomic headwinds in specific regional manufacturing hubs.
Segmentation analysis: Breaking down the categories
Market segmentation is vital for identifying high-growth pockets. The Bed segment (including bunk and folding options) targets high-density housing, while Chair categories cover everything from dining to executive office seating. Table types focus on dining and consoles, whereas Other Types—namely cabinets and shelving—capture the essential B2B institutional demand. These segments are supported by three core materials: Steel, Aluminum, and Wrought Iron, each catering to specific durability needs.
Regional performance and geographic distribution insights
Regional performance is fragmented; while North America leads in high-end office furniture demand from innovators like Teknion Corporation, the Asia-Pacific region experiences the fastest growth due to rapid urbanization. Regulatory compliance regarding fire safety and material toxicity in the EU creates distinct hurdles, whereas emerging markets rely heavily on distributor and dealer networks to navigate fragmented localized infrastructure and transport complexities.
In-depth regional review of key markets
In North America, the market is driven by commercial refurbishments and the adoption of ergonomic steel desks. In contrast, Europe prioritizes sustainable aluminum furniture, influenced by stringent environmental regulations. Meanwhile, the Asia-Pacific theater, anchored by companies like KOKUYO Co. Ltd., benefits from industrialization, seeing massive volume increases in metal storage solutions and bunk beds, reflecting the region's specific demographic shifts and housing density requirements.
Company profiles and strategic positioning
Market leaders utilize distinct strategic levers. Herman Miller Inc. and Haworth Inc. focus on premium design-led office environments, commanding higher price points through branding. Conversely, Nilkamal Limited and Zuari Furniture focus on volume and affordability, securing their position through deep direct sales and dealer penetration in high-growth territories. This spectrum ensures that companies effectively capture demand across both institutional procurement cycles and volatile consumer retail markets.
Porter's Five Forces analysis of the metal furniture sector
The Metal Furniture Market faces moderate threat from substitutes like wood or plastic, though the durability of steel remains a strong barrier. Bargaining power of buyers is high in the commercial sector due to volume, while supplier power is tied to raw metal commodity costs. Competitive rivalry is intense, compelling manufacturers to invest in supply chain optimization and exclusive e-commerce partnerships to maintain margins.
SWOT analysis of the global metal furniture industry
Strengths: Exceptional material durability and brand loyalty for players like Steelcase. Weaknesses: Sensitivity to steel/aluminum raw material price fluctuations. Opportunities: Rapid expansion into the commercial metal shelving space for modern e-commerce warehousing. Threats: Strict environmental regulatory bodies impacting manufacturing emissions. Leveraging these insights allows stakeholders to mitigate risks associated with raw material sourcing while capitalizing on the booming demand for heavy-duty, long-term furniture infrastructure.
Value chain analysis: From raw materials to the end-user
The value chain begins with raw metal processing (steel, aluminum) and proceeds to design and specialized fabrication. Value creation is highest at the manufacturing stage, where firms like Martin Brattrud Inc. apply proprietary coating techniques. Logistics and distribution channels follow, with direct-to-consumer e-commerce significantly shortening the chain, reducing costs, and increasing the speed of delivery to end-users who increasingly demand fast-ship metal furniture solutions.
Investment insights and high-potential areas
We identify B2B institutional furniture as the most lucrative investment area, particularly in markets shifting toward modernized commercial spaces. High-potential growth lies in companies adopting automation to manage rising labor costs and those successfully pivoting to direct sales platforms. Investors should prioritize firms that show resilience in raw material supply agreements, as this vertical control is critical to protecting margins during periods of metal market volatility.
Conclusion and key takeaways for stakeholders
The path to 63.86 Billion by 2033 is paved by the convergence of industrial durability and consumer-grade aesthetic design. Stakeholders should focus on the 5.78% CAGR as a baseline for growth, but look for outsized returns in the metal storage and shelving segment. Adaptability in distribution, specifically the integration of e-commerce and direct sales, remains the most effective strategy for capturing emerging market share.
Research methodology and data triangulation
Our estimates for the Metal Furniture Market are derived from a triangulated approach. We combine trade registry data from major ports to track volume, conduct primary stakeholder interviews with procurement managers at major firms like HNI Corporation, and cross-reference these with macroeconomic indicators. This method ensures that our financial projections account for both market demand signals and the localized supply constraints inherent in global metal fabrication.
Scope of the report: Coverage and parameters
This report covers the global Metal Furniture Market, specifically analyzing segments like beds, sofas, chairs, and tables made from steel, aluminum, and wrought iron. The scope includes geographic performance across all major continents and performance evaluation through 2033. Note that this analysis excludes non-metal furniture types to ensure a precise focus on the specialized metallurgy and fabrication standards required for high-quality metal furniture production.
Recent developments, partnerships, and product launches
Recent activity highlights a focus on sustainability and smart furniture. Partnerships between leading furniture brands and logistics technology innovators are revolutionizing the direct sales experience. Recent product launches from companies like Hillsdale Furniture LLC underscore a trend toward hybrid-use metal furniture, designed specifically to address the dual needs of residential home offices and small-scale commercial setups, reflecting the industry's agility in responding to shifting work-life paradigms.