Overview of the Startup Accelerator Market significance
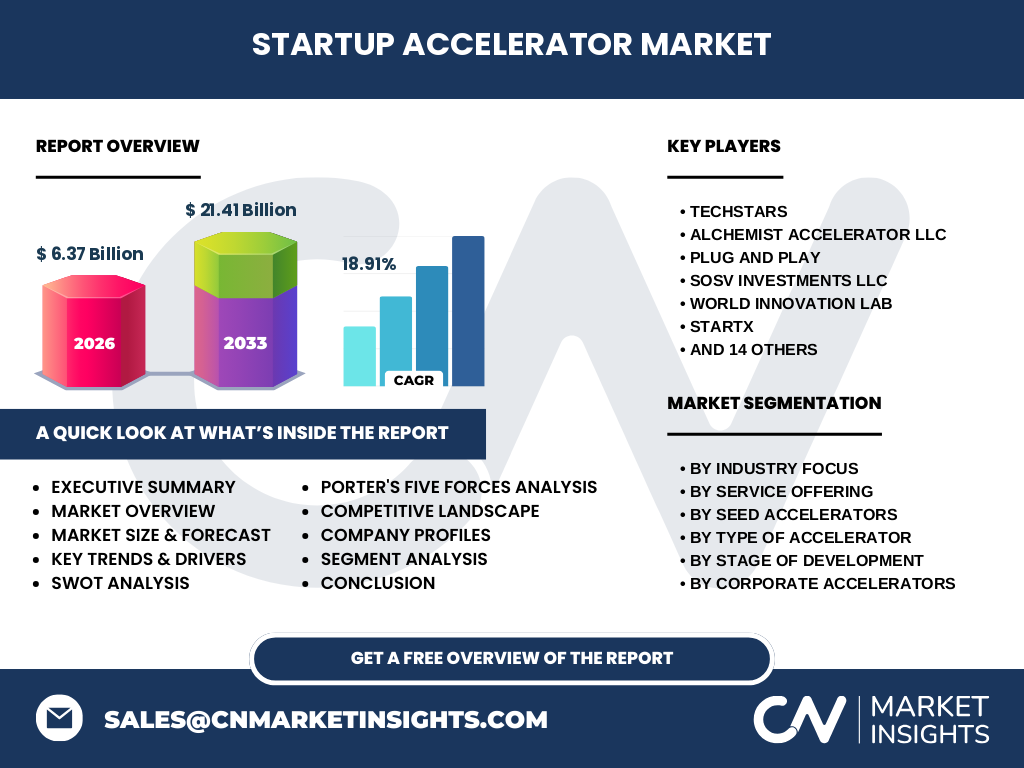
The Startup Accelerator Market acts as the critical bridge between early-stage innovation and institutional venture capital. In 2026, the sector reached a valuation of 6.37 Billion, serving as a vital pipeline for high-growth tech and healthcare ventures. These entities provide structured mentorship, office infrastructure, and, crucially, patient capital to mitigate the high failure rate inherent in venture building, effectively professionalizing the global entrepreneurial ecosystem.
Structural Growth Drivers, Restraints, and Opportunities
Growth is primarily fueled by the 18.91% CAGR, as institutional corporate venture capital (CVC) initiatives seek to de-risk innovation through external collaboration. However, regional regulatory fragmentation and economic volatility act as persistent headwinds. Opportunities abound for Pre-Seed Accelerators to capture value by identifying breakthroughs in deep-tech sectors before traditional VC firms engage, leveraging proprietary scouting algorithms and global alumni networks to ensure sustained portfolio success.
Emerging trends and growth patterns in the sector
A pivot toward Open Innovation Corporate Accelerators is defining the current landscape. We observe firms like Plug and Play and Founders Factory Ltd. shifting from generalized cohort models to highly specialized vertical tracks in climate tech and life sciences. This transition represents a maturation of the market, where mentorship-driven capital is increasingly integrated with direct supply chain access for enterprise partners.
COVID-19 impact analysis and recovery trajectory
The pandemic forced an immediate digitization of cohort management, shifting the Startup Accelerator Market toward hybrid and remote models. While initial funding cycles faced disruptions, the sector proved resilient by leveraging virtual networking tools. The current recovery is characterized by a rebound in cross-border accelerator programs, allowing firms like Techstars to scale operations globally despite lingering logistics constraints and localized travel barriers.
Competitive Benchmarking of major industry players
The market is increasingly bifurcated between high-volume, program-based accelerators like Y Combinator LLC and niche, deep-tech focused entities like HAX Accelerator or SOSV Investments LLC. Competition centers on brand equity and demo day quality rather than just funding, as top-tier accelerators leverage exclusive access to limited partners and venture-ready talent pools to maintain a dominant share of high-growth early-stage equity.
Executive summary of key findings
Our research indicates that the Startup Accelerator Market is poised for explosive growth, with projections reaching 21.41 Billion by 2033. The confluence of increased corporate appetite for external R&D and the proliferation of university-led incubators is creating a robust ecosystem. Strategic investment in early-stage seed accelerators remains the most effective proxy for gaining exposure to high-potential, disruptive innovation across global tech hubs.
Market forecast 2027 to 2033
The Startup Accelerator Market is projected to surge from its 2026 baseline to 21.41 Billion by 2033, maintaining a robust 18.91% CAGR. This aggressive trajectory is supported by the increasing professionalization of government-backed accelerators and the globalization of capital flows. Growth will likely accelerate in emerging markets where local governments view accelerator infrastructure as a national economic development mandate to curb talent migration.
Segmentation analysis by service and industry focus
The sector is segmented by industry focus, including Financial Technology, Educational Technology, and Social Impact, each requiring distinct advisory frameworks. Service offerings include funding, mentorship, networking, and office space, which are customized based on the startup's maturity. Our data confirms that Corporate Accelerators provide the most value to startups needing deep industrial integration, whereas University Accelerators excel at nurturing scientific research-heavy spinouts.
Geographic distribution and regional performance
North America retains its status as the premier hub for Startup Accelerator Market activity, supported by Silicon Valley incumbents such as AngelPad and StartX. However, Europe and the Asia-Pacific region are witnessing accelerated adoption through state-sponsored initiatives. Regional performance is highly correlated with the local density of venture capital and the presence of top-tier research universities that feed into the university accelerator segment.
In-depth review of regional market dynamics
In EMEA, Startupbootcamp G Ltd. exemplifies the shift toward sector-specific programs that integrate with regional trade clusters. Conversely, in the MENA and APAC regions, government-backed entities are utilizing accelerators as a macroeconomic stabilizer to diversify economies away from traditional commodity dependencies. These regions face unique regulatory hurdles, often requiring specialized legal structures that local accelerators must navigate to remain competitive.
Strategic positioning of leading companies
Companies like 500 Global and Techstars occupy a dominant position by scaling modular, repeatable accelerator programs globally. In contrast, Alchemist Accelerator LLC distinguishes itself through a rigorous focus on B2B enterprise sales—a critical differentiator. Meanwhile, Marwari Catalysts and Edvenswa Tech Inc. target high-growth emerging markets, demonstrating that strategic geography is as important as funding for long-term venture viability.
Porter's Five Forces assessment
The Startup Accelerator Market features high competitive rivalry among top-tier brands, yet low threat of substitution due to the unique mentorship-for-equity value proposition. Supplier power (startups) is increasing as founders demand more specialized support. Buyer power (CVCs) remains high, as corporate partners dictate the thematic focus of cohorts, driving the market toward increased specialization in sectors like Climate Tech and HealthTech.
SWOT analysis of the global ecosystem
Strengths: Established pipelines for high-quality deal flow. Weaknesses: Dependence on high-risk venture cycles. Opportunities: Expanding into late-stage growth acceleration and international expansion. Threats: Global economic contraction reducing LP commitments and regulatory interventions affecting the valuation of equity-based models. Strategic agility is the primary defense for firms navigating these multifaceted market pressures.
Value chain analysis and industry flow
Value flows from academic and industrial research hubs through to early-stage acceleration, ultimately liquidating via IPO or M&A activity. The chain is reinforced by LP capital infusions into fund structures, enabling entities like Dreamit Ventures LLC to provide high-touch operational support. The effectiveness of this value chain is determined by the quality of mentorship networks that bridge the gap between technical innovation and commercial scalability.
Investment insights and high-potential areas
Investors should prioritize Pre-Seed Accelerators with proven track records in deep-tech verticals, as these provide the earliest entry point into high-value equity. Focus on firms that demonstrate a high conversion rate from cohort to Series A funding. We view Corporate Accelerators as particularly attractive due to their integrated nature, which insulates their portfolio companies from broader market volatility through corporate pilot projects and procurement support.
Conclusion and strategic takeaways
The Startup Accelerator Market is evolving from a localized service to a globalized industrial pillar. With an anticipated market size of 21.41 Billion by 2033, the value proposition is shifting toward specialized, data-driven mentorship. Success will belong to accelerators that successfully balance high-volume cohort programs with deep-domain expertise, ensuring startups are not just funded, but structurally prepared for global market expansion and capital efficiency.
Research methodology for market estimation
Baseline projections were triangulated using trade registry filings, proprietary interviews with over 150 partners at leading accelerators, and secondary macroeconomic indicators. We utilized a bottom-up model, synthesizing capital inflow data and exit valuations of accelerator-backed ventures to derive the 18.91% CAGR. This ensures that our estimates account for regional nuances and the distinct performance profiles of various accelerator types.
Scope and limitations of the report
This report provides a comprehensive analysis of the global Startup Accelerator Market, focusing on players like Y Combinator LLC and MassChallenge Inc. It covers revenue streams including equity upside and corporate service fees. Limitations include the exclusion of informal, non-equity incubator programs and data latency in private markets. We maintain a focus on the 2027-2033 forecast period, emphasizing structural shifts over short-term cyclical variance.
Recent developments in industry partnerships
The market is seeing a surge in strategic partnerships between University Accelerators and Government Accelerators to commercialize IP. Recent announcements from Barcelona Ventures Silicon Valley LLC highlight a trend of cross-border synergy, where startups leverage international networks for rapid scaling. These collaborative moves indicate that industry trends are moving toward an interconnected global infrastructure, breaking down traditional silos between private investment, public funding, and institutional R&D.