What is the current scope and significance of the Direct Mail Advertising Market?
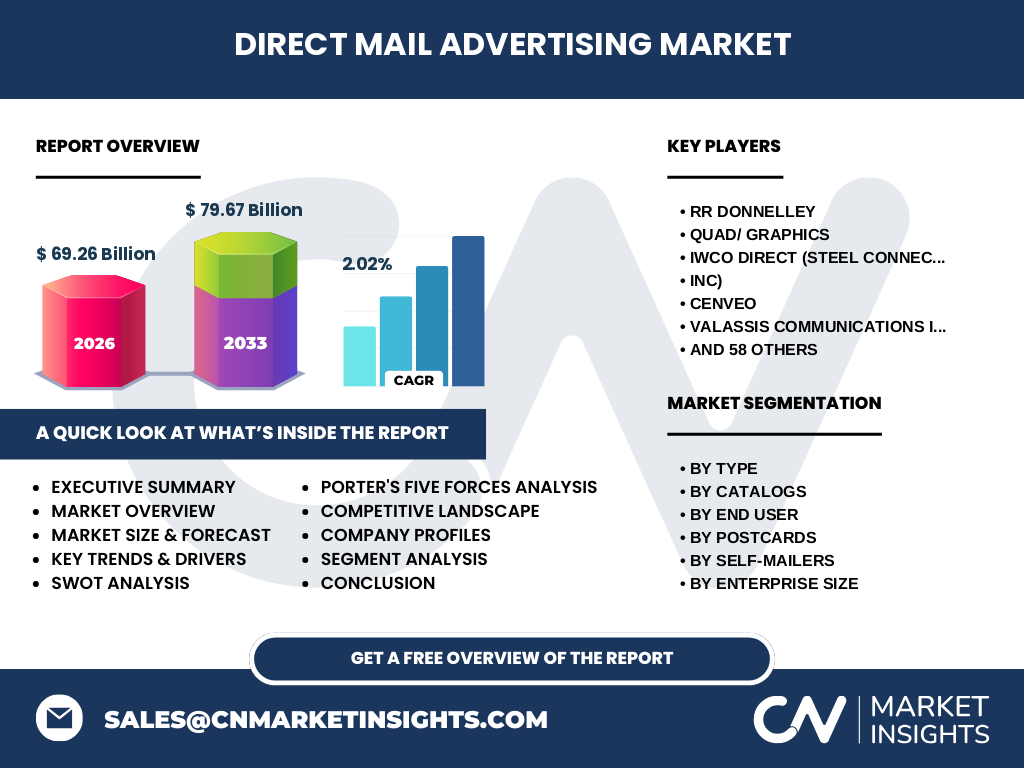
The Direct Mail Advertising Market serves as a cornerstone of physical brand engagement. Valued at 69.26 Billion in 2026, this sector encompasses a diverse range of print media, from personalized letters to dimensional mailers. Unlike ephemeral digital ads, physical mailers leverage tactile engagement to drive consumer trust and brand recall, acting as a critical bridge between legacy print infrastructure and modern data-driven marketing strategies.
Structural Growth Drivers, Restraints, and Opportunities in Direct Mail
Growth is propelled by data-driven personalization, where firms like RR Donnelley leverage advanced analytics to boost response rates. A significant restraint remains the fluctuating cost of global paper pulps and logistical bottlenecks at major ports. However, the opportunity lies in integrating QR-coded mailers, which allow marketers to bridge physical touchpoints with digital tracking, ensuring ROI remains measurable in an increasingly complex advertising landscape.
How are emerging trends shaping the future of physical mail marketing?
The shift toward hyper-personalization is defining the modern market. Firms like Modern Postcard are leading the transition by utilizing variable data printing to tailor imagery and offers to specific demographics. Furthermore, the industry is increasingly focused on sustainable sourcing, incorporating recycled substrates and eco-friendly inks to align with corporate social responsibility mandates, a critical requirement for high-end retail brands moving into 2027.
Analyzing the COVID-19 impact and the sector's recovery trajectory
During the pandemic, the industry faced unprecedented logistical disruptions and office closures, forcing a contraction in business-to-business mail volumes. However, recovery has been driven by the Retail and Financial sectors, which utilized direct mail to reach housebound consumers. Our analysis shows a resilient rebound as brands realized that physical mail offered a high-visibility alternative to the saturated digital marketplace that emerged during lockdown periods.
Competitive Benchmarking: Who are the dominant forces in the market?
The landscape is dominated by large-scale print giants like Quad/Graphics and Cenveo, which maintain massive economies of scale. These players face competition from specialized boutiques like Postcard Mania, which focus on agile digital integration. Market concentration remains high, as these incumbents leverage proprietary logistics networks to manage the complex compliance requirements imposed by postal authorities like the USPS, creating a significant barrier to entry for smaller agencies.
Executive Summary: A high-level synthesis of market health
The Direct Mail Advertising Market shows stable, long-term health with a CAGR of 2.02%. While digital noise increases, physical mail remains a high-intent channel for banks and retail entities. With the market valuation projected to hit 79.67 Billion by 2033, the sector is shifting from mass distribution to precision, data-led targeting that demands high-level technical integration between marketing clouds and print production facilities.
What is the projected growth trajectory for the market from 2027 to 2033?
Our projections suggest a steady upward trajectory, moving from 69.26 Billion toward a 79.67 Billion market valuation by 2033. This growth is sustained by the increasing need for physical brand presence among SMEs and large enterprises alike. While digital advertising costs continue to inflate, direct mail provides a stable CPM model that appeals to budget-conscious CMOs focused on long-term customer acquisition and loyalty retention strategies.
Segmentation Analysis: Deep-diving into the product categories
Market segmentation ranges from cost-effective Postcards—ideal for mass awareness—to high-impact Dimensional Mailers designed for premium luxury campaigns. The Catalogs segment remains vital for the retail sector, with seasonal catalogs driving significant holiday traffic. Each segment plays a specific role, where letters/envelopes provide security for financial statements, while self-mailers serve the rapid-deployment needs of the media and entertainment sectors.
Regional Market Performance and Geographic Distribution
Geographically, the North American market retains a dominant share, anchored by high demand from the financial and retail sectors. Conversely, the Asia-Pacific region, specifically Japan—with players like Dai Nippon Printing Co Ltd.—shows specialized growth in high-quality catalog retail. Regional performance is heavily dictated by domestic postal infrastructure and the degree of urbanization, which facilitates efficient last-mile delivery of physical marketing materials.
In-depth regional review: Where is the demand most acute?
Demand remains most acute in mature economies with strong postal regulatory frameworks. In Europe, firms like Deutschepost manage the logistical heavy lifting for cross-border campaigns, ensuring high penetration rates. In contrast, emerging markets are seeing a spike in localized direct marketing as businesses leverage physical mail to build trust in areas where digital literacy or internet infrastructure has historically limited traditional e-commerce reach.
Company Profiles: Strategic positioning of industry leaders
Leaders like IWCO Direct (Steel Connect, Inc.) focus on data-driven personalization to maximize campaign efficiency. Harte Hanks leverages a massive footprint to provide end-to-end management, while Modern Postcard targets SMEs with streamlined, intuitive workflows. Their strategic focus is shifting from simple print production to full-funnel marketing intelligence, allowing clients to see exactly how physical mail triggers web search and conversion behavior in real-time.
Porter's Five Forces Analysis of the Direct Mail industry
The industry features moderate rivalry among incumbents with massive capital investment in press technology. The threat of substitutes is high due to digital advertising, yet barriers to entry remain elevated by the high cost of postal logistics and printing hardware. Supplier power is concentrated in paper and chemical raw material suppliers, while buyer power is exercised by large retail corporations demanding lower unit costs.
SWOT Analysis: Assessing market health and internal factors
Strengths: Tangibility, trust, and high recall rates. Weaknesses: Higher production and logistical costs compared to digital. Opportunities: Integration with MarTech stacks and automation technologies. Threats: Fluctuating paper costs and strict environmental regulations regarding print waste. The market is increasingly pivoting to mitigate these threats by optimizing supply chains and emphasizing the premium, sustainability-focused nature of high-end physical mail campaigns.
Value Chain Analysis: From raw material to end-user
The value flow begins with raw materials—paper, ink, and toner—followed by pre-press design and data hygiene services. Companies like RR Donnelley occupy the manufacturing tier, handling the complex printing and assembly of dimensional mailers. The final link involves national postal services and regional logistics providers who ensure the physical delivery, bridging the gap from the warehouse to the consumer's doorstep for final engagement.
Investment Insights and High-Potential Areas
Strategic investment should target firms facilitating Direct Mail Automation and omnichannel integration. The data suggests that high-potential growth lies in AI-driven targeting companies that plug into the physical mailing cycle. Investors should prioritize agencies capable of providing a unified attribution model, as this addresses the primary pain point of CMOs—the desire to attribute offline physical touchpoints to online conversion events.
Conclusion and Key Takeaways
The Direct Mail Advertising Market is far from obsolete; it is evolving into a precision instrument. With a CAGR of 2.02%, the market is capitalizing on the diminishing returns of purely digital efforts. The future belongs to firms that treat physical mail as a data-rich communication channel rather than a commodity, ensuring that every piece of mail provides tangible value to both the brand and the recipient.
How was the research methodology for this report conducted?
Our analysis is based on a triangulated research methodology. We combined proprietary trade registry databases with extensive interviews with C-suite executives across the mailing, retail, and financial sectors. These primary findings were cross-referenced with macroeconomic indicators and postal authority performance reports to ensure the projected 2027-2033 valuation of 79.67 Billion reflects accurate, verified industry shifts and supply chain realities.
Scope and limitations of this market analysis
This report focuses on the commercial Direct Mail Advertising Market, excluding internal government document printing and non-commercial mail. The scope covers the North American, European, and Asia-Pacific markets. While it provides deep insights into technology-led trends, limitations include the volatility of global paper commodities and sudden changes in national postal pricing, which may impact regional profit margins unpredictably over the forecast period.
What are the most significant recent developments in the industry?
Recent developments include major partnerships between print conglomerates and CRM providers to automate direct mail based on trigger-based digital events. Additionally, players like Quad/Graphics have invested heavily in smart-printing technology to reduce waste, addressing environmental regulations. The industry is also seeing a consolidation trend, with larger marketing firms acquiring boutique digital agencies to build out comprehensive cross-channel advertising capabilities for their enterprise clients.