What is the scope and significance of the Mobile Point Of Sale Devices Market?
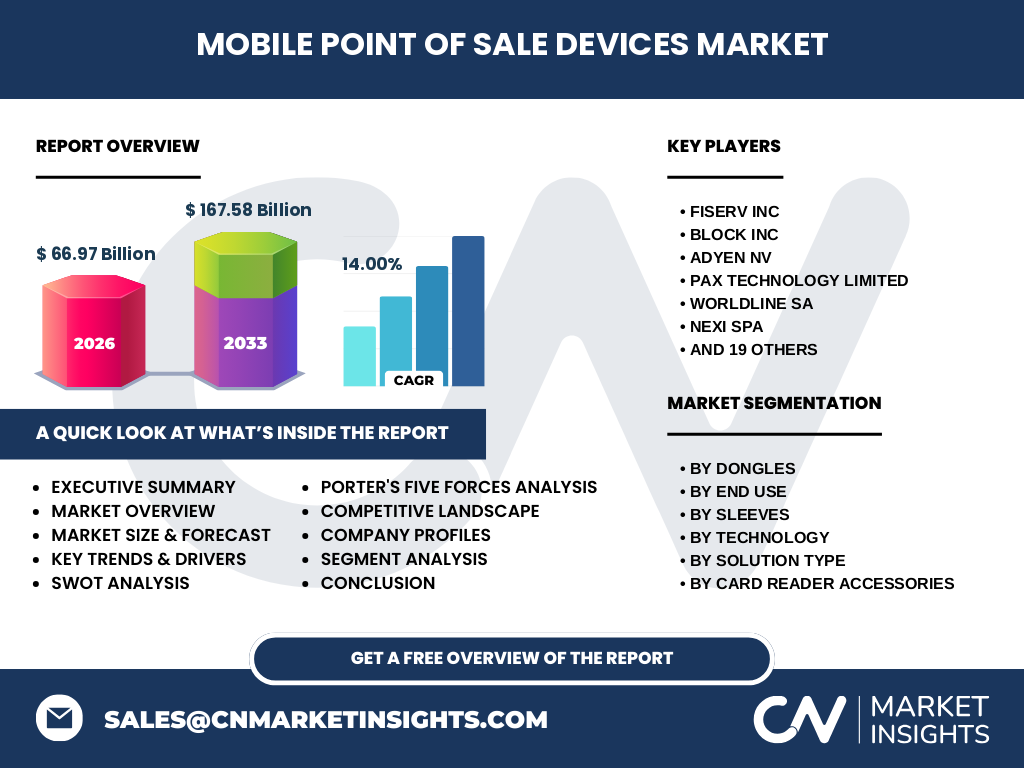
The Mobile Point Of Sale Devices Market serves as the critical connective tissue for modern commerce, enabling fluid transactions beyond static counters. Our analysis defines this market as the synthesis of hardware—dongles, sleeves, and integrated terminals—and the software ecosystems required for processing. Given the 66.97 Billion valuation in 2026, it represents a foundational infrastructure shift for global retail, hospitality, and healthcare sectors demanding real-time agility.
Structural Growth Drivers and Market Constraints
The market is propelled by a 14.00% CAGR, driven by democratized payment access for SMBs. Key drivers include the transition to EMV-compliant hardware and the proliferation of NFC-enabled contactless payments. Conversely, manufacturers face logistical hurdles regarding global supply chain volatility for semiconductors and complex PCI DSS compliance mandates, which act as a barrier to entry for smaller, regional hardware providers.
Emerging trends shaping the mobile POS landscape
A pivot toward integrated all-in-one mPOS devices is currently reshaping the industry. We observe a trend of convergence where biometrics and high-speed Bluetooth connectivity are becoming standard. Companies like Sunmi Technology Co Ltd and Zebra Technologies Corporation are leading this trend, prioritizing devices that combine robust physical durability with seamless cloud-sync capabilities to meet the high-throughput demands of modern retail warehouses.
How did the COVID-19 pandemic influence long-term market trajectories?
The pandemic served as a catalytic inflection point for the mobile point of sale devices market. The enforced necessity of contactless, socially-distanced payment experiences accelerated digital adoption by five years. Recovery has solidified into a permanent shift, with enterprises moving away from legacy hardware toward flexible, Bluetooth-enabled mobile terminals to manage consumer traffic more efficiently and maintain service continuity in volatile health environments.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a mix of pure-play payment innovators like Block Inc and SumUp Payments Limited, alongside legacy industrial giants like Toshiba Corporation and Panasonic Corporation. Market concentration is high in developed economies, while Pine Labs Private Limited and Paytm One97 Communications Ltd command significant strategic influence in rapidly digitizing emerging markets, focusing on vertical-specific solutions for retail and hospitality.
Executive Summary of the Mobile Point Of Sale Devices Market
Our research forecasts the market will reach 167.58 Billion by 2033. This growth underscores a massive shift in how businesses handle transactional data. By leveraging integrated card reader solutions and specialized protective sleeves with integrated card readers, firms are effectively bridging the gap between mobile digital wallets and physical storefronts, ensuring high-velocity throughput across diverse global retail ecosystems.
Market Projection and Growth Forecast (2027–2033)
We project the market will expand from its 2026 base to a valuation of 167.58 Billion by 2033. This represents a robust 14.00% CAGR. The growth trajectory is supported by the scaling of payment infrastructure in underserved regions and the constant refreshing of Chip-And-PIN and biometric-ready hardware necessitated by evolving security protocols and international anti-fraud regulations.
Segmentation Analysis by Solution Type and End-Use
We segment the market into Dongles (Audio Jack, USB, Bluetooth), Sleeves, and Integrated Solutions. These serve distinct operational needs, from portable micro-merchants utilizing dongles to high-traffic Restaurant Hospitality and Healthcare providers requiring all-in-one mPOS devices. This diversity ensures that the market addresses specific friction points, such as line-busting in retail or secure, portable bedside payments for clinical settings.
Geographic Performance and Regional Market Analysis
Regional performance is stratified by regulatory digital maturity. North America and Western Europe remain the largest markets by value due to high NFC adoption. However, APAC is the fastest-growing region, driven by Pine Labs Private Limited and Newland Digital Technology Co Ltd, who capitalize on localized mobile-first payment habits and the rapid transition from cash to digital-only ecosystems.
In-depth regional review: Where is the highest growth potential?
The highest incremental growth potential lies within emerging economies across Southeast Asia and Latin America. Regional constraints such as limited hardwired internet infrastructure make Bluetooth and Hybrid Technology Solutions essential. Local players are outperforming global incumbents by providing ruggedized hardware capable of withstanding harsh, humid climates, proving that localization of form factor is just as vital as software capability.
Strategic Positioning of Leading Market Players
Strategic positioning varies significantly: Stripe Inc and Adyen NV focus on the software-centric backend, while PAX Technology Limited and Castles Technology Co Ltd master the hardware engineering requirements. Companies like Toast Inc and Lightspeed Commerce Inc differentiate by embedding mPOS capabilities deep into specific industry-vertical POS platforms, creating an impenetrable ecosystem lock-in that enhances merchant retention.
Porter's Five Forces Analysis of the mPOS Sector
The threat of new entrants is moderate, mitigated by high certification requirements (e.g., PCI PTS). Supplier power remains focused on the rare earth mineral and chip manufacturers, while buyer power is high due to the commoditization of basic card readers. Competitive rivalry is intense, forcing manufacturers to compete on device connectivity and software integration rather than pure price-based commoditization.
SWOT Analysis: Internal Strengths and Market Threats
Strengths include rapid scalability and ease of deployment. Weaknesses involve high dependence on third-party payment gateways. Opportunities emerge from the integration of biometrics for enhanced security. Threats include cybersecurity breaches that could erode consumer trust and stringent data residency laws enforced by bodies like the GDPR in the EU, which complicate global hardware distribution strategies.
Value Chain Analysis from Raw Materials to End-Users
The value chain starts with the sourcing of silicon and battery components, flows through ODM manufacturers like Castles Technology, and passes to payment gateways and ISVs who overlay the software. The final leg reaches retailers and healthcare providers, who utilize these devices to streamline their customer checkout journey and ensure secure, compliant, and near-instantaneous financial reconciliation.
Investment Insights and Strategic Recommendations
We recommend focusing on integrated all-in-one mobile terminals as the primary growth vector. Investors should prioritize companies exhibiting strong cross-border regulatory compliance and those with hardware modularity. The most lucrative areas involve biometric authentication integration and devices capable of operating in offline-first environments, which offer a strategic edge in regions where connectivity remains unstable.
Conclusion and Key Takeaways for Market Stakeholders
The Mobile Point Of Sale Devices Market is a high-growth arena, forecasted to hit 167.58 Billion by 2033. Success relies on navigating the delicate balance between hardened security features and intuitive user design. Stakeholders must recognize that hardware is no longer a standalone commodity; it is a vital component of a connected digital service infrastructure that drives operational efficiency.
Research Methodology: How we triangulated market data
Our baseline estimates are derived from a triangulated framework. We synthesize global trade registry data, audit thousands of hours of primary stakeholder interviews with tier-1 POS providers, and cross-reference these with macroeconomic indicators. This method ensures our 14.00% CAGR calculation is not merely predictive but grounded in the actual shipment volumes and enterprise adoption patterns observed across major global shipping hubs.
Scope of the report: What is covered and what are the limitations?
This report covers the global Mobile Point Of Sale Devices Market, focusing on hardware segments: Dongles, Sleeves, and Integrated Solutions. Geographical scope includes North America, Europe, APAC, and RoW. Limitations include potential variance in cross-border regulatory shifts that might affect device certifications. Our analysis strictly centers on hardware and hardware-integrated software, excluding stand-alone mobile payment application services without hardware components.
Recent Developments and Market Announcements
Recent activity highlights a surge in partnership-driven growth, such as Fiserv Inc and NCR Voyix Corporation expanding their omnichannel payment capabilities. There is a marked uptick in product launches targeting biometric-integrated POS for enhanced fraud prevention. These developments indicate a broader move toward security-first hardware designs, aimed at meeting the sophisticated demands of retailers looking to lower their overall payment processing friction.