What is the scope and industry significance of the Container Fleet Market?
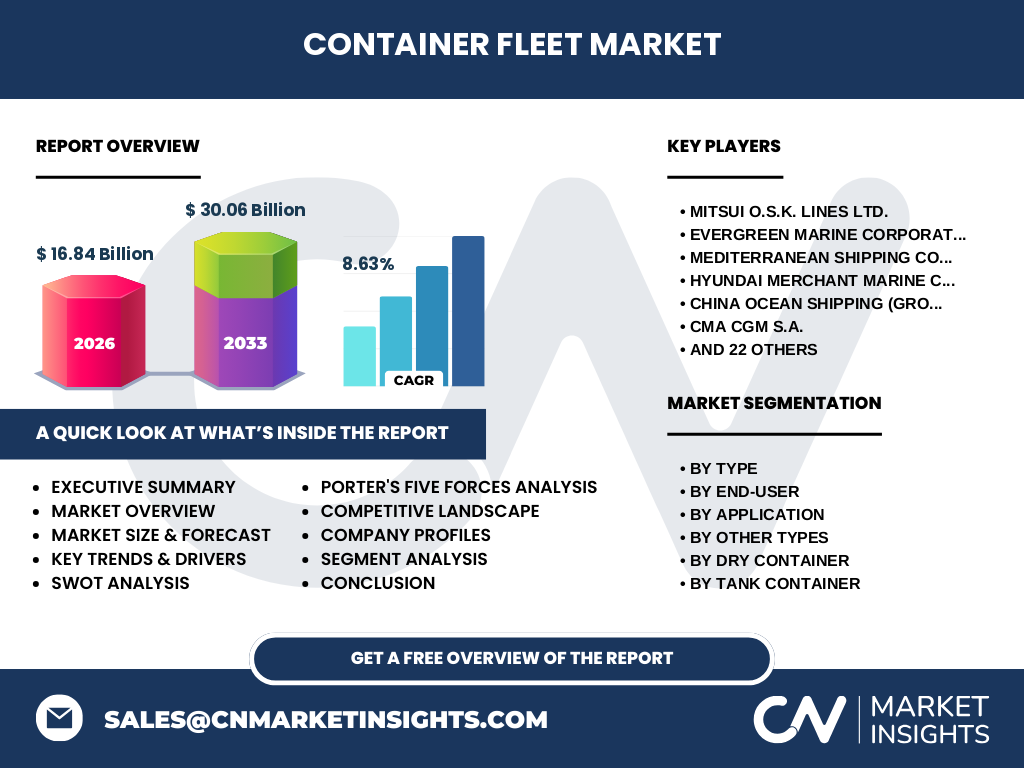
The Container Fleet Market represents the backbone of global trade, valued at 16.84 Billion in 2026. It encompasses the ownership, leasing, and operational management of standardized shipping units—ranging from Dry Containers to specialized Reefer and ISO Tank units. This infrastructure is critical for the seamless movement of cargo, serving as the essential interface between land-based logistics and maritime transport hubs worldwide.
Structural Growth Drivers and Market Constraints
Growth is propelled by a projected market expansion to 30.06 Billion by 2033, reflecting an 8.63% CAGR. Key drivers include the rise in global e-commerce and demand for cold-chain logistics. However, the industry faces severe headwinds from geopolitical trade tensions and escalating raw material costs for steel production, alongside stringent IMO environmental regulations that force costly fleet modernization to meet carbon emission reduction mandates.
Emerging Trends Shaping the Container Fleet Industry
The industry is pivoting toward smart containers integrated with IoT tracking, which enhance visibility in the Food and Agriculture segment. Furthermore, there is a clear shift toward sustainability-focused fleet management. Leading operators like A.P. Moller - Maersk A/S and CMA CGM S.A. are increasingly investing in green methanol-powered vessels and modular container designs to optimize logistics efficiency and reduce the carbon intensity of global shipping corridors.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic triggered unprecedented supply chain volatility, initially causing a massive shortage of empty containers. However, the subsequent post-pandemic recovery spurred aggressive fleet expansion as consumer demand spiked. Our analysis shows that companies that adopted digital-first asset management during this turbulent period were better positioned to capitalize on the 8.63% CAGR, successfully navigating the bottlenecks at major ports like Shanghai and Los Angeles.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is defined by high concentration among giants like Mediterranean Shipping Company S.A., COSCO, and Hapag-Lloyd. Strategic dynamics center on vertical integration, where carriers are acquiring logistics assets and terminal operations to control the entire supply chain. Meanwhile, pure-play lessors like Textainer Group Holdings Limited and Seaco Global Limited provide the flexible capacity essential for maintaining global fleet fluidity during peak shipping cycles.
Executive Summary: High-level Synthesis of Market Findings
The Container Fleet Market is on an aggressive upward trajectory, set to reach 30.06 Billion by 2033. Our research identifies technological adoption and infrastructure optimization as the primary value levers. Despite inflationary pressures on steel, the demand for High Cube and Reefer containers remains robust, driven by the critical requirements of the Automotive and Food and Agriculture sectors. The market rewards entities with high fleet agility and digital maturity.
Market Forecast 2027 to 2033
Between 2027 and 2033, we project the market will sustain an 8.63% CAGR, culminating in a valuation of 30.06 Billion. This expansion is supported by robust infrastructure development in emerging economies and the necessity for specialized tank containers in the surging Oil, Gas, and Chemicals sector. Strategic investment in pallet-wide and bulk container technology will be pivotal for operators looking to capture specialized trade volumes during this growth phase.
Segmentation Analysis: Driving Value Across Specialized Categories
Our analysis segments the market by Type, End-User, and Application. The Reefer Container segment is a high-value outlier, critical for pharmaceutical and food transport. Meanwhile, the ISO Tank segment is essential for the Oil, Gas, and Chemicals industry. By balancing Standard Dry Containers for general goods with Special Containers like Flat Racks for project cargo, players like Mitsui O.S.K. Lines diversify their revenue streams against cyclical industry downturns.
Regional Market Analysis and Geographic Performance
Geographically, the Asia-Pacific region dominates due to massive manufacturing hubs in China and Southeast Asia. North America and Europe remain high-consumption corridors, driving the demand for import-centric container distribution. Our data indicates that localized regulatory hurdles, such as strict European sustainability requirements, are forcing operators to optimize fleet performance differently across regions, favoring companies with regionally compliant and flexible asset portfolios.
In-depth Regional Review: Key Geographic Markets
The Asian market, led by China COSCO Shipping, focuses on volume-scale efficiency and high-traffic routes. Conversely, the European market is experiencing a shift toward sustainable intermodal logistics. In North America, firms like Matson Navigation Company Inc. leverage regional demand for High Cube containers to service e-commerce. Each region presents distinct logistical hurdles, requiring tailored fleet strategies to manage port congestion and inland distribution challenges effectively.
Company Profiles and Strategic Positioning
Leading firms like ZIM Integrated Shipping Services Ltd. and Yang Ming Marine Transport Corporation exhibit niche-market specialization, while giants like Evergreen Marine focus on massive fleet scaling. Companies such as Seaspan Corporation utilize long-term leasing models to provide stability in a volatile market. These entities are actively balancing their exposure to industrial transport versus consumer goods to hedge against fluctuating global trade cycles and regional demand shocks.
Porter's Five Forces Analysis: Competitive Forces Assessment
The Container Fleet Market exhibits high barriers to entry due to massive capital intensity. Supplier power is moderate, influenced by the steel and manufacturing sector, while buyer power is concentrated among global retail giants. The threat of substitutes is low, as sea transport remains the only viable bulk option. Rivalry is intense, driving innovation in smart technology and fuel-efficient fleet architecture to maintain competitive differentiation.
SWOT Analysis of the Global Container Fleet
Strengths include the ubiquity of standardized units. Weaknesses relate to high exposure to global economic cycles. Opportunities lie in the digital transformation of logistics and the surge in specialized tank container demand for the chemical sector. Threats involve volatile fuel prices and strict environmental compliance mandates from regulatory bodies like the International Maritime Organization, which challenge the profitability of older, less efficient vessel and container fleets.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with steel and polymer production, moving through specialized manufacturing facilities into the leasing and ownership phase. Asset managers then deploy these units to ocean carriers, which integrate them into global logistics networks. Finally, the value flows to end-users in Retails and Automotive sectors. Efficiency at each stage—from container production to final mile distribution—is critical for capturing margins in this 16.84 Billion market.
Investment Insights and Strategic Recommendations
Investors should prioritize companies with high Reefer and Tank container exposure, as these segments command higher margins and show resilient demand. Based on our market analysis, scaling in digital asset tracking is a non-negotiable strategic move. We recommend focusing on market participants like Textainer or Seaspan that demonstrate capital discipline and a clear roadmap for decarbonizing their fleet to meet upcoming 2033 industry sustainability benchmarks.
Conclusion and Key Takeaways
The Container Fleet Market is essential to global prosperity, projected to reach 30.06 Billion by 2033. Success in this sector requires balancing cost-efficient fleet expansion with technological innovation. As 8.63% CAGR suggests, the market is poised for significant growth, provided companies successfully navigate regulatory headwinds and optimize their multi-modal logistics chains to meet the evolving demands of global trade, particularly within the cold-chain and industrial transport segments.
Research Methodology: How we triangulated the data
Our methodology utilizes triangulation of primary and secondary data. We synthesized trade registry filings, annual reports from key players like Nippon Yusen Kabushiki Kaisha, and primary interviews with logistics stakeholders. Macroeconomic indicators from the World Bank and IMF were cross-referenced with fleet capacity data to model the growth trajectory. This multi-source approach ensures our 8.63% CAGR estimate remains grounded in verified industrial reality rather than speculative projections.
Scope of the Report: Coverage Parameters
This report covers the global Container Fleet Market from 2026 to 2033. The analysis spans all container types, including Dry, Reefer, Tank, and Special units, across major end-user industries. It focuses on commercial maritime logistics, excluding small-scale, domestic-only short-haul transport. Limitations include fluctuations in steel commodity prices and the unpredictable impact of geopolitical regional instability on global shipping volumes, which are accounted for through scenario-based modeling.
Recent Developments: Strategic Moves in the Market
Recent activity highlights a focus on alliances and M&A. Partnerships between major lines like Ocean Network Express and industry innovators are driving AI-enabled route optimization. Additionally, announcements regarding new-build orders for High Cube and eco-friendly refrigeration units signal a shift toward future-proofing assets. These strategic moves by Arkas Container Transport and others reflect a collective push to lower operational costs while meeting the urgent demand for carbon-efficient shipping.