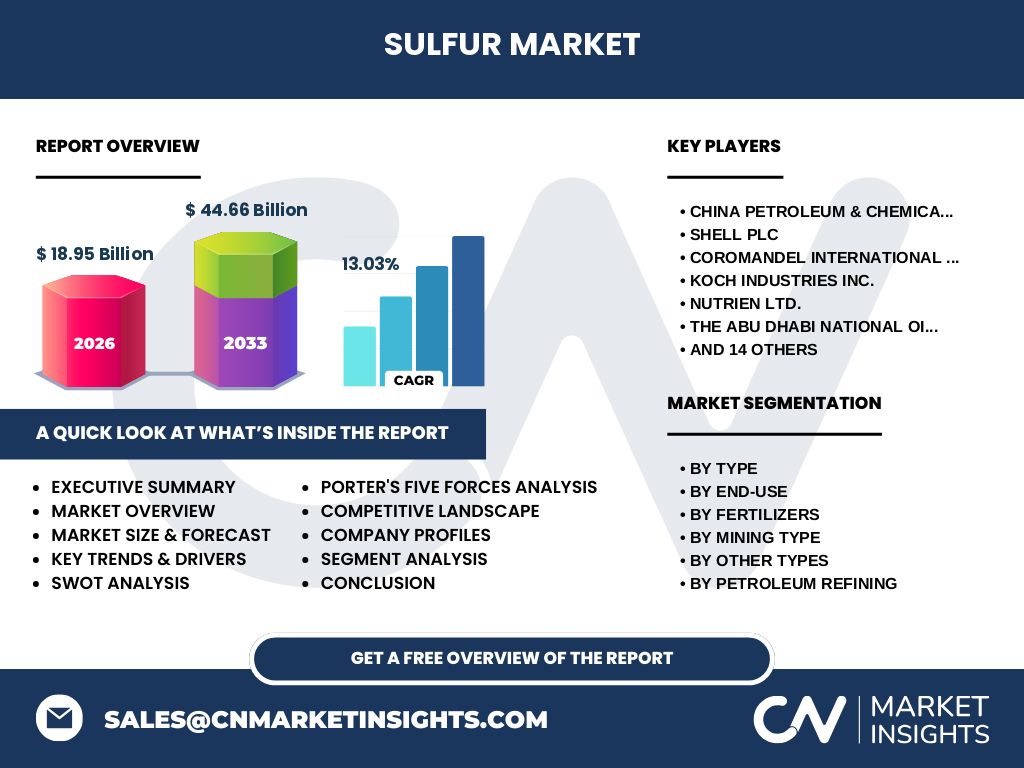
Overview of the global Sulfur Market
The Sulfur Market functions as a critical pillar for global industrial chemistry, centered on the production and consumption of sulfur derived largely from petroleum refining and natural gas sweetening. With a market size of 18.95 Billion in 2026, the sector is indispensable for producing sulfuric acid, the lifeblood of the fertilizer, chemical processing, and metal manufacturing industries, positioning sulfur as an essential commodity for global economic productivity.
Structural Growth Drivers and Market Constraints
Primary growth is driven by the agricultural sector's relentless demand for ammonium sulfate and potassium sulfate fertilizers. However, the market faces logistical hurdles, including strict IMO shipping regulations regarding sulfur content in marine fuels. Despite these constraints, the shift toward sustainable sulfur recovery units (SRU) in refineries creates significant opportunities for players like Shell plc and ADNOC to monetize byproduct streams.
Emerging trends and long-term trajectory
A pivot toward specialized sulfur compounds, such as those used in advanced rubber vulcanization and pharmaceutical synthesis, is reshaping industry portfolios. Our analysis identifies a move toward circular economy initiatives where Sulfur-Metal Manufacturing processes, particularly in copper and zinc extraction, increasingly prioritize closed-loop systems to minimize environmental impact and recover sulfur value from slag.
Post-COVID-19 market recovery and resilience
The pandemic initially disrupted supply chains at major ports like Shanghai and Rotterdam, causing volatility in sulfuric acid pricing. Recovery has been robust, fueled by the aggressive rebound in industrial manufacturing and food security mandates. The industry demonstrated remarkable resilience by integrating digital logistics, allowing companies like Nutrien Ltd. and The Mosaic Company to maintain throughput despite early lockdowns.
Competitive Benchmarking and Market Concentration
The Sulfur Market is characterized by high concentration, dominated by state-backed giants like China Petroleum & Chemical Corporation and ADNOC alongside private powerhouses like Koch Industries Inc. Competition centers on logistical efficiency and vertical integration. Players like Yara International ASA secure their competitive edge by hedging raw material availability, effectively insulating themselves against the cyclical nature of global commodity markets.
Executive Summary of Sulfur Market Outlook
Our research confirms the Sulfur Market is poised for exponential growth, projected to reach 44.66 Billion by 2033 from a 2026 base of 18.95 Billion. This represents a significant CAGR of 13.03%. This trajectory reflects the heavy reliance of emerging economies on sulfur-intensive chemical processing and the ongoing necessity for high-yield agricultural fertilizers to support a growing global population.
Market Forecast: 2027 to 2033
The forecast period reflects an aggressive compound annual growth rate of 13.03%. We anticipate the valuation will climb to 44.66 Billion by 2033. This growth is underpinned by sustained capital expenditure in hydrodesulfurization technologies at refineries and the expansion of downstream sulfur-based specialty chemical capacity in the Asia-Pacific region, which remains the most aggressive growth engine for the industry.
Strategic Segmentation Analysis
Market segmentation spans critical verticals. Fertilizers remain the dominant category, including Ammonium Sulfate and Sulfur Coated Urea. Meanwhile, the Petroleum Refining segment, encompassing Sulfur Recovery Units, acts as both a supply source and a consumption hub. Chemical Processing and Sulfur-Metal Manufacturing (specifically zinc and copper refining) provide the necessary high-margin diversification that stabilizes revenues against pure commodity price swings.
Geographic Performance and Regional Dynamics
Geographically, the Middle East and North America dominate supply due to massive refining capacities, while Asia-Pacific serves as the primary consumption epicenter. Regional performance is highly correlated with domestic agricultural intensity and infrastructure investment. Israel Chemicals Ltd. and Haifa Group have optimized their regional footprints to capture high demand in arid markets requiring sophisticated sulfur-based fertigation solutions.
Detailed Regional Review: North America and Asia-Pacific
In North America, demand is heavily tied to the Midwest agricultural sector and refined fuel requirements. In contrast, Asia-Pacific is witnessing rapid scaling of Sulfur-Metal Manufacturing. Companies like China National Chemical Corporation are strategically prioritizing local sulfur supply chains to mitigate dependence on volatile seaborne imports, marking a shift toward regional autarky in sulfuric acid production capacities.
Strategic Positioning of Key Companies
Major players employ distinct strategies: BASF SE focuses on high-value sulfur compounds for the pharmaceutical industry, while Coromandel International Ltd. leverages its stronghold in Indian fertilizer markets. Freeport Sulfur Company and Texas Gulf Sulfur Company remain essential to the upstream supply chain, whereas Ecospec Noveltech Pte. Ltd is pioneering innovative sulfur scrubbing technologies that address the growing pressure for cleaner refinery emissions.
Porter’s Five Forces Analysis
The threat of new entrants is low due to the massive capital required for refinery sulfur recovery integration. Supplier power is high among major oil and gas producers. Competitive rivalry is intense, driven by price transparency in global trade. Bargaining power of buyers in the fertilizer sector is moderate, limited by the essential nature of sulfur nutrients for crop yields.
SWOT Analysis: Strengths, Weaknesses, Opportunities, and Threats
Strengths: Indispensable raw material status. Weaknesses: High dependence on oil and gas industry cycles. Opportunities: Increasing adoption of Sulfur Coated Urea for controlled-release fertilizers. Threats: Rapidly evolving environmental regulations by agencies like the EPA or EU ECHA, which may necessitate expensive process upgrades for sulfuric acid production facilities, potentially impacting margins for smaller tier-two manufacturers.
Value Chain and Industry Flow
The value chain begins with desulfurization in petroleum refineries, transforming hazardous hydrogen sulfide into marketable sulfur. This raw material flows to sulfuric acid plants and fertilizer producers like Nutrien Ltd., ultimately reaching end-users in agriculture, pharmaceuticals, and rubber production. This interconnected flow highlights how logistical hubs and port infrastructure act as the connective tissue for global price stability.
Investment Insights and Strategic Recommendations
We recommend investors prioritize companies integrating Sulfur Recovery Unit (SRU) optimization and those expanding in specialty sulfur-metal alloys. High-potential areas include bio-based sulfur compounds and advanced nutrient coatings. The data suggests that firms aligning with ESG-compliant supply chains—like those utilizing recycled sulfur from mining slag—will outperform, as carbon-neutral mandates become standard for upstream heavy industrial players globally.
Key Takeaways and Conclusion
The Sulfur Market is undergoing a transformative growth phase, projected to reach 44.66 Billion by 2033. Success for stakeholders requires balancing traditional commodity trading with investments in value-added downstream chemistry. Agricultural security and industrial modernization remain the dual engines propelling this sector, ensuring that sulfur remains a vital element of the global economic infrastructure throughout the coming decade.
Methodology for Market Estimation
Our estimates are triangulated using a rigorous, multi-layered approach. We aggregate trade registry data and customs filings, calibrate them against primary stakeholder interviews with industry CEOs, and cross-reference these with macroeconomic indicators from the World Bank and sector-specific bodies. This ensures that our CAGR of 13.03% accurately reflects real-world market dynamics, balancing raw production figures with precise regional consumption estimates.
Scope of the report
This report covers the global Sulfur Market, including fertilizers, chemical processing, sulfur-metal manufacturing, and petroleum refining. The scope excludes small-scale artisanal mining but comprehensively evaluates industrial-scale production. Regional coverage spans North America, Europe, Asia-Pacific, and LAMEA, providing granular analysis of the market segments and the companies influencing the landscape from 2026 to 2033.
Recent Market Developments
Recent activity highlights a focus on technological partnerships. For instance, recent alliances between Treibacher Industrie AG and specialized metal refineries demonstrate a commitment to high-purity sulfur output. Furthermore, industry-wide initiatives to enhance Sulfur Coated Urea production reflect a broader trend of leveraging smart-fertilizer technology to meet climate targets while simultaneously improving agricultural throughput for major producers like The Mosaic Company and K+S Aktiengesellschaft.