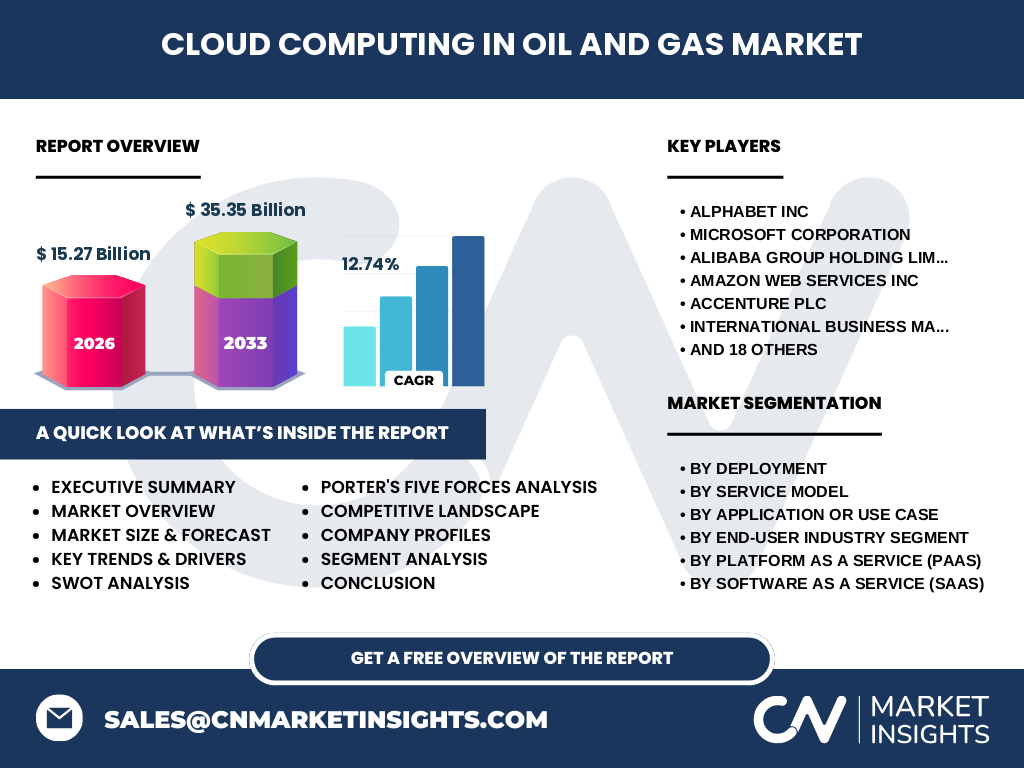
Overview of the Cloud Computing In Oil And Gas Market
The Cloud Computing In Oil And Gas Market serves as the digital backbone for global energy operations, transitioning legacy infrastructure into agile, cloud-native environments. Valued at 15.27 Billion in 2026, this sector focuses on integrating upstream exploration data with downstream refining workflows. By leveraging scalable architectures, operators achieve operational transparency, ensuring compliance with strict regulatory frameworks like the OSHA and EPA mandates regarding emissions monitoring and safety.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by the urgent need for predictive maintenance and real-time reservoir simulation to maximize ROI. However, firms face significant challenges, including strict data sovereignty laws and the logistical complexity of integrating legacy SCADA systems. Despite these hurdles, the industry is pivoting toward Hybrid Cloud deployments, balancing security with the computational power required for massive seismic data processing projects across major basins.
Emerging Trends and Strategic Growth Patterns
We observe a distinct shift toward AI-driven digital twins, where companies like Dassault Systèmes SE and Aspen Technology Inc lead in simulating complex refinery throughput. These trends emphasize edge computing for remote oilfield operations, minimizing latency in mission-critical data transmission. Organizations are increasingly prioritizing SaaS-based Enterprise Resource Planning to harmonize disparate supply chain nodes across international maritime shipping routes.
COVID-19 Impact and Recovery Trajectory
The pandemic acted as a catalyst for digital transformation, forcing firms to accelerate cloud migration to support remote workforce collaboration during price volatility. Initially challenged by disrupted supply chains, the market rebounded as operators realized that cloud-based asset management systems offered the resilience needed for survival. Recovery is now characterized by sustained investment in IaaS to ensure continuous uptime for global production assets.
Competitive Benchmarking and Market Dynamics
The landscape is dominated by heavyweights including Microsoft Corporation, Amazon Web Services Inc, and Alphabet Inc, providing the hyperscale infrastructure necessary for massive data analytics. Conversely, niche players like Quorum Software LLC and PetroDE LLC dominate through specialized upstream simulation software. Concentration remains high, with Accenture plc and Capgemini SE orchestrating complex system integration projects for supermajors, balancing cloud adoption with legacy technology optimization.
Executive Summary of the Cloud Computing In Oil And Gas Market
Our analysis projects the Cloud Computing In Oil And Gas Market to reach 35.35 Billion by 2033, growing at a CAGR of 12.74%. The sector's transition is non-negotiable for competitiveness in an era of energy transition. Success hinges on a strategic mix of Hybrid Cloud adoption, robust data security frameworks, and the integration of analytics platforms that optimize production flow from wellhead to pipeline.
Market Forecast Analysis (2027-2033)
Following the 2026 valuation of 15.27 Billion, the market is set to experience aggressive expansion through 2033, reaching 35.35 Billion. This 12.74% CAGR reflects the commoditization of compute resources and storage solutions. As volatility persists in global oil prices, upstream producers will rely increasingly on cloud-based predictive analytics to lower lifting costs and extend the economic life of aging, mature assets.
Segmentation Analysis: Deployment, Service, and Application
The market is segmented by Deployment (Public, Private, Hybrid), Service Model (IaaS, PaaS, SaaS), and Use Case. While Infrastructure as a Service handles storage and networking, Platform as a Service is increasingly critical for developers creating custom reservoir modeling tools. These segments empower upstream firms to manage vast geological datasets, while Supply Chain Management applications streamline the movement of materials through critical regional ports and transport networks.
Regional Market Analysis and Geographic Distribution
North America remains a dominant revenue engine due to the concentration of shale extraction technologies and high cloud literacy. However, the Middle East and Africa are rapidly emerging as high-growth regions, driven by massive digital modernization initiatives by national oil companies. Meanwhile, the Asia-Pacific region presents unique opportunities in downstream refining optimization, supported by substantial regional investments in downstream infrastructure and local technological hubs.
In-depth Regional Review: North America vs. Middle East
North America utilizes cloud platforms primarily for shale analytics and high-frequency production monitoring. In contrast, the Middle East is scaling Private and Hybrid Cloud architectures to modernize national infrastructure, emphasizing Data Storage and Management for massive, multi-decade extraction projects. Both regions demonstrate that localized regulatory compliance and data residency requirements remain the primary design constraints for global cloud service providers operating within these critical energy theaters.
Company Profiles and Strategic Positioning
Market leaders utilize specific strategic moats: SAP SE and Oracle Corporation excel in ERP and back-office integration, while Infosys Limited and Cognizant Technology Solutions Corporation provide the agile implementation services required for complex legacy migrations. Bentley Systems Inc occupies a specialized space in infrastructure modeling, directly supporting the technical engineering requirements of midstream operators managing extensive pipeline networks across complex, environmentally sensitive terrains.
Porter's Five Forces Analysis
The threat of new entrants is moderate, hampered by the high cost of cloud architecture and specialized energy-sector expertise. Buyer power is significant, as supermajors command large-scale, long-term contracts. Competitive rivalry is intense among cloud hyperscalers like Microsoft and Amazon, while supplier power is concentrated in proprietary software suites that firms are reluctant to swap, ensuring sticky SaaS and PaaS revenue streams for providers like Infor Inc.
SWOT Analysis: Cloud Computing In Oil And Gas Market
Strengths: Massive computational scalability and real-time data access. Weaknesses: High dependence on stable high-speed connectivity in remote fields. Opportunities: Integration of IoT sensors and machine learning for Predictive Maintenance. Threats: Increasing sophisticated cyber-attacks on critical energy infrastructure targeting sensitive reservoir data or pipeline control systems. Firms that proactively manage these threats through robust Security and Compliance Services gain a decisive competitive advantage in global energy markets.
Value Chain Analysis of the Industry
The value flow initiates with upstream raw material extraction, where cloud services provide the compute resources to process seismic data. It moves through midstream transportation and downstream refining. Players like Workday Inc and Sage Group plc facilitate the enterprise back-end, while TIBCO Software Inc ensures seamless middleware integration. This value chain is increasingly digital, as data-driven decisions now influence every stage of the energy commodity lifecycle.
Investment Insights and High-Potential Areas
Investors should target companies providing Vertical-Specific SaaS solutions that bridge the gap between IT and OT (Operational Technology). The highest potential lies in Disaster Recovery and Backup services, as firms face mounting pressure to protect critical assets from cyber-warfare. Furthermore, investments in Analytics and Monitoring Platforms are poised for rapid growth, as oilfield service providers look to increase operational efficiency in response to global environmental and sustainability mandates.
Conclusion and Key Takeaways
The transition to the cloud is no longer optional; it is the primary driver of operational efficiency in the oil and gas sector. With a projected market value of 35.35 Billion by 2033, organizations must prioritize Hybrid Cloud strategies that balance internal control with hyperscale agility. Companies that effectively leverage predictive modeling and automated supply chain tools will inevitably capture the lion's share of market value over the next decade.
Research Methodology for Market Estimates
Our estimates are triangulated using a multi-layered approach: we synthesize official trade registry data, annual reports from top-tier energy firms, and primary interviews with CTOs and Lead Data Scientists in the field. Macro-indicators like regional CAPEX spending and energy policy shifts serve as the baseline, which is then validated against proprietary market sentiment analysis to ensure our projections align with real-world industry adoption patterns and budgetary commitments.
Scope and Parameters of the Report
This report examines the Cloud Computing In Oil And Gas Market through the lens of deployment, service, and application segments. The scope includes all major Upstream, Midstream, and Downstream activities. While our analysis covers global market trends, it specifically excludes general-purpose enterprise cloud usage that does not directly impact oil and gas-specific workflows, such as generic administrative email hosting or standard office document management systems.
Recent Developments and Industry Announcements
Strategic partnerships have recently intensified, notably between cloud hyperscalers and traditional Oilfield Services Providers. Announcements focus on deployment and orchestration platforms that enable remote wellhead monitoring. Companies like Risk Edge Solutions Private Limited are launching AI-powered risk mitigation tools, further highlighting the industry's pivot toward integrated, cloud-first operational models designed to minimize downtime and maximize productivity in volatile market conditions.