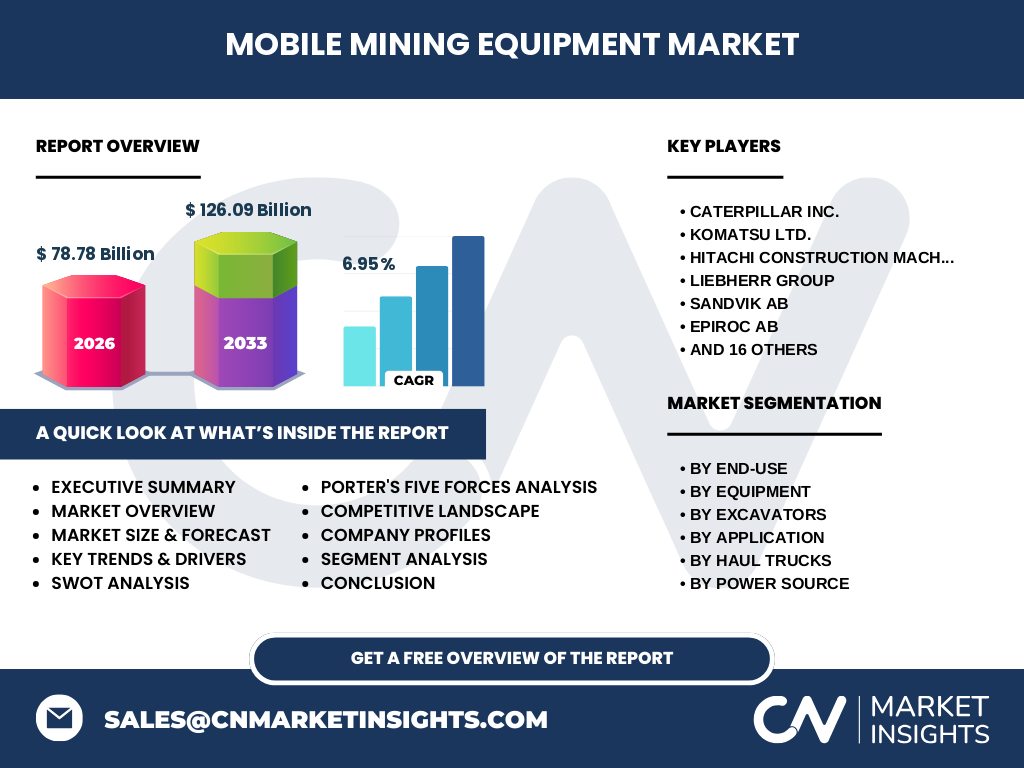
Market overview and industry significance of the Mobile Mining Equipment Market
The Mobile Mining Equipment Market serves as the backbone of global extraction operations, encompassing heavy machinery essential for surface and underground resource recovery. Our analysis identifies that this sector facilitates the movement of billions of tons of raw materials annually. Through precision-engineered assets like haul trucks and excavators, the industry ensures the operational continuity of metal, coal, and mineral mining, which remain critical to modern industrial supply chains.
Structural Growth Drivers and Market Constraints
The market is propelled by a 6.95% CAGR, driven by the global transition toward critical mineral extraction like lithium and copper. Conversely, strict emission mandates enforced by bodies such as the EU and EPA act as primary restraints. Operational challenges include high logistical hurdles at remote port facilities, yet opportunities abound for manufacturers pivoting toward autonomous haulage systems and digitized site management to enhance recovery efficiency.
Emerging trends and transformation patterns
The sector is witnessing a decisive Shift Toward Electrification and Autonomy. Leading innovators like Sandvik AB and Epiroc AB are prioritizing battery-electric vehicles to address ventilation constraints in underground mining. Furthermore, teleoperation technologies are gaining traction, allowing for increased safety and productivity. These trends represent a fundamental departure from traditional diesel-dependent mining, favoring OEMs capable of integrating complex digital software stacks.
COVID-19 impact analysis and recovery trajectory
The pandemic caused significant disruptions in global logistics, halting supply chains for critical components like semiconductors and specialized steel. However, our data reveals a robust post-pandemic rebound as commodity prices surged, incentivizing capital expenditure in the Mining Companies segment. The recovery trajectory, moving toward a $126.09 Billion valuation by 2033, underscores the resilience of mining fleet investments despite initial operational lockdowns.
Competitive landscape and strategic dynamics
The market features high concentration among global giants including Caterpillar Inc., Komatsu Ltd., and Liebherr Group. These players maintain dominance through massive R&D spending on fleet management systems. Competitive dynamics are currently shifting toward vertical integration, where companies like Hitachi Construction Machinery and SANY Heavy Industry differentiate themselves by offering complete end-to-end service lifecycles, ensuring high equipment availability for operators in challenging remote environments.
Executive summary of the Mobile Mining Equipment Market
The Mobile Mining Equipment Market is entering a period of unprecedented expansion, moving from $78.78 Billion in 2026 to a projected $126.09 Billion by 2033. This growth is sustained by global industrial demand for raw materials and a technological migration toward hybrid and electric power sources. Strategic focus remains on optimizing Total Cost of Ownership through predictive maintenance and advanced operator assist technologies.
Market forecast from 2027 to 2033
Based on our econometric modeling, the industry will maintain a healthy 6.95% CAGR through 2033. This consistent growth trajectory is predicated on high-volume demand from emerging markets and the replacement cycle of legacy diesel fleets. The transition to a $126.09 Billion market size reflects a sustained commitment by global stakeholders to modernize extractive capacities with higher-efficiency mechanical and electrical asset classes.
Segmentation analysis of equipment and end-use
We categorize the market by End-Use (Mining Companies, Contract Miners, Rental), Equipment Type (Haul Trucks, Excavators, Loaders, Drills), and Power Source. The Haul Trucks segment holds the highest value, reflecting the necessity for high-payload capacity in open-pit mining. Meanwhile, the Rental segment provides critical flexibility for projects with volatile production targets, acting as a buffer for mining companies during market price fluctuations.
Geographic distribution and regional performance
Performance varies significantly by region, with Latin America and Australia serving as massive consumption hubs due to their extensive mineral reserves. Our research indicates that North America remains a leader in technology adoption for autonomous equipment. Regional performance is heavily influenced by localized regulatory frameworks and the availability of grid infrastructure, which dictates the rate of adoption for electric-powered mining equipment.
In-depth regional review of key markets
In the Asia-Pacific region, massive state-backed infrastructure projects drive demand for Xuzhou Construction Machinery Group (XCMG) and Liugong equipment. Conversely, the African market relies heavily on rugged, diesel-powered machinery capable of enduring extreme conditions and limited service networks. These localized demands require manufacturers to balance high-tech innovation with the practical necessity for durable, easily repairable machinery in developing extraction corridors.
Company profiles and strategic positioning
Industry leaders like Caterpillar Inc. and Komatsu Ltd. position themselves as comprehensive solutions providers, offering integrated hardware and software ecosystems. Smaller, specialized firms like Normet Oy and Schopf Maschinenbau focus on niche underground utility segments, creating a segmented competitive field. The strategic focus across the board is moving toward connectivity, ensuring that every asset transmits real-time data back to central command platforms.
Porter's Five Forces assessment
The threat of new entrants is moderate, mitigated by high capital intensity and strict safety compliance hurdles. Bargaining power of buyers is significant, as large mining firms demand tailored, high-capacity machinery. Competitive rivalry is intense, centered on technological patent ownership and global service footprint. The threat of substitutes remains low, as there is no viable alternative to heavy-duty mobile machinery for large-scale earth-moving requirements.
SWOT analysis of the sector
The strengths lie in high barriers to entry and strong brand loyalty; weaknesses include vulnerability to commodity price volatility. Opportunities emerge from the decarbonization trend, which forces fleet replacement programs. Threats center on potential geopolitical trade restrictions and supply chain instability for critical microchips and high-grade alloys, which could delay the deployment of next-generation autonomous mining systems.
Value chain analysis and industry flow
The value chain begins with raw material suppliers (steel, rare earths) feeding into the OEMs. Manufacturers then integrate high-tech components (sensors, batteries) to produce mobile units. Distribution occurs through both direct sales and specialized dealers. The value flow culminates with end-users (Mining Companies, Contract Miners), who utilize the equipment to optimize tonnage-per-hour, ultimately feeding the global metallurgical and energy-commodity commodity markets.
Investment insights and high-potential areas
High-potential investment opportunities exist in aftermarket services and autonomous software integration. Our analysis suggests that investors should prioritize companies investing in battery technology for underground equipment, as this segment faces the strongest regulatory pressure to go green. Additionally, firms that successfully provide as-a-service models for equipment rental are seeing improved long-term revenue predictability compared to cyclical, pure-play capital equipment manufacturers.
Conclusion and key takeaways
The Mobile Mining Equipment Market is resilient, scaling toward $126.09 Billion through 2033. Success in this market now demands more than manufacturing excellence—it requires a transition into digitally integrated ecosystem management. As the industry grapples with the dual requirements of sustainability and productivity, firms that master electric drive-trains and autonomous operations will capture the largest market share in the coming decade.
Research methodology for baseline estimates
Our methodology utilizes triangulation across multiple data streams: we synthesize proprietary trade registry data, perform deep-dive interviews with industry chief engineers, and correlate findings with macroeconomic indicators. By reconciling bottom-up equipment demand forecasts with top-down capital expenditure trends from mining major participants, we ensure our figures—such as the 6.95% CAGR—are grounded in verifiable, actionable intelligence.
Scope of the report and coverage parameters
This report covers the global Mobile Mining Equipment Market, specifically focusing on equipment units, end-use sectors, and power sources. The scope excludes stationary mineral processing plants but includes all surface and underground mobile assets. Geographical coverage spans North America, Europe, Asia-Pacific, and emerging markets. Data limitations exist regarding small-scale artisanal mining, which is excluded from these professional-grade baseline projections to ensure market accuracy.
Recent developments and strategic moves
Recent industry activity highlights a surge in strategic partnerships between OEMs and battery suppliers to fast-track electric fleet development. Notable announcements include Sandvik’s expansion of their underground battery-electric portfolio and Epiroc’s increased focus on remote-controlled drilling automation. These strategic moves by key players demonstrate a clear market alignment with global decarbonization targets and a push to stabilize operations through heightened digitalization and real-time fleet analytics.