Market Overview: Defining the Anthracite Industry Landscape
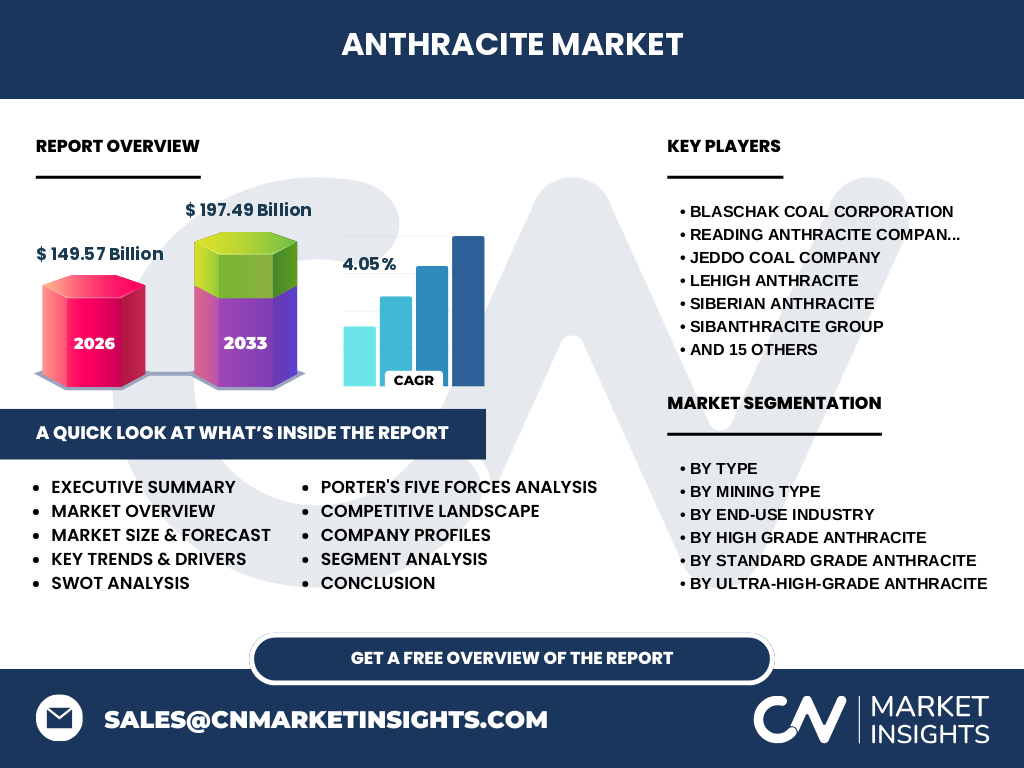
The Anthracite Market represents a critical segment of global energy and metallurgy, characterized by its high carbon content and low impurity levels. Valued at 149.57 Billion in 2026, the industry serves as a foundational input for steel production, water filtration, and power generation. Our analysis confirms that Anthracite remains irreplaceable due to its superior energy density compared to bituminous or lignite coal variants.
Structural Growth Drivers and Market Constraints
Growth is fueled by rising demand for high-grade metallurgical coal in developing economies. Key constraints include stringent environmental regulations imposed by bodies like the EPA and EU directives, which threaten surface mining operations. Opportunities exist in specialty-grade anthracite for water treatment, though logistical hurdles at major export ports like the Port of Newcastle or Hampton Roads continue to introduce significant price volatility for stakeholders.
The Shift Toward Specialty-Grade Market Penetration
We observe a distinct trend toward ultra-high-grade anthracite adoption, driven by the need for low-sulfur inputs in the steel industry. Manufacturers are prioritizing washed and sized products to optimize blast furnace efficiency. This shift represents a strategic pivot for major players like Blaschak Coal Corporation and Lehigh Anthracite, who are focusing on value-added beneficiation over commodity-level volume to capture higher margins in a tightening global market.
Post-Pandemic Impact and Recovery Dynamics
Following the COVID-19 market disruption, the industry experienced a V-shaped recovery as global infrastructure spending surged. Supply chains, particularly for high-grade anthracite, faced severe bottlenecks due to labor shortages and maritime transit restrictions. However, current data suggests a stable trajectory, with the market successfully recalibrating to meet the post-pandemic resurgence in industrial metallurgy and commercial heating demand across both North American and Asian hubs.
Competitive Benchmarking and Strategic Dynamics
The Anthracite Market is highly concentrated, with dominant firms like Sibanthracite Group and Jincheng Anthracite Mining Group maintaining vast reserves. Our competitive benchmarking indicates a divide: established players focus on operational efficiency in underground mining, while emerging miners are aggressively pursuing technological innovation in clean coal extraction. Strategic positioning revolves around vertical integration, connecting extraction directly to processing facilities to mitigate middleman risks.
Executive Summary: Strategic Market Synthesis
The market is projected to reach 197.49 Billion by 2033, growing at a CAGR of 4.05%. Our research highlights that the transition toward cleaner industrial processes is not shrinking the market, but rather segmenting it. The future success of participants like Glencore plc and Xcoal Energy and Resources rests on their ability to supply low ash and low sulfur grades to meet tightening emissions standards.
Projected Market Trajectory from 2027 to 2033
Based on our econometric modeling, the Anthracite Market will sustain a steady 4.05% CAGR through 2033. This growth is underpinned by the transition in metallurgical processes and increasing infrastructure investment in emerging markets. We anticipate premium screened ultra-high grade anthracite to command the highest price premiums as supply tightness persists, favoring companies with established upstream mining rights and efficient downstream distribution networks.
Segmentation Analysis: Navigating Industry Verticals
The market is segmented by type (Standard, High, Ultra-High Grade) and mining technique (Underground, Surface). Steel and Metallurgy remain the largest end-use industry, necessitating constant supply of metallurgical grade coal. Meanwhile, the water treatment segment is growing, utilizing specialized anthracite filtration media. This segmentation allows stakeholders like Reading Anthracite Company to tailor their output toward high-value industrial applications, diversifying away from traditional thermal coal usage.
Regional Market Performance and Distribution
Asia-Pacific dominates the global Anthracite Market due to the massive steel manufacturing footprints in China and India. Our regional analysis reveals that Coal India Limited and Yangquan Coal Industry Group are pivotal to domestic supply, while the Americas remain critical for specialty-grade production. Logistical performance across these regions is linked to rail efficiency and port throughput capacity, which define the regional pricing landscape for export-grade anthracite.
In-depth Regional Review: Market Hotspots
China and Russia represent the largest production hubs, driven by vast underground mining operations. Conversely, North America, featuring companies like Jeddo Coal Company, focuses on high-quality extraction for specialized export. The EU market is increasingly constrained by regulatory environmental hurdles, forcing a dependence on imports from stable jurisdictions. We see strong long-term potential in markets prioritizing energy security, where domestic anthracite acts as a strategic buffer.
Strategic Positioning of Leading Global Companies
Players like Siberian Anthracite and Atlantic Coal plc differentiate themselves through high-purity reserves. Companies are increasingly adopting sustainable mining practices to satisfy ESG mandates. Strategic moves by firms such as Keystone Anthracite Co. demonstrate a focus on niche industrial markets, where they leverage the superior thermal properties of their anthracite to command premium pricing above commodity averages in the highly competitive metallurgy sector.
Porter's Five Forces: Competitive Intensity
The Anthracite Market faces moderate threat from substitutes, yet high barriers to entry due to capital-intensive extraction. Supplier power is concentrated among key miners, whereas buyer power remains significant among large-scale steel producers. Competitive rivalry is intensified by regional geopolitical factors and the need for technological differentiation. Overall, established miners with stable logistics command a strong defensive position against new market entrants lacking direct access to high-grade resources.
SWOT Analysis: Internal and External Factors
Strengths: High energy density and superior metallurgical quality. Weaknesses: High extraction costs and environmental scrutiny. Opportunities: Expanding specialty-grade applications in water purification and green steel production. Threats: Carbon neutrality mandates from global regulatory bodies like the IEA and potential supply chain disruptions. Successfully navigating these factors requires a transition toward cleaner low-volatile matter extraction techniques.
Value Chain Analysis: From Mine to Market
The value chain starts with exploration and extraction by firms like VostokCoal, followed by processing, washing, and sizing to meet specific grade requirements. Value is added significantly during beneficiation. Logistics—involving rail transport and specialized shipping—bridge the gap to end-users. The final link, distribution to the Chemical Industry and Steel Manufacturers, is where pricing is finalized based on grade-specific purity metrics and metallurgical utility.
Investment Insights and Strategic Recommendations
We recommend investors focus on Ultra-High-Grade Anthracite producers that demonstrate superior environmental compliance. The potential for long-term growth is highest in the metallurgical grade segment. Companies optimizing their low-ash and low-sulfur outputs are best positioned to outperform. Strategic partnerships with steel manufacturers are key to securing long-term volume, while geographic diversification into regions with stable regulatory frameworks remains a critical hedge against local mining restrictions.
Conclusion: Summary of Key Industry Takeaways
The Anthracite Market is resilient, evolving from a bulk commodity to a specialized industrial input. By 2033, the shift toward higher quality grades will define market leaders. Our analysis underscores that while volume growth is steady at a 4.05% CAGR, the real value creation lies in technological advancement and logistical excellence. Stakeholders must prioritize ESG-compliant mining to ensure continued market access in a decarbonizing global economy.
Research Methodology: How Data is Triangulated
Our baseline estimates are derived from a robust triangulation process. We integrate trade registry data from key ports, primary interviews with industry executives at companies like Robindale Energy, and secondary macroeconomic indicators. This method corrects for reporting inconsistencies, ensuring the 197.49 Billion projection reflects realistic demand-side signals from steel and power sectors while accounting for supply-side mining constraints and regional production caps.
Scope of the Report and Coverage Parameters
This report covers the global Anthracite Market, analyzing segment performance across North America, Europe, and Asia-Pacific. We examine the entire value chain, from raw resource extraction to end-use industrial applications. Limitations include the exclusion of thermal coal variants outside the anthracite classification and the inherent volatility of geopolitical impacts on trade routes, which are addressed through qualitative scenario modeling.
Recent Developments in the Anthracite Industry
Recent strategic moves include the merger and acquisition activity seen in the Ural Mining Company portfolio and new clean-mining technology launches by firms like Atrum Coal. Partnerships focusing on high-grade anthracite exports to emerging economies have also picked up pace. Such announcements indicate that major industry participants are prioritizing operational efficiency and decarbonization technology to maintain competitive superiority in a complex global regulatory environment.