Market Overview: Defining the Family Business Services Market
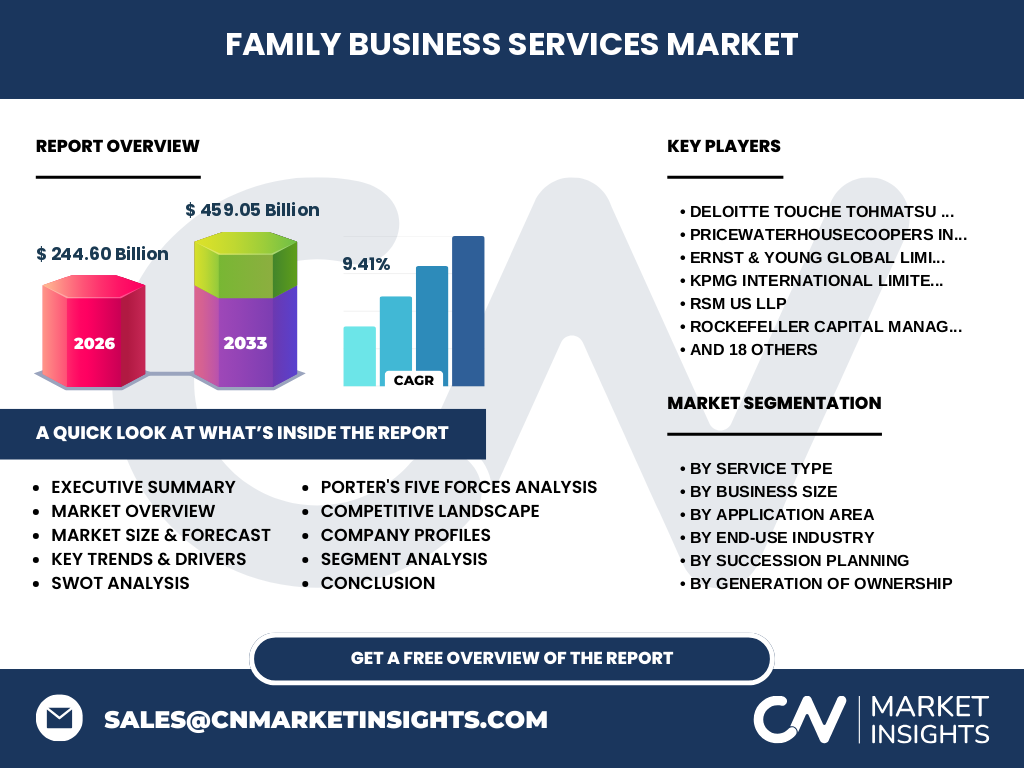
The Family Business Services Market is a specialized professional landscape facilitating the continuity and optimization of multi-generational enterprises. Valued at 244.60 Billion in 2026, the sector encompasses complex succession planning, family governance, and wealth management. It serves as the institutional backbone for organizations navigating the delicate intersection of emotional family dynamics and rigorous commercial operational requirements.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by a massive intergenerational wealth transfer cycle, necessitating professional intervention in succession planning. However, the market faces significant logistical hurdles, including evolving tax codes from bodies like the OECD and IRS. While demand for digital transformation provides an opportunity for consultancy firms to modernize legacy systems, market restraint stems from internal family resistance to third-party governance frameworks.
Emerging Trends and Strategic Patterns
The shift toward professionalized family offices is defining current market trends. Enterprises are increasingly integrating digital transformation tools to streamline strategic planning. Our analysis indicates a growing demand for conflict resolution and mediation services as complex global trade regulations demand higher levels of transparency and formalized decision-making protocols within multi-generational ownership structures.
COVID-19 Impact and Recovery Analysis
The pandemic acted as a catalyst for urgent legacy planning, forcing firms to accelerate leadership transition planning. While initial disruptions stalled expansion, the sector exhibited resilient recovery as businesses sought to navigate volatile global supply chains. Recovery was bolstered by firms like Deloitte and PwC, which provided critical advisory on risk management during the heightened periods of economic uncertainty.
Competitive Benchmarking and Strategic Dynamics
Market concentration remains high among the Big Four—Deloitte, PwC, EY, and KPMG—which leverage global networks to dominate Extra Large Family Business (XLFB) portfolios. Meanwhile, boutiques like The Family Business Consulting Group LLC differentiate by providing specialized, high-touch family governance advisory. Strategic dynamics are shifting toward integrated service models that bundle tax structuring with emotional conflict mediation.
Executive Summary: Key Findings
The Family Business Services Market is poised for substantial expansion, with a forecasted value of 459.05 Billion by 2033. This represents a robust CAGR of 9.41%. Our research identifies that succession planning and strategic growth are the primary engines of value, particularly within the large and conglomerate business tiers seeking international market entry.
Market Forecast: 2027 to 2033 Projections
Projections indicate that the sector will reach 459.05 Billion by 2033, driven by a steady CAGR of 9.41%. This growth is underpinned by the increasing complexity of estate and inheritance planning across multi-generation families. We anticipate that digital advisory platforms will become standard, significantly lowering barriers to entry for smaller service providers competing in the SMFB segment.
Segmentation Analysis: Core Market Roles
Market segmentation is defined by Service Type, Business Size, and End-Use Industry. Succession Planning remains the most critical service for First-Generation enterprises, while digital transformation is the priority for the Financial Services and Healthcare sectors. Each segment serves to balance capital preservation with the need for long-term strategic evolution in a competitive global economy.
Regional Market Performance and Geographic Distribution
North America and Europe currently represent the largest geographic markets, supported by a mature infrastructure of private wealth advisory firms. Conversely, the Asia-Pacific region shows the highest growth potential, as rapid wealth creation among multi-generation firms in regions like Singapore and Hong Kong necessitates sophisticated governance frameworks similar to those pioneered by Andersen Global.
In-Depth Regional Review
The US market is characterized by high demand for tax and financial structuring, reflecting complex local regulatory requirements. In Europe, firms prioritize legacy continuity and family constitution development. Meanwhile, the MENA region is seeing a surge in demand for professional board structuring, reflecting a regional pivot toward institutionalizing traditional business models to meet global standards.
Company Profiles: Strategic Positioning
Leaders like RSM US LLP and BDO International focus on integrated auditing and advisory, providing a holistic Risk Management approach. Specialist firms such as The Williams Group Inc. focus specifically on the intergenerational psychological dynamics of succession. This breadth ensures that whether an enterprise is a medium-sized retailer or an XLFB conglomerate, there is a tailored solution available.
Porter's Five Forces: Competitive Forces Assessment
The threat of new entrants is moderate, constrained by the requirement for deep-seated trust and reputation. Supplier power is low, while the bargaining power of buyers is high, particularly for Extra Large Family Businesses with significant leverage. Competitive rivalry is intense among major consultancy firms vying for multi-national mandates involving market entry and complex wealth advisory.
SWOT Analysis: Strategic Outlook
Strengths: Established trust and long-term advisory relationships. Weaknesses: High reliance on principal consultants. Opportunities: Tech-enabled digital transformation services for aging family businesses. Threats: Regulatory shifts that alter inheritance and wealth tax codes globally. By addressing these factors, service providers can better serve clients through innovative governance solutions.
Value Chain Analysis: Industry Structure
The value chain originates with academic and market research institutes providing foundational data, moving to high-level consultancy firms that synthesize this into strategic planning. The final tier involves specialized wealth managers and mediation facilitators who ensure execution. This flow supports the transformation of raw family capital into sustainable, multi-generational institutional wealth.
Investment Insights and High-Potential Areas
Investors should prioritize firms offering proprietary digital tools for family governance and conflict resolution. With the CAGR of 9.41%, there is a significant opportunity to invest in platforms that facilitate ownership transfer within the Small And Medium Family Business (SMFB) segment, which currently lacks sufficient, high-quality, digitized advisory resources.
Conclusion and Key Takeaways
The Family Business Services Market is moving toward full-service integration. The transition from 244.60 Billion to 459.05 Billion highlights that professional support is no longer elective but fundamental for survival. Success in this market demands a dual focus: technical tax structuring and the soft-skill mastery required to navigate intergenerational leadership transitions.
Research Methodology: Baseline Estimation
Baseline estimates are derived from a triangulation of data: proprietary trade registry analysis, primary stakeholder interviews with partners at leading firms like Rockefeller Capital Management, and macroeconomic indicators from global central banks. This ensures our market size estimates account for both public financial filings and private, non-disclosed consulting revenue streams.
Scope of the Report: Coverage Parameters
This report covers the global Family Business Services Market, focusing on professional services rendered to businesses with significant family ownership. Limitations include informal, local consultancy practices which fall outside standard reporting parameters. The scope prioritizes formal organizations operating in Manufacturing, IT, Finance, and Retail across key economic zones.
Recent Developments and Market Movements
Recent activity includes aggressive M&A by Bessemer Trust to expand its wealth advisory footprint, and Prima Consulting’s launch of new digital transformation suites. These strategic moves illustrate a broader industry trend of leveraging technology to scale high-touch service offerings, allowing firms to capture a larger share of the Multi-Generation enterprise market segment.