Market Overview: Defining the Industrial Aluminum Foil Roll Landscape
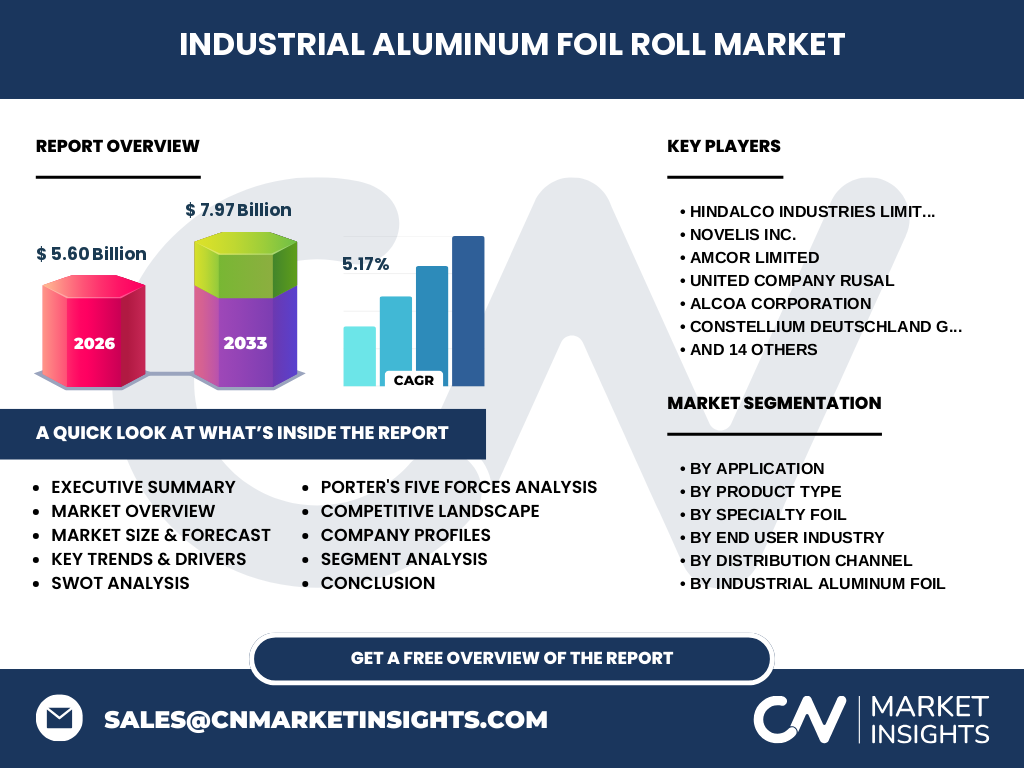
The Industrial Aluminum Foil Roll Market represents a mission-critical segment of the global metals processing industry. Valued at 5.60 Billion in 2026, it encompasses high-purity aluminum substrates used in sophisticated applications like thermal management and electrical shielding. Our analysis defines this scope as the intersection of primary smelting production and high-precision converting, essential for end-users ranging from automotive manufacturers to specialized pharmaceutical packagers.
Structural Growth Drivers and Market Constraints
Growth is propelled by a 5.17% CAGR through 2033, driven by electrification in automotive sectors and increasing demand for barrier-protection in medical supplies. Conversely, volatility in primary aluminum ingot prices and stringent environmental regulations imposed by bodies like the EU’s Carbon Border Adjustment Mechanism act as significant restraints. Logistical bottlenecks at major shipping hubs further complicate global supply chain agility for bulk foil distributors.
Emerging Trends Reshaping Industrial Foil Consumption
We observe a definitive shift toward Ultra-Thin Aluminum Foil technology to reduce secondary packaging weights. Innovations in hydrophobic foil coatings are currently revolutionizing the HVAC and construction sectors, where moisture resistance is paramount. Market participants like Novelis Inc. and Amcor Limited are leading this technical transition, focusing on high-performance materials that provide superior thermal insulation while meeting stringent sustainability mandates.
COVID-19 Impact and Long-Term Recovery Trajectory
The pandemic caused initial manufacturing paralysis due to labor shortages and port closures. However, the surge in pharmaceutical demand—specifically for blister pack foils—accelerated the recovery. Our research indicates that the industry adapted through diversified sourcing strategies, shifting away from over-reliance on singular Asian export channels, ultimately resulting in the current robust forecast of 7.97 Billion by 2033.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is characterized by high concentration among key players like Hindalco Industries Limited, United Company RUSAL, and Constellium. Strategic dynamics hinge on vertical integration; companies controlling both smelting and foil conversion gain a distinct cost advantage. Mid-tier innovators like Alcomet Germany GmbH differentiate through precision engineering in specialty segments, creating significant barriers to entry for unspecialized commodity producers.
Executive Summary: Synthesis of Industrial Aluminum Foil Market Findings
The Industrial Aluminum Foil Roll Market is on a definitive expansion path, rising from 5.60 Billion in 2026 to 7.97 Billion by 2033. This growth is underpinned by the transition toward sustainable, high-barrier packaging and the expansion of the electronics sector. Industry leaders are pivoting toward advanced laminate technologies and energy-efficient manufacturing to maintain competitive margins in an evolving, regulation-heavy global economy.
Market Forecast: 2027 to 2033 Projections
Based on our econometric modeling, the market is poised to reach a valuation of 7.97 Billion by 2033. This consistent growth, sustaining a 5.17% CAGR, is predicated on the persistent requirement for lightweight shielding and protection across the automotive, electronics, and construction verticals. Investment in circular economy infrastructure remains the primary factor determining which firms will capture the largest share of this forecasted market volume.
Segmentation Analysis: Deep Dive into Product and Application Roles
Segmentation is broken down into three core types: Industrial Aluminum Foil, Pharmaceutical Aluminum Foil (critical for cold forming), and Specialty Foil. These segments serve specific industrial needs, from structural insulation to safety-critical heat seals. By categorizing these, we identify that the Pharmaceutical segment offers the highest margin potential, while Industrial Laminated rolls command the highest volume within the global distribution channels.
Regional Market Performance and Geographic Distribution
Regional performance varies based on industrial infrastructure. Europe remains a hub for high-end anodized aluminum foil production, led by firms like AMAG Rolling GmbH. Meanwhile, the Asia-Pacific region, spearheaded by China Hongqiao Group Limited, dominates in terms of production volume and export capacity. Our analysis maps these regional dynamics to identify where supply chain proximity offers the most significant competitive advantage to end-users.
In-depth Regional Review: Key Industrial Hubs
In North America, the market focuses on food and beverage packaging efficiency, with players like Handi-foil of America Inc. leading, while the German market emphasizes high-precision automotive conductors. These regional clusters are supported by distinct logistical networks. The Middle East is emerging as a critical processing center, leveraging energy cost advantages to attract major global converters seeking lower operational expenditures for energy-intensive foil rolling processes.
Company Profiles: Strategic Positioning of Market Leaders
Leading entities like Amcor Limited and Constantia Flexibles are aggressively pursuing sustainability-linked acquisitions to bolster their pharmaceutical portfolios. Meanwhile, Novelis Inc. focuses on high-strength alloys for the EV battery segment. By contrasting these strategic trajectories, our research highlights how top-tier incumbents are successfully shielding themselves from price volatility while capitalizing on the shift toward specialty, value-added foil products rather than simple commodity rolls.
Porter's Five Forces: Competitive Forces Assessment
The threat of new entrants is moderate, limited by high capital expenditure requirements for rolling mills. However, the bargaining power of suppliers is high due to the scarcity of high-purity aluminum ingots. Competitive rivalry is fierce, intensified by regional players like Zhangjiagang Goldshine Aluminium Foil Co. Ltd, driving companies to innovate in specialty segments like hydrophobic foil to sustain long-term profit margins.
SWOT Analysis: Strategic Industry Insights
The market’s primary strength lies in the versatility of its materials. A significant weakness is the heavy reliance on global supply chain stability. Opportunities abound in the green energy sector, specifically for battery current collectors. Conversely, threats include aggressive environmental policy shifts and the availability of composite alternatives, which may challenge aluminum’s historical dominance in packaging and insulation sectors.
Value Chain Analysis: From Raw Material to End-User
The value chain begins with bauxite mining and primary aluminum smelting, followed by cold rolling, finishing, and conversion. Value is added at each step through laminating, annealing, and coating. Companies like Eurofoil Luxembourg SA occupy key mid-stream positions, adding value by transforming raw aluminum sheets into specific gauges for electronics and medical clients, who then distribute the final products globally.
Investment Insights and High-Potential Growth Areas
Investors should prioritize companies investing in circular aluminum recycling and ultra-thin, high-performance foil. The shift toward electric vehicle battery current collectors presents the most significant growth opportunity. Our research indicates that players with localized production nodes—capable of bypassing volatile shipping costs—will likely yield the highest risk-adjusted returns over the next seven years, outperforming the projected 5.17% CAGR.
Conclusion and Key Takeaways for Stakeholders
The Industrial Aluminum Foil Roll Market is transitioning from a commodity-driven environment to a specialty-focused ecosystem. With the market moving from 5.60 Billion to 7.97 Billion by 2033, the path to success involves mastering specialty coatings and ensuring regulatory compliance. Success in this market now demands high technical competency, strategic supply chain diversification, and an aggressive stance on sustainable production methods.
Research Methodology: How We Triangulated Data
Our estimates are built on a triangulation methodology. We combined trade registry data from the International Aluminium Institute with primary interviews from executive-level stakeholders. We then layered these findings against macroeconomic indicators, including regional manufacturing output and automotive production indices. This multi-factor approach ensures that our 5.17% CAGR estimate remains grounded in both empirical historical data and realistic forward-looking industry capacity assessments.
Scope of the Report: Coverage Parameters and Limitations
This report covers the global Industrial Aluminum Foil Roll Market across major segments: packaging, insulation, electrical, and heat management. While our data provides deep insight into 2027–2033 trends, the analysis is limited to industrial-grade foils, excluding residential-grade household foils. All financial figures are projected in constant currency, and geographic scope includes all primary production regions, with a focus on companies maintaining at least a regional export presence.
Recent Developments: Major Strategic Moves and Launches
The market has seen a flurry of activity, including Constantia Flexibles ramping up their sustainable blister-pack innovation and Hindalco focusing on high-barrier foil solutions. Strategic partnerships have also surged, as automotive OEMs partner directly with mills like AMAG Rolling GmbH to secure supply for EV heat management components. These announcements demonstrate an industry-wide pivot toward long-term contracts and technical integration with final application manufacturers.