Market overview and industry significance of the Digital Travel Market
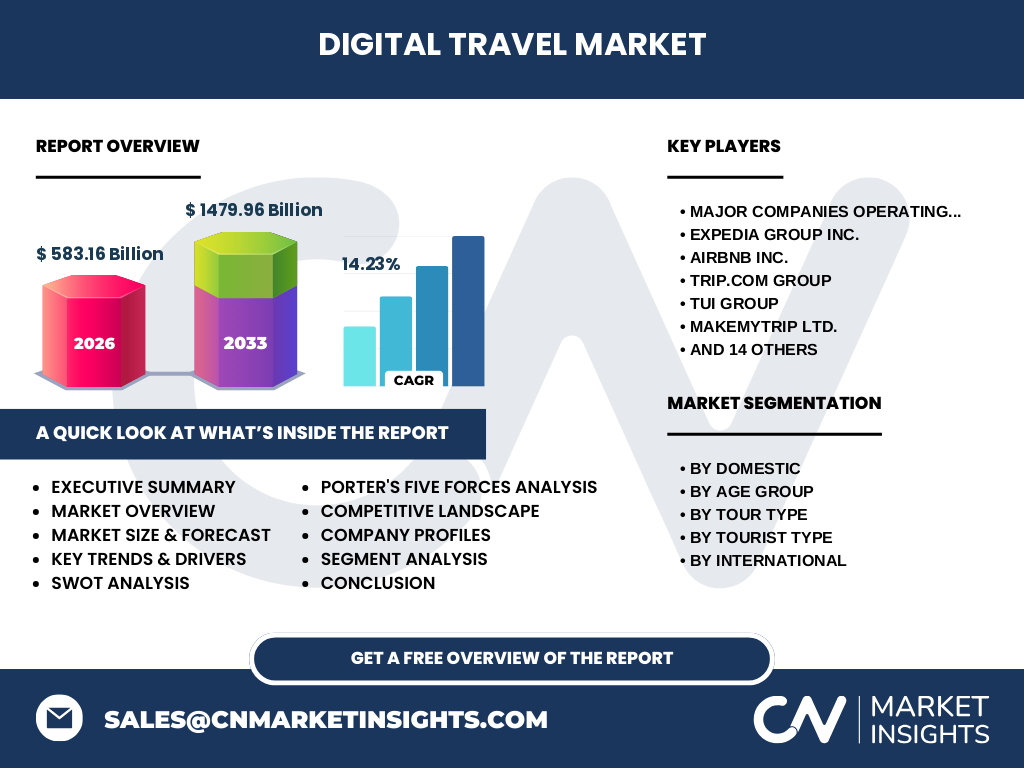
The Digital Travel Market represents the comprehensive ecosystem of online platforms, booking engines, and mobile-first travel management tools. Valued at 583.16 Billion in 2026, this sector acts as the primary digital gateway for global mobility. It connects service providers—from global carriers to boutique stays—with end-users, functioning as the backbone of modern tourism infrastructure and driving frictionless consumer experiences across international borders.
Structural Growth Drivers and Market Constraints
Growth is fueled by the ubiquity of mobile connectivity and AI-driven personalization, alongside a surge in independent and adventure travel segments. However, the industry faces significant restraints, including stringent regulatory hurdles from bodies like the IATA regarding ticket transparency and logistical challenges in cross-border payment processing. These variables dictate how firms like Expedia Group Inc. optimize their global supply chains.
Emerging trends and growth patterns in digital travel
We observe a paradigm shift toward sustainable and eco-tourism, with travelers prioritizing lower carbon footprints. Hyper-personalization, driven by machine learning, is transforming the leisure travel segment, allowing players like Klook Travel Technology Ltd. to curate unique experiences. Meanwhile, the integration of real-time travel analytics has become a prerequisite for maintaining competitive dominance in an increasingly volatile global landscape.
COVID-19 impact analysis and recovery trajectory
The pandemic forced a fundamental restructuring of the Digital Travel Market, accelerating digital adoption and contactless service models. While the sector faced immediate contraction, the recovery has been characterized by a robust rebound in domestic staycations and flexible booking policies. Companies like TUI Group pivoted successfully by leveraging digital agility to navigate shifting health mandates and unpredictable travel corridor closures.
Competitive landscape and strategic market concentration
The market features high concentration among giants like Booking Holdings Inc. and Airbnb Inc., which leverage massive data moats. Strategic dynamics focus on ecosystem integration, where players like Trip.com Group expand from simple ticketing to full-service lifestyle platforms. Mid-tier competitors like MakeMyTrip Ltd. maintain regional strength by addressing hyper-localized consumer preferences within highly competitive emerging markets.
Executive summary: Synthesis of key market findings
The Digital Travel Market is poised for exponential growth, with a projected valuation of 1479.96 Billion by 2033 and a CAGR of 14.23%. Success hinges on mastering digital transformation, catering to the nuanced needs of various age demographics, and navigating the complexities of inbound and outbound international travel. Our research confirms that firms investing in AI-driven user-centric interfaces will capture the largest market share.
Market forecast from 2027 to 2033
Based on our econometric modeling, the Digital Travel Market will maintain a consistent 14.23% CAGR throughout the forecast period. We anticipate a rapid valuation climb from 2027 to 2033, reaching 1479.96 Billion. This trajectory is supported by increased consumer disposable income, the resurgence of long-haul travel, and the expansion of digital infrastructure in previously underserved geographic territories.
Segmentation analysis of travel categories
The market is segmented by Domestic travel (leisure, business, adventure, solo, group) and International travel (inbound, outbound, luxury, eco-tourism). Age-based segmentation (26-55 years) allows for targeted marketing precision. Each segment plays a vital role; for instance, the luxury international segment drives high-margin revenue, while staycations provide volume, ensuring a balanced portfolio for platform operators like eDreams ODIGEO.
Geographic distribution and regional performance
Regional performance remains uneven; mature markets prioritize efficiency and loyalty programs, while high-growth regions like Southeast Asia see rapid adoption of mobile-first booking platforms. Traveloka and Oyo Rooms serve as prime examples of firms capitalizing on regional nuances. Our analysis shows that geographic diversity is critical for mitigating localized geopolitical risks and seasonal travel fluctuations across the globe.
In-depth examination of key regional markets
North America and Europe currently dominate in terms of gross booking value, yet the Asia-Pacific region demonstrates the fastest adoption rate among the 26-35 age cohort. Regulatory scrutiny in the EU, spearheaded by the Digital Markets Act, forces local players to innovate faster. Meanwhile, Yatra Online Inc. excels by navigating the complex infrastructure requirements inherent to the rapidly evolving South Asian market.
Strategic positioning of leading industry participants
Major players occupy distinct niches: American Express Global Business Travel focuses on high-value corporate travel management, whereas GetYourGuide GmbH dominates the experience and tour activities sector. Hopper Inc. leverages predictive analytics to differentiate through price forecasting, proving that strategic positioning is no longer just about inventory scale but about providing proprietary data insights that benefit the modern traveler.
Porter's Five Forces analysis for Digital Travel
The Digital Travel Market faces intense rivalry and high buyer power due to price transparency. However, high entry barriers exist for new startups due to substantial infrastructure costs and the necessity for global distribution partnerships. Substitutes are minimal, though direct-to-supplier booking remains a moderate threat. Supplier power is concentrated among major airlines and hotel chains, necessitating strategic alliances for digital intermediaries.
SWOT analysis of the sector
Strengths: Massive scalability and data-rich environments. Weaknesses: Heavy dependence on external supplier inventory and potential for platform fatigue. Opportunities: Expanding into AI-integrated travel planning and untapped emerging markets. Threats: Increasing geopolitical instability affecting long-haul travel and aggressive regulation by regional authorities like the EU Commission regarding consumer data protection and booking transparency.
Value chain analysis: From suppliers to end-users
The value chain starts with raw inventory suppliers (airlines, hotels) who feed data into Global Distribution Systems (GDS). Digital travel platforms like lastminute.com Group add value by aggregating this data, applying markup, and providing user-friendly UI/UX. The final link is the consumer interface, which converts intent into bookings, effectively streamlining the complex flow between disparate travel service providers and the end-user.
Strategic investment insights and high-potential areas
We identify Sustainable Travel Technology and AI-driven travel assistants as the highest potential investment areas for 2027 and beyond. Investors should look for platforms like Despegar.com Corp. that demonstrate strong localized expertise and a commitment to technological R&D. The integration of fintech services within travel apps represents a massive cross-selling opportunity that remains significantly under-exploited in current market offerings.
Conclusion and key takeaways for stakeholders
The Digital Travel Market will reach a landmark valuation of 1479.96 Billion by 2033. Success will be defined by an operator's ability to balance technological innovation with regional regulatory compliance. Stakeholders must prioritize seamless mobile experiences and sustainable tourism initiatives to maintain relevance in a competitive landscape where brand loyalty is increasingly difficult to secure and maintain over time.
Research methodology: How baseline estimates are triangulated
Our methodology utilizes a triangulation approach, synthesizing trade registry data, primary interviews with C-suite stakeholders, and secondary macroeconomic indicators. We cross-reference booking platform performance metrics with IATA passenger volume reports. This rigorous process ensures our 14.23% CAGR estimate is grounded in empirical reality, minimizing variance by adjusting for regional GDP correlations and historical post-pandemic recovery trends observed across global markets.
Scope of the report: Parameters and limitations
This report covers the global Digital Travel Market, excluding offline-only travel agencies and non-digitized hospitality segments. The scope is limited to B2B and B2C online booking platforms. While we capture data across various segments including leisure, business, and adventure travel, geopolitical events causing sudden border closures remain an exogenous variable that can impact the precision of our 2033 projections.
Recent developments, partnerships, and strategic moves
Recent activity highlights a trend of strategic consolidation and platform diversification. Key announcements from Easy Trip Planners Ltd. and others reflect a move toward super-app integration, blending financial services with travel. Partnerships between tech providers and regional hospitality firms are increasing, aimed at capturing the growing outbound travel demand from emerging markets and enhancing the end-to-end journey experience through real-time communication tools.