Market overview of the Concrete Sealer Market
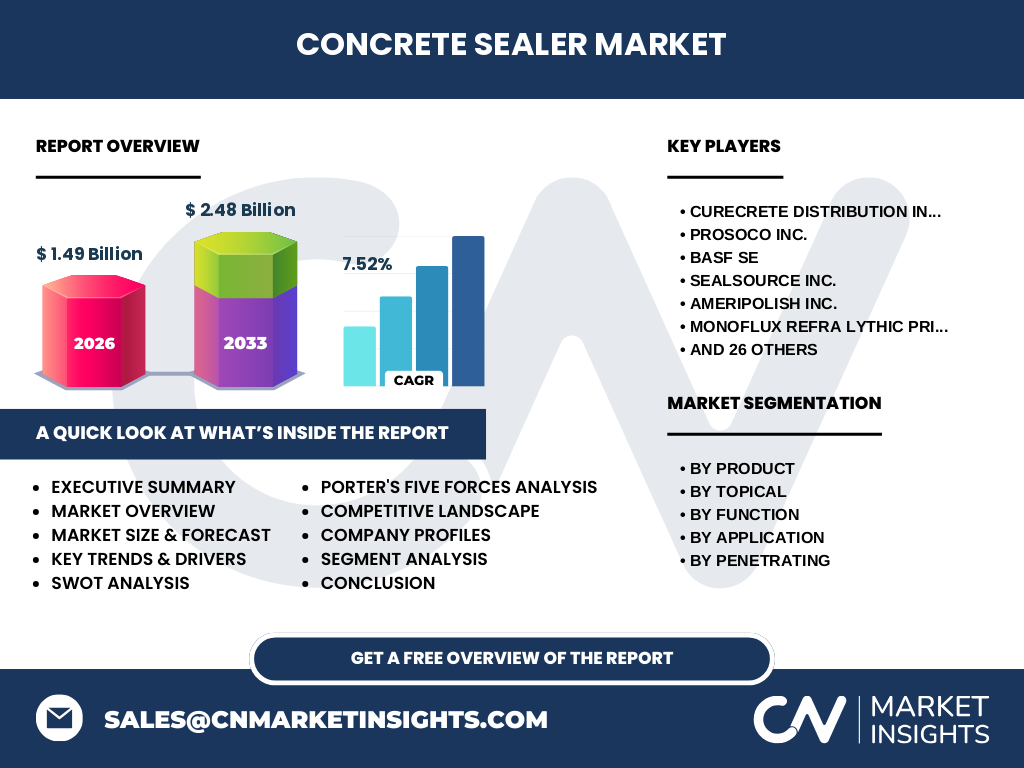
The Concrete Sealer Market functions as a critical protective layer for infrastructure, preserving structural integrity against chemical ingress and moisture. Valued at 1.49 Billion in 2026, this sector encompasses penetrating and topical formulations. It is essential for global asset management, preventing premature spalling and carbonation in concrete surfaces across residential, commercial, and industrial built environments.
Structural Growth Drivers and Market Constraints
Growth is primarily fueled by increasing infrastructure spending and the urgent need for asset rehabilitation. Key drivers include rapid urbanization and high demand from industrial flooring projects. Conversely, logistical hurdles regarding VOC emission compliance and fluctuating raw material costs for epoxy and acrylic resins pose significant restraints for manufacturers like Sika AG and BASF SE.
Emerging trends and long-term patterns
The shift toward sustainable and eco-friendly coatings is dominating the market. We observe a significant pivot toward bio-based sealers and water-based formulations that satisfy stringent environmental mandates. Technological advancements in nanotechnology-based sealers by innovators like Xypex Chemical Corp. are enhancing durability, allowing for deeper penetration and superior hydrophobic properties compared to traditional acrylic alternatives.
Post-pandemic trajectory and recovery analysis
Following initial supply chain disruptions due to COVID-19, the market demonstrated a robust recovery. As global logistics stabilized, pent-up demand in the construction sector accelerated, specifically within commercial warehousing. The current trajectory suggests a resilient growth phase, as contractors prioritize long-term maintenance over short-term savings, bolstering the demand for high-performance sealers manufactured by firms such as Laticrete International Inc.
Competitive landscape and strategic dynamics
The Concrete Sealer Market is characterized by a mix of specialized chemical giants and regional niche players. Market concentration is moderate, with RPM International Inc. and PPG Industries Inc. leveraging extensive distribution networks. Meanwhile, firms like Curecrete Distribution Inc. and AmeriPolish Inc. compete through intense technical specification and direct-to-contractor support, driving innovation in decorative and industrial finishing.
Executive summary of key findings
Our research indicates the Concrete Sealer Market is set for significant expansion, reaching 2.48 Billion by 2033 with a CAGR of 7.52%. The sector is transitioning from traditional surface coatings to sophisticated penetrating silanes and siloxanes. Success in this landscape necessitates geographic diversification and adherence to evolving international building codes, particularly in high-growth regions like North America and Asia-Pacific.
Forecast for the Concrete Sealer Market through 2033
Projected to grow from 1.49 Billion in 2026 to 2.48 Billion by 2033, the market reflects a stable CAGR of 7.52%. This forecast assumes sustained growth in commercial and industrial construction and an increasing focus on the lifecycle maintenance of aging infrastructure. Market participants must align their portfolio with high-performance silicate and silane-based systems to capture this sustained growth.
Segmentation analysis by product and function
Market segmentation provides a clear strategic map: By Product, the market splits into Silicates, Silane/Siloxane, Acrylics, and Epoxies. By Function, it distinguishes between Topical and Penetrating solutions. While topical acrylics remain high-volume for residential use, Penetrating silane/siloxane sealers are becoming the preferred standard for heavy-duty industrial and infrastructure projects due to their superior longevity and breathability.
Geographic performance and regional distribution
Regional performance is dictated by industrialization rates and climate-driven maintenance requirements. North America remains a dominant hub, while Asia-Pacific exhibits the fastest growth due to aggressive infrastructure development. European markets focus heavily on environmental compliance, favoring manufacturers like Mapei SPA and Akzo Nobel N.V. that provide low-VOC, high-compliance products designed for harsh weather cycles and strict maritime regulations.
In-depth regional market review
In North America, demand is driven by infrastructure renovation, while in the Asia-Pacific region, new construction projects dominate the Concrete Sealer Market. Emerging markets in the Middle East present unique challenges, such as extreme heat affecting curing times, favoring specialized companies like Stone Technologies Ltd. that provide climate-stabilized formulations. Our analysis shows these regions require localized distribution networks and technical support to maintain market share.
Strategic positioning of leading companies
Top players like Sika AG and W. R. Meadows Inc. leverage R&D-led portfolios to dominate, while specialized innovators like KreteTek Industries Inc. focus on high-margin, professional-grade silane sealers. The strategic positioning of firms such as Euclid Chemical Co. reflects an emphasis on value-added services, including job-site technical support, which is a critical differentiator in a crowded Concrete Sealer Market with high competitive intensity.
Porter's Five Forces assessment
The threat of new entrants is moderate due to high regulatory barriers for chemical manufacturers. Bargaining power of buyers is high, as contractors consolidate procurement. However, supplier power is significant for raw materials like high-grade epoxies. The intensity of competitive rivalry is high, with players like RPM International Inc. and PPG Architectural Finishes Incorporated engaged in constant innovation cycles to secure project specifications.
SWOT analysis of the industry
Strengths: Established distribution and essential nature of the product. Weaknesses: Dependence on volatile petrochemical raw materials. Opportunities: Expansion into smart, self-healing concrete sealers and massive infrastructure bills in major economies. Threats: Increasing stringency of global environmental regulations and potential supply chain bottlenecks at major ports. Success hinges on a company's ability to maintain R&D intensity despite these macroeconomic threats.
Value chain analysis of the sector
The value chain starts with the extraction of raw materials for resins and catalysts, moving through chemical synthesis and specialized manufacturing. Value flow then moves to distributors and specifiers—like engineers and architects—who dictate the final application. End-users, ranging from commercial property owners to state highway departments, represent the final stage. The most significant value-add occurs during the product formulation and technical sales advisory phases.
Investment insights and high-potential areas
Investors should prioritize companies focused on water-based silane and siloxane technologies, as these are increasingly mandated by local governments. High-potential areas include integrated asset management solutions where the sealer is part of a larger maintenance contract. Firms with strong R&D footprints, such as Xypex Chemical Corp. and ChemMasters Inc., represent stable investment vehicles capable of outperforming the projected 7.52% CAGR.
Conclusion and key takeaways
The Concrete Sealer Market is a vital, growing segment of the global construction industry, projected to reach 2.48 Billion by 2033. Success depends on navigating the transition to eco-compliant technologies and maintaining robust relationships with specifiers. Companies that balance localized distribution with advanced, site-specific product formulations will dominate this evolving market landscape over the next decade.
Research methodology for the report
Our baseline estimates are triangulated using a proprietary mix of trade registry data, primary stakeholder interviews with industry chemical engineers, and secondary macroeconomic indicators. We validate market size by cross-referencing regional building permit data with average sealer application rates per square meter, ensuring our projections accurately reflect the real-world demand patterns observed by leading participants like Sika AG and Mapei SPA.
Scope of the Concrete Sealer Market report
This report provides comprehensive coverage of the Concrete Sealer Market, including product types, functional segmentation, and regional performance through 2033. Limitations include the exclusion of small, local artisanal coating manufacturers and the volatility of niche, highly specialized experimental protective additives. The scope is strictly focused on industrial-grade, commercial, and residential applications, ensuring data relevance for strategic decision-makers and investors.
Recent developments and strategic moves
Recent developments indicate a wave of strategic partnerships and sustainability-focused launches. Major players like RPM International Inc. have actively acquired niche firms to enhance their green product portfolio. Additionally, new product launches by KreteTek Industries Inc. underscore the industry's push toward faster-curing, high-penetration sealers. These moves signify a market-wide shift toward efficiency and compliance, preparing the industry for the rigorous demands of the next seven years.