Market Overview: Defining the Advance Directives Market landscape
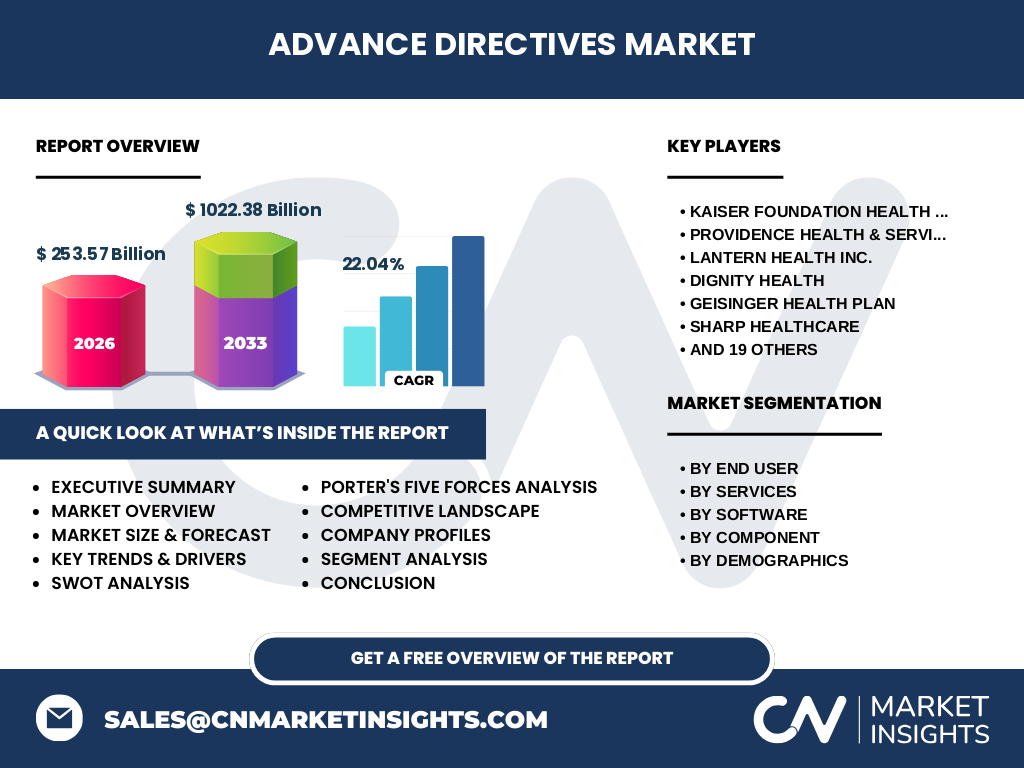
The Advance Directives Market encompasses the critical intersection of legal, healthcare, and digital documentation services. It functions as the infrastructure for end-of-life autonomy, enabling patients to codify medical preferences. As of 2026, the market is valued at 253.57 Billion, reflecting its vital role in modern medical ethics and administrative compliance within complex regulatory environments like the U.S. HIPAA frameworks.
Structural Growth Drivers and Market Constraints
Primary growth is fueled by an aging global population and the digitization of healthcare records. Conversely, regulatory fragmentation acts as a significant restraint, as advance directives vary by jurisdiction. Challenges include data interoperability hurdles between providers like Kaiser Foundation Health Plan Inc. and regional legal databases, while opportunities lie in integrating Cloud-Based Advance Directive Solutions into mainstream electronic health record (EHR) systems.
Emerging Trends and Strategic Growth Patterns
A pivot toward mobile-first accessibility is currently defining market expansion. Innovators like Cake Software Inc. and Everplans Inc. are revolutionizing the user journey, moving beyond static PDFs to interactive platforms. This trend toward consumer-centric digital health suggests that users now prioritize 24/7 access to directives, ensuring that medical facilities have real-time, authenticated data during emergency triage scenarios.
COVID-19 Impact and Recovery Trajectory
The pandemic served as a catalyst for adoption, forcing a radical shift in how end-of-life planning is perceived and managed. With in-person legal consultations restricted, companies like LegalZoom.com Inc. saw surge demand for digital documentation. Post-COVID, the recovery trajectory remains aggressive, as institutions now prioritize remote-ready directive infrastructure to mitigate the administrative bottlenecks experienced during the 2020 healthcare crisis.
Competitive Landscape and Strategic Market Positioning
The market is a mix of specialized tech firms and large healthcare systems. Players like ADVault Inc. and DocuBank Ltd. occupy the niche of digital repository security, while health giants like Providence Health & Services integrate these services into their clinical workflow. The landscape is characterized by high strategic integration, where success depends on interoperability partnerships rather than purely proprietary software ownership.
Executive Summary: High-level synthesis of Advance Directives Market findings
The Advance Directives Market is entering an era of explosive growth, projected to reach 1022.38 Billion by 2033 with a CAGR of 22.04%. Our analysis indicates a clear shift from manual, paper-based legal services toward automated digital management platforms. Organizations that successfully bridge the gap between legal enforceability and healthcare operational efficiency will capture the largest market share during this transition.
Market Forecast: Growth Projections 2027-2033
Based on current trajectories, the market is set to achieve a compound annual growth rate of 22.04%, culminating in a 1022.38 Billion market valuation by 2033. This growth is driven by the scalability of cloud-based platforms and the increasing demand for Document Storage And Management Services within the aging demographic, which remains the most critical consumer cohort for adoption.
Segmentation Analysis: Deep Dive into Market Verticals
We categorize this market by component, service, and demographic. The Software component, particularly Cloud-Based Advance Directive Solutions, is seeing the highest velocity. By end-user, the B2B segment—integrating services into hospital groups like Dignity Health—is outpacing B2C growth. Meanwhile, Training and Support Services remain essential for legal compliance, ensuring documents meet regional court-sanctioned criteria for end-of-life decision-making.
Regional Market Analysis: Geographic Distribution
North America leads the sector, bolstered by sophisticated digital healthcare laws and major players like Affirm Health Inc. The Asia-Pacific region is emerging as a high-potential market due to rapidly aging demographics and government-led digital health initiatives. European markets remain strictly regulated, requiring companies to align software features with localized privacy laws, which influences the pace of technology penetration compared to the more decentralized North American market.
In-depth Regional Review: Performance Metrics
In North America, adoption is anchored by established hospital networks such as Geisinger Health Plan. Conversely, the Australian market is witnessing accelerated interest via Advance Care Planning Australia Ltd. and Thanacare Pty Ltd. These entities are tailoring digital directives to comply with localized health mandates. The key to regional performance remains regulatory alignment, as standardized digital directive acceptance varies significantly between federal and regional healthcare authorities.
Company Profiles: Strategic Positioning and Focus
Leading companies like ThroughCare Inc. and WiserCare Inc. focus on clinical integration, ensuring that end-of-life decisions directly inform provider action. Trust & Will Inc., meanwhile, dominates the B2C space by simplifying the legal document creation process. This diversity in positioning allows the sector to cater to both individual planning needs and the complex, high-volume requirements of large-scale healthcare networks.
Porter's Five Forces Analysis
The threat of new entrants is moderate, limited by high regulatory compliance hurdles. Supplier power is low as software infrastructure is increasingly commoditized. Buyer power is significant among large health systems that demand customized EHR integration. The competitive rivalry is intense, driven by aggressive software feature sets from players like GoodTrust Corporation, while the threat of substitution remains low given the legal necessity of documented directives.
SWOT Analysis: Strategic Assessment
Strengths: High barriers to entry for newcomers and essential service nature. Weaknesses: Significant regional regulatory fragmentation and high implementation costs. Opportunities: Integration with AI-driven health triage systems and untapped emerging markets. Threats: Potential data breaches causing loss of consumer trust in cloud storage services and restrictive legislative changes that could invalidate digital-only directive signatures.
Value Chain Analysis: From Creation to Implementation
The value chain starts with legal framework developers and software engineers who codify jurisdictional requirements. It flows through Document Storage and Management platforms, reaching the healthcare frontline where providers—like Island Health Authority—utilize these documents. The final stage involves Training and Support, ensuring that patients and medical teams are effectively aligned, which is critical for maximizing the utility and legal reliability of the end product.
Investment Insights and Strategic Recommendations
Investors should prioritize companies with scalable B2B integration capabilities. The shift toward interoperable cloud platforms suggests that firms partnering with major EHR vendors are positioned for superior long-term returns. We identify high-potential in AI-assisted legal compliance tools that automatically update directives to match changing state laws, reducing manual oversight for both users and healthcare provider organizations.
Conclusion and Key Takeaways
The Advance Directives Market is set for transformative growth through 2033. By 2026, the sector has proven its resilience and necessity, reaching 253.57 Billion. The future success of participants hinges on digital-first strategies, seamless regulatory compliance, and deeper integration with clinical workflows. The shift from manual to automated, cloud-based systems is not merely a trend but a structural evolution of the industry.
Research Methodology: How we triangulated our data
Our estimates are triangulated using a multi-dimensional approach: analyzing official trade registry data from legal-tech sectors, conducting primary interviews with stakeholders at firms like Vital Decisions LLC, and synthesizing macroeconomic trends regarding aging populations. We adjust baseline figures based on localized regulatory feedback, ensuring our 22.04% CAGR forecast accounts for varying regional healthcare adoption rates and current technological barriers.
Scope of the Report: Parameters and Limitations
This report examines the global Advance Directives Market, encompassing software platforms, legal consultancy, and document management services. It excludes general legal services not focused on medical care. While we provide a detailed 2027 to 2033 forecast, market performance remains subject to fluctuations in national health policy, which could impact the speed of digital transformation across specific, highly-regulated geographical territories.
Recent Developments: Partnerships and Product Innovations
Recent industry moves show a focus on ecosystem expansion. Major announcements include OneAccord Health LLC strengthening its clinical partnership network and Tulip Cremation enhancing its digital end-of-life planning suite. Companies are increasingly launching Mobile Apps For Advance Directives to capture the younger demographic, signaling a strategic effort to normalize end-of-life planning much earlier in the patient lifecycle.