Market Overview: Defining the Amorphous Polypropylene Terephthalate landscape
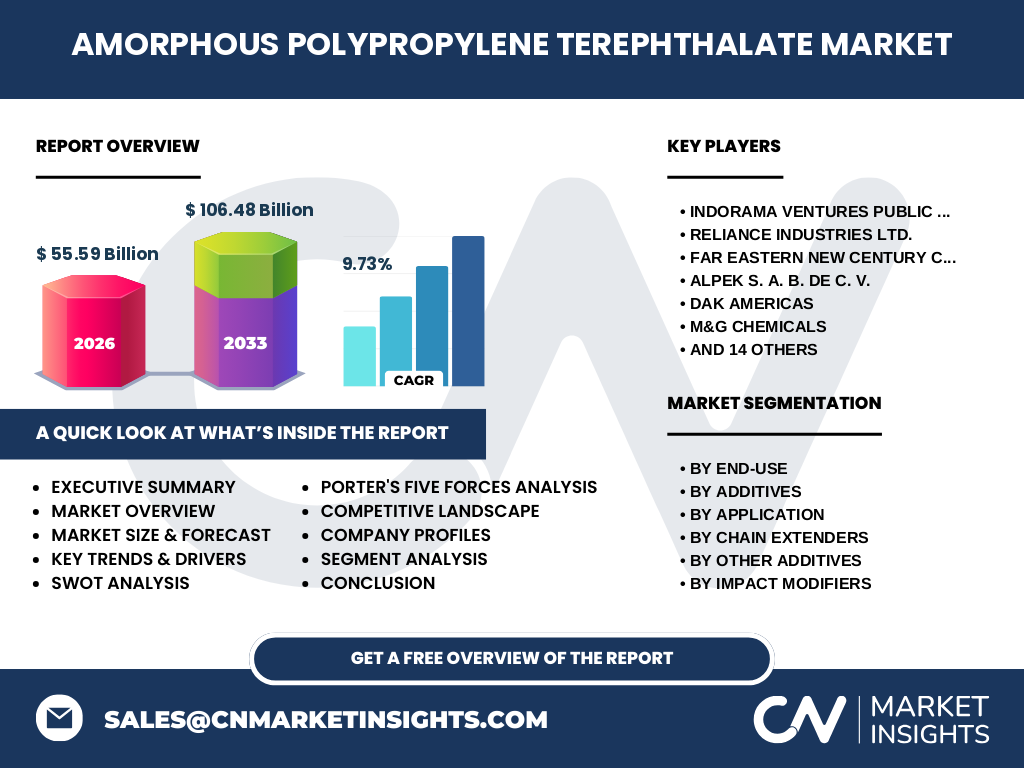
The Amorphous Polypropylene Terephthalate Market encompasses the production and distribution of non-crystalline PET resins essential for clarity-demanding applications. With a 2026 market size of 55.59 Billion, this sector serves as the backbone for global food packaging and pharmaceutical logistics, prioritizing high transparency and barrier efficiency over the thermal stability found in semi-crystalline variants.
Structural Growth Drivers and Market Constraints
Growth is propelled by surging consumer demand for high-barrier food packaging and rigid films. However, industry stakeholders face stringent regulatory pressures from bodies like the FDA and EFSA regarding recyclability. The primary challenge involves balancing cost-efficient processing with the rising energy costs associated with raw material synthesis in major manufacturing hubs.
Emerging Trends in the Amorphous Polypropylene Terephthalate Market
The industry is shifting toward advanced additive integration to enhance physical performance without compromising clarity. We observe a trend of using specialized chain extenders to improve rheological properties. Companies are increasingly prioritizing circular economy initiatives, integrating post-consumer recycled content into their amorphous portfolios to align with evolving international sustainability mandates and corporate ESG targets.
COVID-19 Impact and Recovery Analysis
The pandemic acted as a bifurcated catalyst for the market. While supply chain disruptions hampered raw material procurement from major ports, demand for hygienic pharmaceutical packaging and single-serve food containers spiked. Post-pandemic recovery has been robust, characterized by a 9.73% CAGR as regional packaging infrastructures modernized to address long-term shifts in consumer delivery and sterilization requirements.
Competitive Benchmarking and Strategic Dynamics
The landscape is highly consolidated, dominated by titans like Indorama Ventures and Reliance Industries Ltd. These players utilize massive scale to maintain pricing power. Smaller, specialized firms like Ester Industries leverage technical agility to provide tailored additive solutions. Competitive success is currently defined by vertical integration, ensuring a steady flow of monomer feedstocks despite volatile crude oil markets.
Executive Summary: Key Findings
The Amorphous Polypropylene Terephthalate Market is positioned for explosive growth, projected to reach 106.48 Billion by 2033. Our research indicates that the synergy between innovative chemical additives and the expansion of the pharmaceutical packaging sector will sustain a strong 9.73% CAGR. Strategic investors should focus on companies with high proprietary technology portfolios and robust regional supply chain presence.
Market Forecast: 2027 to 2033 Projections
Our analysis projects the total addressable market to climb from its 2026 baseline to 106.48 Billion by 2033. This trajectory reflects a steady 9.73% annual growth rate. The forecast is underpinned by anticipated capacity expansions from Zhejiang Zhink Group and Jiangsu Sanfangxiang, which are critical to meeting the escalating structural demand within the Asian and Western packaging corridors.
Segmentation Analysis: Breaking Down the Industry
Market segmentation focuses on three core dimensions: End-Use, Additives, and Applications. The Food & Beverages segment currently leads in volume, while the Pharmaceuticals category exhibits the highest profit margins. Additive segments—specifically chain extenders and impact modifiers—are experiencing higher growth, as manufacturers differentiate their offerings to meet specific shelf-life requirements for sensitive medical products.
Regional Market Distribution Performance
Regional performance is anchored by Asia-Pacific's manufacturing dominance, led by LOTTE Chemical and Toray Industries. North America and Europe remain high-value regions focused on premium, eco-compliant resin formulations. Trade registry data highlights a significant shift in logistics, with regional hubs in Saudi Arabia (SABIC) becoming pivotal to supply chains for the EMEA market, countering raw material scarcity in traditional centers.
In-depth Regional Review: Key Geographic Focus
The Asian market remains the volume engine, driven by the massive production footprint of Far Eastern New Century Corporation. Conversely, European markets dictate the pace of innovation for barrier-enhancing additives due to strict plastic waste directives. Our research indicates that localized manufacturing in Latin America and MEA is slowly reducing dependency on transcontinental shipments of virgin resins.
Company Profiles and Strategic Positioning
Leaders like Alpek S.A.B. de C.V. and DAK Americas maintain a strategic edge through aggressive acquisition of regional processing assets. SK Chemicals distinguishes itself through sustainable resin alternatives. These firms are moving beyond commodity-grade production, investing heavily in R&D for specialized antioxidants and UV stabilizers, positioning themselves as high-value partners for global food conglomerates and medical device original equipment manufacturers.
Porter’s Five Forces Assessment
The market demonstrates moderate-to-high intensity. Supplier power is concentrated in large-scale petrochemical feedstock providers, while buyer power remains high among multinational food brands. Threat of substitution is mitigated by the unmatched clarity of amorphous PET. Entry barriers are significant, requiring massive capital expenditure, which prevents widespread disruption from smaller, emerging market players in the short-to-medium term.
SWOT Analysis of the Industry
Strengths: Massive, established infrastructure. Weaknesses: High dependence on oil-linked feedstocks. Opportunities: Rapid expansion in pharmaceutical and specialized medical packaging applications. Threats: Increasing regulatory scrutiny on non-recyclable materials in major EU and North American jurisdictions. These factors necessitate a strategic pivot toward advanced, circular additive technologies to maintain a competitive advantage.
Value Chain Analysis
The value flow begins with monomer synthesis (PTA/MEG) by conglomerates like Reliance Industries, moving through intermediate resin polymerization, and ending with converter-level extrusion. Value-add occurs during additive compounding—where impact modifiers and colorants are introduced. The downstream reach extends to major retailers and healthcare providers, where the Amorphous Polypropylene Terephthalate market's final, shelf-ready packaging solutions are ultimately realized.
Investment Insights and Strategic Recommendations
Investors should prioritize companies investing in circularity-enabling additives and efficient catalysis. With the market set to reach 106.48 Billion, the highest-potential areas reside in the pharmaceutical-grade resin segment, which remains less sensitive to commodity pricing fluctuations. We advise caution regarding entities with high exposure to regions lacking robust recycling infrastructure, as regulatory headwinds are expected to intensify.
Conclusion and Key Takeaways
The Amorphous Polypropylene Terephthalate Market is defined by its resilience and technical evolution. Reaching 106.48 Billion by 2033, the industry demonstrates a strong 9.73% CAGR. Success requires a dual focus on operational scale and specialized additive innovation. Firms that proactively adopt sustainable, compliant manufacturing processes will likely dominate the next decade of market expansion, leveraging their strategic position to navigate supply chain complexities.
Research Methodology: How we triangulate data
Our estimates are triangulated using multi-source data ingestion. We combine proprietary trade registry data tracking raw material flows with primary stakeholder interviews involving CEOs and lead engineers at firms like Polyplex Corporation. Macroeconomic indicators from trade bodies and GDP-correlated consumption models are cross-referenced to ensure that our 9.73% CAGR and 106.48 Billion forecast remain highly accurate and industry-representative.
Scope of the Report: Parameters and Limitations
This report examines the global supply and demand dynamics of Amorphous Polypropylene Terephthalate, covering 2026-2033. It spans major end-uses and additive types but excludes specialized copolyesters outside the core PET scope. Our analysis assumes stable international trade relations; sudden shifts in geopolitical trade barriers or major environmental regulatory bans could influence the projected market trajectories and regional performance benchmarks.
Recent Developments in the Industry
Key strategic moves include Polygenta Technologies and Zhejiang Zhink Group advancing their recycled-content resin pipelines. Recent product launches focus on high-performance antioxidants and heat stabilizers that reduce material degradation. These partnerships between resin producers and chemical additive specialists are designed to meet the technical requirements of high-speed packaging lines, effectively boosting efficiency for end-users across the global food and beverage landscape.