Executive Summary of the Salt Market
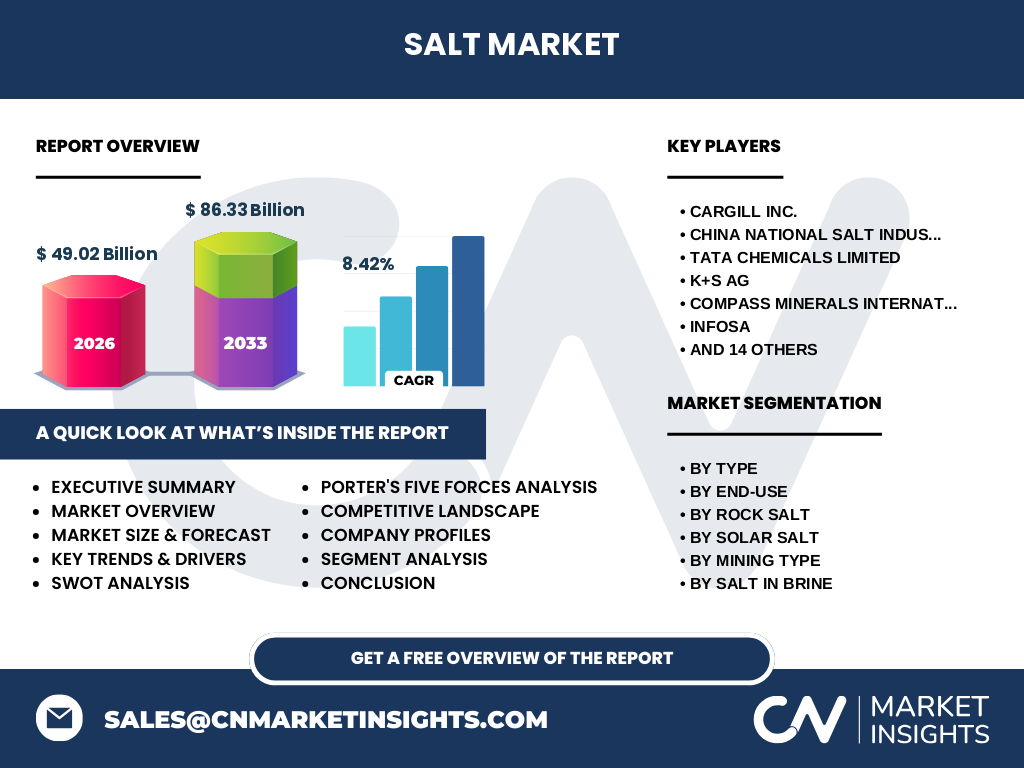
Our analysis indicates that the Salt Market is poised for exceptional expansion, surging from a valuation of 49.02 Billion in 2026 to reach 86.33 Billion by 2033. Driven by a robust compound annual growth rate of 8.42%, this trajectory underscores critical shifts across chemical processing, industrial de-icing, and food manufacturing applications worldwide.
What defines the scope and industry significance of the Salt Market?
The Salt Market encompasses the extraction, refinement, and distribution of sodium chloride essential for industrial and consumer applications. Governed by stringent quality standards enforced by agencies like the FDA and the EPA, this sector underpins global chemical synthesis, water softening infrastructure, and cold-weather municipal logistics managed by major transport authorities.
Structural Growth Drivers and Market Restraints
Growth is propelled by surging demand in chlor-alkali manufacturing and municipal de-icing requirements. Conversely, logistical bottlenecks in maritime transport, stringent environmental regulations on brine discharge, and volatile energy costs for vacuum pan evaporation act as primary market restraints, challenging profit margins for producers.
Emerging Trends and Growth Patterns in the Industry
The industry is witnessing an accelerated shift toward high-purity vacuum pan salt and automated underground mining techniques. Producers are optimizing supply chains to reduce carbon footprints, aligning with sustainability mandates while capitalizing on rising chemical feedstock demands across developing economies.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic caused temporary supply chain disruptions and labor shortages in underground and surface mining operations. However, resilient demand from the pharmaceutical and food processing sectors catalyzed a rapid V-shaped recovery, stabilizing operational throughput across major global saltworks.
Competitive Benchmarking and Market Concentration
The Salt Market exhibits a moderately consolidated structure dominated by multinational giants like Cargill Inc., Tata Chemicals Limited, and K+S AG. These industry leaders leverage proprietary extraction technologies and extensive logistical networks to maintain pricing power, while regional players serve specialized local demands.
Market Forecast for the Salt Industry (2027-2033)
Projected to scale dramatically, the market will expand from its 2026 baseline to 86.33 Billion by 2033 at a 8.42% CAGR. This accelerated forecast reflects heightened industrialization, rising chemical feedstock requirements, and expanding infrastructure for winter road safety globally.
Segmentation Analysis of the Salt Market
Market segmentation spans multiple categories:
- By Type: Rock Salt, Salt In Brine, Solar Salt, Vacuum Pan Salt
- By End-Use: Food Industry, Chemical Industry, Water Treatment And De-icing, Agriculture, Pharmaceuticals
- By Mining Type: Underground Mining, Surface Mining
Geographic Distribution and Regional Market Performance
Regional performance varies significantly based on industrial density and climatic conditions. North America and Europe dominate de-icing consumption due to harsh winters, whereas Asia-Pacific leads chemical and industrial consumption, driven by rapid manufacturing expansion in emerging economies.
In-Depth Regional Review
North American operations heavily rely on rock salt mining in geological basins, supported by efficient inland waterways and rail logistics. In contrast, Asia-Pacific markets heavily leverage solar evaporation ponds along coastal regions to meet booming domestic chemical manufacturing demands.
Strategic Positioning of Leading Companies
Industry titans like Morton Salt Inc. and Compass Minerals International Inc. focus on optimized logistical integration for de-icing salt, whereas specialized entities like Dead Sea Works Ltd. and Salinen Austria AG capitalize on unique mineral compositions for pharmaceutical and specialty chemical applications.
Porter's Five Forces Analysis of the Salt Market
Bargaining power of buyers remains moderate due to standardized product offerings, while supplier power is low given abundant geological reserves. However, the threat of substitutes is negligible, and competitive rivalry is intense among established global conglomerates.
SWOT Analysis of the Industry
Strengths include vast mineral reserves and essential end-use demand. Weaknesses involve high freight-to-value ratios. Opportunities lie in high-purity vacuum pan salt for pharmaceuticals, while threats include stringent environmental regulations governing discharge and mining rights.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with geological extraction via underground mining or solar evaporation. It progresses through chemical purification and crystallization, followed by bulk transport via maritime vessels and rail networks to industrial end-users and consumer packaging facilities.
Investment Insights and High-Potential Areas
Investors should target high-purity vacuum pan salt production facilities and sustainable solar salt operations. Companies investing in automated underground mining and eco-friendly brine management systems present superior long-term growth potential within this multi-billion dollar sector.
Conclusion and Key Takeaways
The Salt Market represents a stable yet high-growth ecosystem anchored by essential industrial needs. Reaching 86.33 Billion by 2033, success in this sector hinges on logistical efficiency, environmental compliance, and technological modernization in extraction.
Research Methodology
Our baseline estimates are rigorously triangulated by combining international trade registry data, primary stakeholder interviews with executives from China National Salt Industry Corporation and K+S AG, and secondary macroeconomic indicators from global industrial bodies.
Scope of the Report
This report evaluates the global Salt Market across historical data, current estimations, and a strict forecast window through 2033. It covers all major product types, mining methods, and regional jurisdictions, excluding unauthorized gray-market trade channels.
Recent Industry Developments and Strategic Moves
Recent developments feature major infrastructure investments by Schweizer Salinen AG in eco-friendly refining technologies and strategic supply agreements forged by Tata Chemicals Limited to secure long-term chemical industry feedstock contracts across international markets.