What is the scope and industry significance of the Base Oil Market?
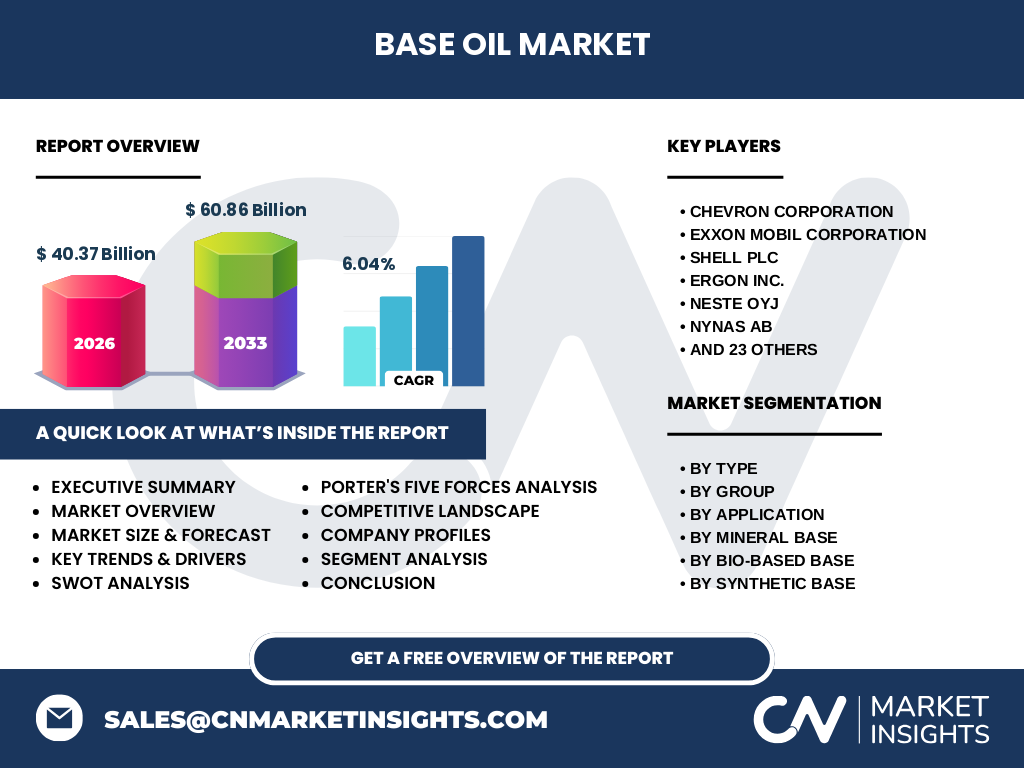
The Base Oil Market represents the foundational pillar of the global lubricants industry, serving as the essential fluid medium for automotive and industrial machinery. Valued at $40.37 Billion in 2026, this sector underpins tribological efficiency worldwide, relying on complex refining streams from key players like ExxonMobil and Shell PLC to prevent catastrophic mechanical friction.
What are the key market drivers, restraints, challenges, and opportunities shaping the Base Oil Market?
Industrial automation and stringent OEM specifications act as primary structural catalysts, while fluctuating vacuum gas oil feedstock costs restrain margin expansion. Logistics bottlenecks in key blending hubs present persistent hurdles. Conversely, rising demand for high-performance synthetic lubricants creates lucrative expansion opportunities for refiners capable of advanced hydrocracking.
Emerging trends and growth patterns in the Base Oil Market
The industry is experiencing a pronounced shift toward ultra-low viscosity Group III and Group IV polyalphaolefins to meet aggressive fuel economy standards. Refiners are increasingly investing in proprietary wax isomerization technologies to upgrade traditional paraffinic streams into premium-tier stocks demanded by electric vehicle thermal management systems.
COVID-19 impact analysis and recovery trajectory
Pandemic-induced lockdowns severely disrupted automotive production and industrial manufacturing, causing a sharp contraction in lubricant consumption. The subsequent recovery trajectory has been shaped by V-shaped demand rebounds in Asia-Pacific and supply chain realignments, forcing operators to optimize capacity utilization across major hydroprocessing units.
Competitive benchmarking and strategic dynamics
Market concentration remains moderately high, dominated by integrated energy titans like Chevron Corporation, Saudi Aramco, and SK Lubricants. These industry leaders leverage feedstock integration and proprietary catalytic dewaxing to defend market share against nimble independent blenders navigating tightening environmental mandates.
Executive summary of the Base Oil Market report
Our analysis indicates that the global Base Oil Market is poised for robust expansion, scaling from $40.37 Billion in 2026 to $60.86 Billion by 2033 at a CAGR of 6.04%. This trajectory is propelled by accelerating industrialization and rigorous efficiency standards across emerging economies.
Market forecast from 2027 to 2033
Projected to achieve a solid 6.04% CAGR, the market will surge from its 2026 baseline to reach $60.86 Billion by 2033. This accelerated growth phase reflects sustained demand for high-viscosity index synthetic stocks in advanced industrial applications and stringent passenger car engine oils.
Segmentation analysis across product categories
The market bifurcates across multiple dimensions: by Type (Mineral, Synthetic, Bio-Based), Group (I through V), Application (Automotive, Industrial, Metalworking, Greases, Hydraulic), Mineral Base (Paraffinic, Naphthenic, Aromatic), Bio-Based (Vegetable, Animal, Bio-Synthetic), and Synthetic Base (PAO, Esters, Group III). Each category dictates distinct blending economics and performance thresholds.
Regional market analysis and geographic distribution
Geographic performance highlights Asia-Pacific as the undisputed consumption epicenter, driven by massive manufacturing output in China and India. Meanwhile, North America and Europe prioritize high-margin synthetic formulations, governed by stringent environmental regulations from agencies like the EPA and REACH compliance frameworks.
In-depth regional review of high-growth territories
Asia-Pacific dominates volumetric demand due to rapid automotive fleet expansion and heavy industrial build-out. In contrast, the Middle East leverages abundant crude reserves and state-of-the-art refining complexes operated by entities like Abu Dhabi National Oil Company to export high-quality Group II and III base stocks globally.
Company profiles and strategic positioning
Industry heavyweights such as TotalEnergies, PETRONAS Lubricants, and Petro-Canada utilize vertically integrated supply chains to secure base stock margins. Specialized players like Nynas AB focus intensely on naphthenic specialties, carving out high-barrier niches in electrical transformer oils and low-temperature process fluids.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to abundant crude oil availability, whereas buyer power is high among major automotive OEMs demanding custom fluid specifications. Threat of substitution is rising via bio-based alternatives, while high capital expenditure requirements for hydrocrackers keep the threat of new entrants relatively low.
SWOT analysis of the Base Oil Industry
Strengths lie in robust supply chain integration and advanced hydroprocessing tech. Weaknesses involve high carbon intensity in traditional refining. Opportunities abound in electric vehicle drivetrain fluids, while threats stem from aggressive carbon-neutrality mandates and fluctuating crude feedstock prices.
Value chain analysis from raw materials to end-users
The value chain originates with crude oil extraction and vacuum distillation, proceeding through solvent extraction or catalytic hydrocracking into base oil refineries. Independent and integrated blenders then formulate finished lubricants with specialized additive packages before distribution to automotive and industrial end-users.
Investment insights and high-potential areas
Strategic capital should target hydrocracking capacity expansions for Group III and IV synthetic base oils, where margins significantly outpace commoditized Group I slates. Investors should prioritize partnerships with technology innovators developing sustainable, biodegradable bio-synthetic base stocks.
Conclusion and key takeaways
The transition toward high-performance synthetic and bio-based stocks defines the future trajectory of the sector. Companies that proactively decarbonize refining assets and align product portfolios with OEM efficiency trends will capture outsized value through 2033.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, customs import-export logs, primary stakeholder interviews with refinery executives, and secondary macroeconomic indicators from international energy agencies to ensure unmatched analytical accuracy.
Scope of the report and coverage parameters
This report encompasses a comprehensive global assessment of the base oil sector, evaluating historical trends from 2020 alongside forecasts through 2033. Coverage parameters incorporate volumetric consumption data, pricing volatility metrics, and regulatory impacts across all major geographic jurisdictions.
Recent developments in the market
Recent strategic moves feature major capacity expansions by producers like SK Lubricants and joint ventures focused on sustainable base stock production. Leading refiners are actively investing in proprietary hydroisomerization units to meet tightening global specifications for low-sulfur industrial and automotive lubricants.