What is the scope and industry significance of the Nuclear Inspection Service Market?
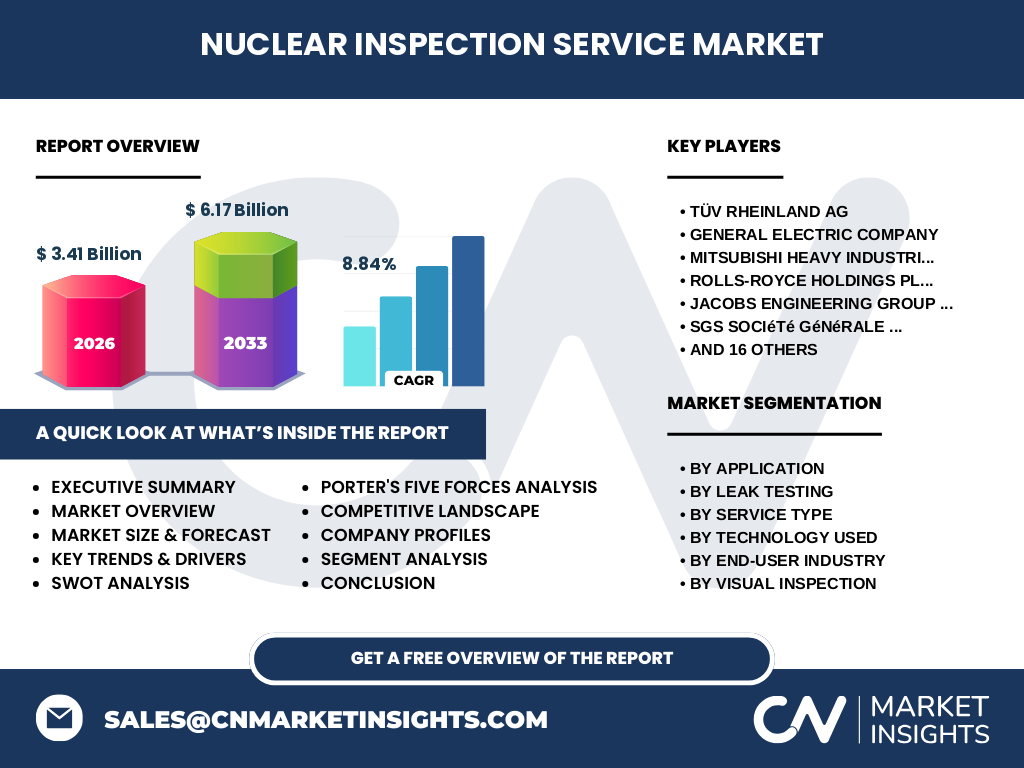
Our analysis indicates that the Nuclear Inspection Service Market is valued at $3.41 Billion in 2026, playing a critical role in ensuring structural integrity across global energy infrastructure. Operating under strict oversight from the Nuclear Regulatory Commission Regulations and the International Atomic Energy Agency Standards, these specialized verification protocols safeguard high-stakes assets like nuclear power plants and research reactors.
Structural Growth Drivers and Market Restraints
The sector benefits from rising global energy demands and life-extension programs for aging infrastructure. Based on our research, the market faces significant restraints, including stringent compliance protocols governed by the Environmental Protection Agency Guidelines and high capital expenditures required for advanced diagnostic platforms like Robotic Inspection Systems and Artificial Intelligence and Machine Learning.
The Shift Toward Advanced Non-Destructive Testing and Digital Integration
Industry participants are rapidly adopting Non-Destructive Testing (NDT) methodologies such as Phased Array Ultrasonic Testing (PAUT) and Digital Radiography. This shift minimizes radiation exposure for personnel while maximizing defect detection accuracy in primary coolant loops and fuel fabrication assemblies, significantly reducing costly operational downtime for energy producers.
How did the COVID-19 pandemic impact operational continuity and recovery trajectories?
The pandemic severely disrupted scheduled refueling outages and mandatory containment inspections due to travel restrictions and labor shortages. However, the data suggests a robust recovery, accelerated by the deployment of Drones and Unmanned Aerial Vehicles and Remote Visual Inspection (RVI) technologies, which allowed operators to maintain compliance with American Society For Testing And Materials standards remotely.
Competitive Benchmarking and Strategic Dynamics
Market concentration is high, featuring global service providers and engineering conglomerates. Key players like TÜV Rheinland AG, Framatome SAS, and Westinghouse Electric Company LLC leverage proprietary testing technologies to secure long-term service contracts with nuclear energy producers, driving consolidation through strategic acquisitions of specialized NDT firms.
Executive Summary of Valuation and Strategic Outlook
A high-level synthesis of our proprietary research reveals a fast-expanding sector projected to reach $6.17 Billion by 2033, expanding at a robust CAGR of 8.84%. This growth is underpinned by stringent safety mandates from organizations like the International Organization For Standardization Standards and technological leaps in automated defect evaluation.
Long-Term Market Forecast from 2027 to 2033
Our forecasting models show continuous, accelerated expansion as the baseline valuation scales from the 2026 baseline toward the $6.17 Billion mark by 2033. This trajectory is sustained by a steady 8.84% CAGR, driven by the global renaissance of nuclear energy and mandatory periodic safety reviews for plants nearing their initial design life.
Segmentation Analysis Across Applications, Technologies, and Testing Methods
The market is segmented by application into nuclear power plants, research reactors, and fuel fabrication facilities. Service-type breakdowns highlight Non-Destructive Testing (NDT), visual inspection, and radiographic testing, while leak testing relies on techniques like Helium Mass Spectrometry and Ultrasonic Leak Detection to ensure containment integrity.
Geographic Distribution and Regional Performance Overview
Regional performance varies based on national energy policies and the density of operational reactors. North America and Europe hold dominant revenue shares due to established regulatory frameworks from the Nuclear Regulatory Commission Regulations, whereas the Asia-Pacific region exhibits the fastest growth driven by aggressive reactor construction programs.
In-Depth Regional Review of Nuclear Infrastructure Markets
Regional analysis highlights North America as a mature market focused on plant life extensions, supported by inspection specialists such as Acuren Inspection Inc. and Mistras Group Inc. Meanwhile, Asia-Pacific represents a high-growth frontier driven by new builds in emerging economies, requiring advanced Ultrasonic Testing and robotic deployment.
Company Profiles and Strategic Positioning of Industry Leaders
Leading entities utilize distinct strategic advantages. Firms like Rolls‑Royce Holdings plc and Mitsubishi Heavy Industries Ltd. combine engineering prowess with in-house inspection capabilities. Meanwhile, specialized technological innovators like Eddyfi Technologies Inc. and Zetec Inc. supply cutting-edge probes and software to service providers such as SGS Société Générale de Surveillance S.A. and Bureau Veritas S.A.
Porter's Five Forces Analysis of the Inspection Sector
Supplier power is moderate, balanced by specialized technology developers and heavy regulatory certification requirements. Buyer power remains low due to the critical, mission-critical nature of nuclear safety. Threat of substitution is minimal, as regulatory bodies strictly mandate certified NDT and leak testing protocols like Bubble Testing and Magnetic Particle Testing.
SWOT Analysis of the Nuclear Inspection Service Ecosystem
Strengths include high technical barriers to entry and deep regulatory expertise. Weaknesses involve high training costs and equipment obsolescence risks. Opportunities lie in artificial intelligence integration and small modular reactor deployments. Threats stem from geopolitical disruptions impacting specialized raw material supply chains for testing probes.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material suppliers providing specialized alloys for testing equipment, flowing through hardware and software developers like Nucleom and FORCE Technology Foundation. Service providers execute inspections on-site, delivering actionable integrity data to end-users such as government regulatory bodies and nuclear energy producers.
Investment Insights and High-Potential Growth Areas
Strategic recommendations emphasize capital allocation toward autonomous robotics and Artificial Intelligence and Machine Learning software for automated defect recognition. Investors should target niche technological innovators capable of reducing human error during high-radiation containment vessel evaluations, yielding superior long-term ROI.
Conclusion and Strategic Takeaways for Market Stakeholders
The data confirms that mastering advanced digital inspection modalities is essential for capturing market share through 2033. Stakeholders must align their service portfolios with stringent international standards to secure lucrative maintenance contracts across global nuclear fleets, ensuring compliance and operational longevity.
Research Methodology and Baseline Triangulation Techniques
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-suite executives, secondary macroeconomic indicators, trade registry data, and regulatory filing analysis from bodies like the International Atomic Energy Agency Standards to ensure absolute data fidelity.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for nuclear inspection services through 2033, analyzing specific segments including leak testing, non-destructive testing, visual inspection, and compliance frameworks. Limitations exclude conventional fossil-fuel power generation assets, maintaining strict focus on the nuclear sector.
Recent Developments, Partnerships, and Strategic Corporate Moves
Recent market activities feature key partnerships between inspection leaders and plant operators to deploy real-time monitoring arrays. Notable moves by firms such as Kinectrics Inc., Applus+, and ENGIE Laborelec highlight a concerted industry push toward integrating AI-driven analytics into legacy inspection workflows.