What is the scope and industry significance of the Mechanical Pipettes Market?
Our analysis indicates that the Mechanical Pipettes Market represents a foundational pillar for life sciences, clinical diagnostics, and analytical chemistry. Valued at 1.61 Billion in 2026, this sector encompasses essential liquid handling instruments crafted from advanced engineering plastics, PVDF, and chemically resistant fluoroelastomers. These precision tools ensure repeatable volumetric accuracy across pharmaceutical research and high-throughput screening laboratories worldwide.
Structural Growth Drivers and Market Restraints
The market is propelled by expanding pharmaceutical R&D pipelines and rising demand for precise micro-volume dispensing in genomics and proteomics. However, strict calibration standards enforced by ISO 8655 and persistent supply chain bottlenecks for medical-grade raw materials act as operational restraints. Stringent sterilization protocols and contamination control requirements further compel laboratories to upgrade their liquid handling arsenals continually.
Emerging Trends Reshaping Laboratory Workflows
Laboratories increasingly prioritize ergonomics to mitigate repetitive strain injuries among technicians, driving demand for lightweight chassis designs and low-force plunger mechanisms. Adjustable-spacing multi-channel mechanical pipettes are gaining traction as researchers transition samples rapidly between microplates, PCR strips, and gel electrophoresis chambers without risking cross-contamination or alignment errors.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic triggered an unprecedented surge in demand for diagnostic testing kits, accelerating procurement cycles for single-channel and multi-channel mechanical pipettes across clinical reference labs. While global supply chain disruptions initially strained component sourcing, post-pandemic stabilization has cemented robust inventory reserves. Diagnostic laboratories now maintain higher baseline equipment redundancies to withstand future biological contingencies.
Competitive Benchmarking and Industry Concentration
The market features intense rivalry among established multinationals and specialized liquid-handling innovators. Dominant players leverage proprietary tip-fitting technologies and global distribution networks to secure institutional contracts. Companies such as Eppendorf AG and Gilson Inc. focus heavily on ergonomic precision engineering, whereas agile competitors like Microlit Industries Private Limited compete effectively through cost-optimized manufacturing.
Executive Summary of the Mechanical Pipettes Market
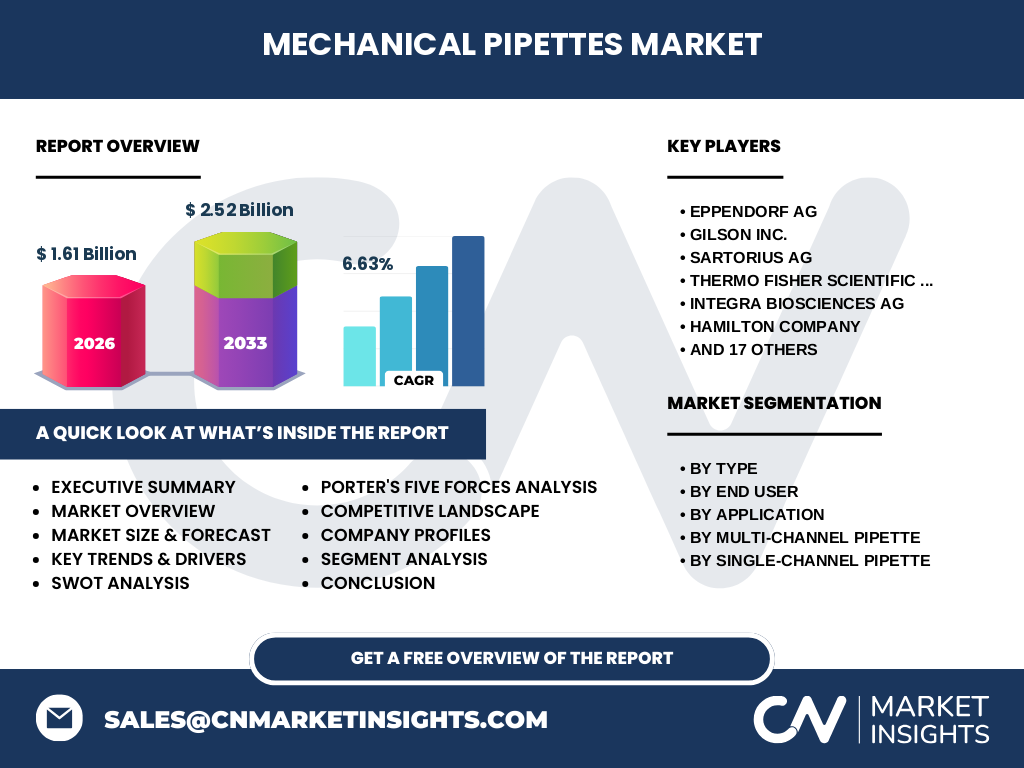
Our research forecasts the Mechanical Pipettes Market to expand from 1.61 Billion in 2026 to 2.52 Billion by 2033, achieving a robust 6.63% CAGR. Driven by biotechnology breakthroughs and stringent clinical diagnostic demands, the sector demonstrates remarkable resilience. Strategic investments in ergonomic designs and high-channel-count configurations will capture disproportionate market share during the forecast window.
Market Forecast and Long-Term Trajectory (2027 to 2033)
Based on our econometric modeling, the market is projected to scale from its 2026 baseline of 1.61 Billion to reach 2.52 Billion by 2033, expanding at a steady 6.63% CAGR. This trajectory reflects sustained capital expenditure within academic research institutes and contract research organizations seeking high-durability liquid handling solutions that minimize calibration drift.
Segmentation Analysis Across Product and End-User Categories
Categorized by type, the market includes Single-Channel Pipette and Multi-Channel Pipette variants, with single-channel models further divided into Fixed Volume Pipettes and Variable Volume Pipettes. End-user verticals span Academic And Research Institutes, Pharmaceutical And Biotechnology Companies, Clinical And Diagnostic Laboratories, Contract Research Organizations And Contract Manufacturing Organizations, Industrial And Food Testing Laboratories, and Private And Independent Laboratories.
Regional Market Distribution and Geographic Performance
Geographic performance highlights North America and Europe as dominant revenue contributors, anchored by dense clusters of biopharmaceutical headquarters and well-funded academic research centers. Meanwhile, the Asia-Pacific region exhibits the fastest growth velocity, propelled by surging biotechnology investments in emerging economies, expanding clinical testing infrastructure, and favorable contract research outsourcing trends.
In-Depth Regional Review of Key Markets
North America maintains leadership due to early adoption of advanced liquid handling systems and rigorous regulatory compliance mandates enforced by the FDA. In contrast, Asia-Pacific growth is propelled by rapidly expanding life science hubs in regional manufacturing centers, where local laboratories increasingly demand high-durability, cost-effective variable volume instruments to support domestic diagnostic scaling.
Strategic Positioning of Leading Companies
Industry leaders like Thermo Fisher Scientific Inc., Sartorius AG, and Mettler Toledo International Inc. anchor their strategies in comprehensive product ecosystems combining pipettes, tips, and calibration services. Specialty players such as Integra Biosciences AG and Hamilton Company carve out high-margin niches through specialized electronic-assist mechanical hybrids and high-throughput liquid handling modules.
Porter's Five Forces Assessment of Competitive Pressures
The threat of new entrants remains moderate due to high capital requirements for precision mold tooling and stringent ISO calibration compliance. Bargaining power of buyers is tempered by the critical need for absolute volumetric accuracy in diagnostics, making laboratories reluctant to compromise on established brands. Competitive rivalry among incumbent manufacturers remains exceptionally fierce.
SWOT Analysis of the Mechanical Pipettes Industry
Key strengths include established brand loyalty, exceptional mechanical durability, and widespread clinical adoption. Weaknesses center on vulnerability to counterfeit pipette tips and susceptibility to calibration drift under harsh chemical exposure. Opportunities lie in emerging biotech hubs across developing nations, while threats involve potential supply chain shocks impacting high-grade polymer procurement.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with the sourcing of medical-grade polymers, stainless steel, and specialized O-rings from certified chemical suppliers. Precision injection molding and assembly occur in controlled cleanroom facilities before rigorous calibration testing against ISO standards. Finished goods flow through specialized scientific distributors directly to biopharmaceutical companies, diagnostic labs, and academic research institutions.
Investment Insights and High-Potential Growth Areas
Investors should target manufacturers specializing in High-Channel-Count Mechanical Pipettes (Above 16 Channels) and Adjustable-Spacing Multi-Channel Mechanical Pipettes, as these segments address the surging demand for high-throughput genomic screening. Companies integrating sustainable, autoclavable materials will capture significant preference among environmentally conscious institutional buyers.
Conclusion and Strategic Takeaways
The Mechanical Pipettes Market demonstrates solid fundamentals, underpinned by a projected expansion from 1.61 Billion in 2026 to 2.52 Billion by 2033 at a 6.63% CAGR. Manufacturers that successfully balance ergonomic innovation, strict regulatory compliance, and multi-channel versatility will secure long-term market dominance across global life science ecosystems.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with laboratory managers, and secondary macroeconomic indicators from global health organizations. This multi-tiered analytical approach reconciles manufacturer shipment volumes with regional procurement budgets to ensure high-fidelity market sizing.
Scope of the Report and Coverage Parameters
This report evaluates the global Mechanical Pipettes Market across specific product types, applications including Biological and Chemical, and diverse end-user verticals. The analysis covers historical pricing trends from preceding years, current baseline valuations for 2026, and forecast projections through 2033, excluding fully automated robotic liquid handling workstations.
Recent Developments, Partnerships, and Product Launches
Recent industry momentum highlights strategic portfolio expansions by major participants such as Corning Incorporated and Brand Gmbh + Co Kg, focusing on lightweight, fatigue-reducing pipetting platforms. Furthermore, collaborations between established instrument manufacturers and regional biotech distributors have optimized supply chain responsiveness across emerging APAC markets.