What is the scope and industry significance of the Retail Self Service Kiosk Market?
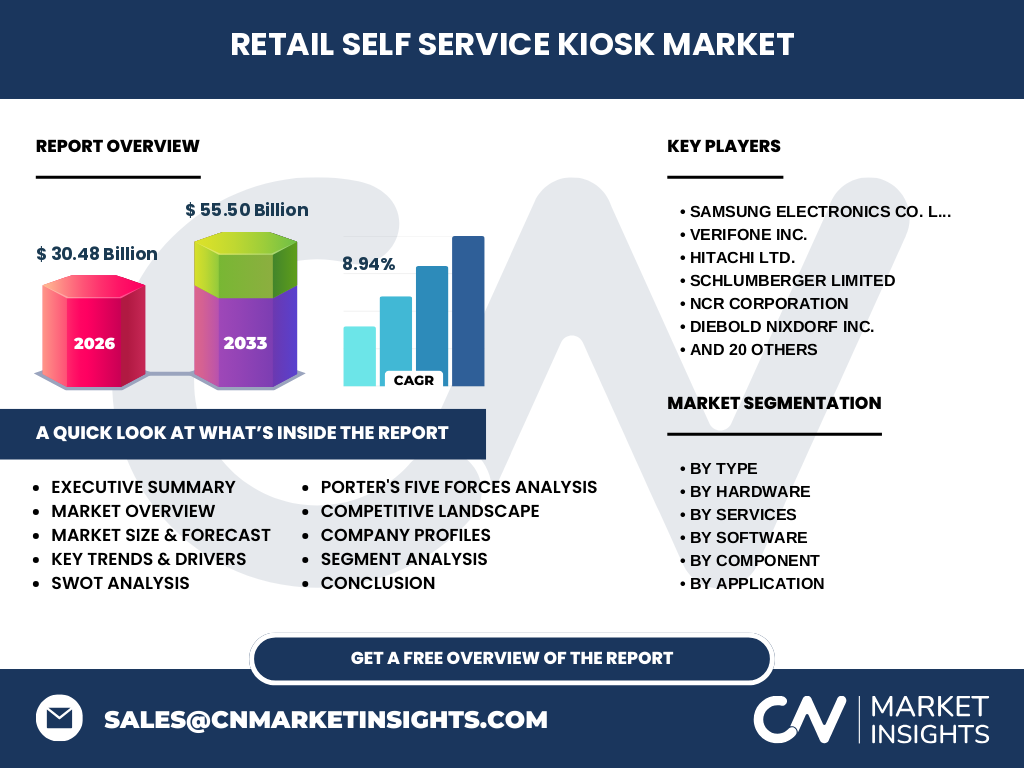
Our analysis indicates that the Retail Self Service Kiosk Market represents a transformative commercial sector valued at $30.48 Billion in 2026. This market encompasses interactive hardware, specialized software, and lifecycle services deployed across physical retail environments to streamline consumer transactions. It is critical for modern omnichannel retail strategies, drastically reducing labor overhead while enhancing consumer autonomy.
Key market drivers, restraints, challenges, and opportunities shaping the Retail Self Service Kiosk Market
The primary catalyst is rising consumer demand for friction-free checkouts, countered by high initial deployment costs for robust kiosk enclosures and payment modules. Supply chain bottlenecks involving semiconductor components for touchscreens pose ongoing logistical hurdles. However, significant opportunities exist in integrating advanced biometric authentication and AI-driven personalized advertising within convenience and supermarket applications.
Emerging trends and growth patterns in the Retail Self Service Kiosk Market
The shift toward contactless, hygienic interfaces dominates current industry dynamics. Our research highlights rapid adoption of modular hardware designs featuring advanced payment software and security protocols. Retailers increasingly prioritize cloud-managed operating systems that allow centralized fleet updates across geographically dispersed supermarket chains, minimizing costly on-site maintenance.
COVID-19 impact analysis and recovery trajectory
The pandemic served as an unprecedented inflection point, accelerating adoption as retailers sought touch-free, social-distanced transaction methods. While supply chain disruptions temporarily delayed hardware rollouts, post-pandemic recovery has been robust. Investments in antimicrobial touchscreen coatings and robust sanitization modules cemented self-service terminals as permanent fixtures in modern retail infrastructure.
Competitive landscape of the Retail Self Service Kiosk Market
The landscape features a mix of diversified technology giants and specialized hardware vendors. Industry leaders like NCR Corporation, Diebold Nixdorf Inc., and Samsung Electronics Co. Ltd. leverage massive manufacturing scale and global distribution networks. Meanwhile, specialized innovators like Olea Kiosks Inc. and Meridian Kiosks LLC compete successfully through highly customizable enclosure designs and agile software integration.
Executive summary of the Retail Self Service Kiosk Market research overview
Our comprehensive research confirms a thriving market trajectory, projecting expansion from $30.48 Billion in 2026 to $55.50 Billion by 2033 at a robust CAGR of 8.94%. Convenience stores and supermarkets represent primary revenue hotspots, driven by continuous hardware and software innovations that maximize throughput and optimize labor allocation.
Market forecast from 2027 to 2033
Based on our econometric models, the market will scale from its 2026 baseline to reach $55.50 Billion by 2033, expanding at a compound annual growth rate of 8.94%. This sustained momentum is underpinned by escalating deployment in emerging retail economies and continuous hardware refresh cycles for payment modules and high-durability touchscreens.
Segmentation analysis across types, hardware, services, software, components, and applications
Segmentation reveals distinct revenue pools: By Type covers Point of Interaction, Ticketing Kiosks, and Others; By Hardware includes Enclosures, Touchscreens, Printers, and Payment Modules; By Services encompasses Installation, Maintenance, Support, and Consulting; By Software features Operating Systems, User Interface, Payment, Management, and Security Software; By Component spans Hardware, Software, and Services; By Application focuses on Convenience stores and Supermarkets.
Regional market analysis and geographic performance
Geographic performance varies significantly due to labor costs, digital payment maturity, and regulatory frameworks. North America maintains a dominant market share due to early retail automation adoption, while Asia-Pacific exhibits the fastest growth velocity, fueled by rapid urbanization and the proliferation of cashierless convenience stores in metropolitan hubs.
In-depth regional review of the Retail Self Service Kiosk Market
North American growth is anchored by strict labor cost pressures, pushing major supermarket chains to deploy end-to-end self-checkout terminals. In Europe, adherence to stringent GDPR and data security standards dictates software architecture choices. Meanwhile, Asia-Pacific markets prioritize ultra-fast, QR-code-driven payment modules integrated seamlessly with local mobile wallet ecosystems.
Company profiles and strategic positioning of leading participants
Leading players deploy distinct competitive strategies. NCR Corporation and Diebold Nixdorf Inc. focus on end-to-end enterprise solutions for large supermarkets. Elo Touch Solutions Inc. and Pyramid Computer GmbH specialize in high-performance hardware components and modular kiosk enclosures, while software innovators ensure secure, compliant transaction flows.
Porter's Five Forces analysis of competitive intensity
Industry rivalry is intense, driven by numerous hardware vendors competing on price and modularity. Supplier power is moderate, concentrated among specialized touchscreen and printer manufacturers. Buyer power is high, as major supermarket chains demand customized enclosures and bespoke software integrations. Threat of substitution remains low due to the irreplaceable labor-saving value of self-service terminals.
SWOT analysis for the Retail Self Service Kiosk Market
Strengths include proven labor cost reduction and enhanced consumer transaction speed. Weaknesses involve high initial capital expenditure and hardware maintenance overhead. Opportunities lie in AI-powered cross-selling algorithms and biometric payment integration. Threats stem from cybersecurity vulnerabilities and potential supply chain disruptions impacting raw material acquisition for touchscreens.
Value chain analysis from raw materials to end-users
The value chain initiates with raw material suppliers providing silicon, aluminum, and glass for touchscreens and enclosures. Component manufacturers assemble payment modules, printers, and operating systems. System integrators like KIOSK Information Systems Inc. combine these elements before deploying them to convenience stores and supermarkets for end-user interaction.
Investment insights and high-potential strategic focus areas
Investors should target software providers specializing in cloud-based management systems and advanced security modules, as these yield high-margin, recurring SaaS revenues. Furthermore, backing agile hardware manufacturers capable of rapidly adapting enclosures to emerging biometric payment technologies offers significant upside potential across supermarket retail segments.
Conclusion and key takeaways for industry stakeholders
The data underscores a lucrative growth trajectory, advancing from $30.48 Billion in 2026 to $55.50 Billion by 2033. Stakeholders must prioritize software security, modular hardware adaptability, and seamless omnichannel integration to capture expanding market share across convenience and supermarket retail verticals.
Research methodology used to triangulate baseline estimates
Our baseline estimates are rigorously triangulated by combining proprietary trade registry data, primary qualitative interviews with C-level executives at firms like Frank Mayer and Associates Inc. and Redef Interactive Kiosks, and secondary macroeconomic indicators tracking retail automation expenditures globally.
Scope of the report and coverage parameters
This report covers global deployment trends, hardware configurations, software ecosystems, and service models within the retail sector. Limitations include excluding non-retail self-service applications such as airport check-in kiosks or medical check-in terminals, maintaining strict focus on convenience stores and supermarkets.
Recent developments, partnerships, and strategic moves in the industry
Recent market activity is characterized by strategic consolidation and technological upgrading. Major players are forging partnerships with fintech providers to embed biometric payment modules directly into kiosk software architectures, ensuring compliance with evolving financial security standards while enhancing the consumer checkout experience.