What is the market overview and industry significance of the Robotic Process Automation In Legal Service Market?
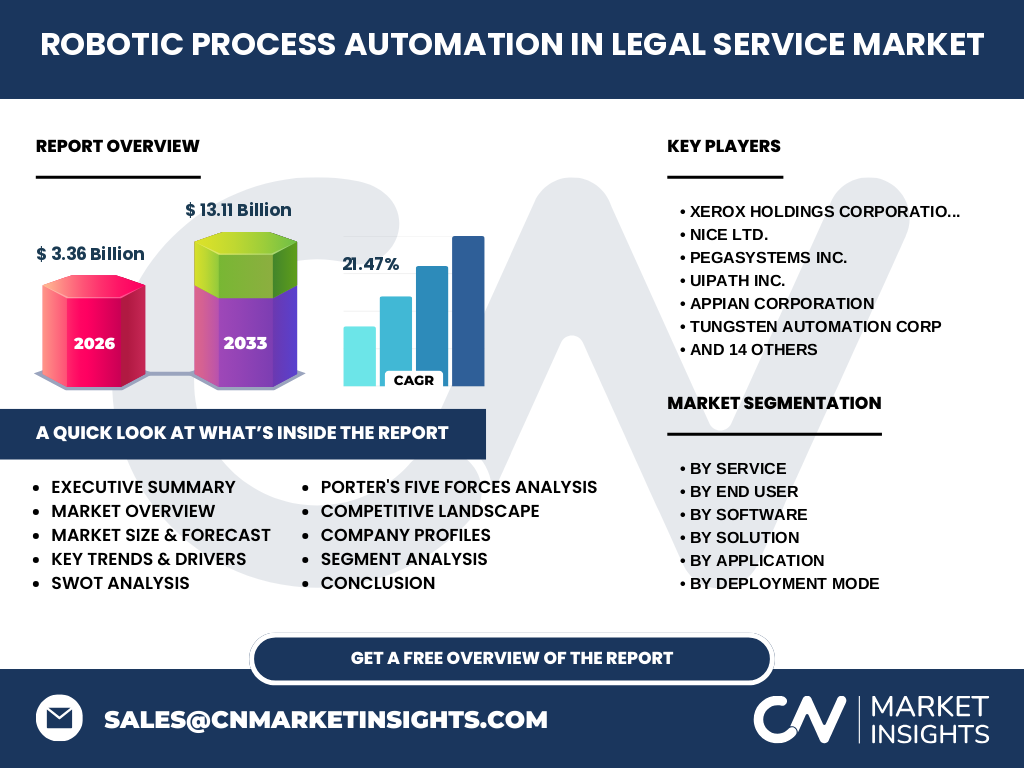
Our analysis indicates that the Robotic Process Automation In Legal Service Market is valued at 3.36 Billion in 2026. This sector transforms traditional legal operations by deploying software bots to execute repetitive, rule-based workflows, shifting legal professionals toward high-value advisory roles while ensuring strict adherence to regulatory standards set by bodies like the American Bar Association.
Key market drivers, restraints, challenges, and opportunities shaping Robotic Process Automation In Legal Service Market
The primary catalyst is the urgent need to reduce operational overhead in billable-hour structures. However, implementation is restrained by legacy system integration hurdles and data privacy fears regarding client confidentiality under GDPR. Opportunities abound in automating compliance monitoring and contract analysis for corporate legal departments.
Emerging trends and growth patterns in Robotic Process Automation In Legal Service Market
Law firms are increasingly pairing workflow automation with cognitive data extraction to parse unstructured discovery documents. Cloud deployment is outpacing on-premise models, driven by the need for scalable, secure infrastructure that allows distributed legal teams to access automated case management tools remotely.
COVID-19 impact analysis — how the pandemic affected Robotic Process Automation In Legal Service Market and the recovery trajectory
The pandemic acted as an accelerant for digital transformation across the legal sector. As courts shifted to virtual hearings and lawyers worked remotely, demand for automated billing, invoicing, and document management surged, establishing a resilient post-pandemic recovery trajectory centered on cloud-native solutions.
Competitive landscape — major players, market concentration, and strategic dynamics
The market features a mix of enterprise automation giants like UiPath Inc., Automation Anywhere Inc, and Blue Prism Group plc alongside legal-specific innovators such as Luminance Technologies Limited. and Onit Inc. Strategic dynamics involve aggressive M&A and platform partnerships to embed AI capabilities directly into legal workflows.
Executive summary — high-level synthesis of key findings about Robotic Process Automation In Legal Service Market
Our research confirms the Robotic Process Automation In Legal Service Market will expand from 3.36 Billion in 2026 to 13.11 Billion by 2033 at a CAGR of 21.47%. This explosive growth is propelled by corporate legal departments demanding cost efficiencies and faster turnaround times from external counsel.
Market forecast — projected growth from 2027 to 2033
Driven by a robust 21.47% CAGR, the market will scale dramatically between 2027 and 2033 to reach 13.11 Billion. This trajectory reflects mainstream adoption moving beyond early adopters to mid-sized law firms and government legal entities seeking automated compliance and litigation support.
Segmentation analysis — break down each segment category, explain what it covers and its market role
Market segmentation spans multiple categories: By Service (consulting, implementation, training, support, process assessment, custom development); By End User (law firms, corporate legal departments, government entities); By Software (workflow automation, document management, contract analysis, case management, compliance monitoring, data extraction); By Solution (software, service); By Application (document management, contract management, compliance management, billing/invoicing, litigation support); and By Deployment Mode (on-premise, cloud).
Regional market analysis — geographic distribution and performance across regions
North America dominates adoption due to early technology integration in major law firms, followed closely by Europe, where stringent data protection regulations heavily influence deployment strategies. Asia-Pacific represents the fastest-growing frontier as regional legal hubs modernize their administrative processes.
In-depth regional review — detailed examination of key regional markets
In North America, corporate legal departments are aggressively adopting cloud-based contract analysis bots to streamline operations. Meanwhile, European markets prioritize on-premise and hybrid compliance monitoring solutions to ensure strict alignment with regional data sovereignty laws and local bar association mandates.
Company profiles — strategic positioning of leading companies in Robotic Process Automation In Legal Service Market
Industry leaders leverage distinct strategic advantages. UiPath Inc. and Automation Anywhere Inc provide robust enterprise software platforms, while specialized players like Luminance Technologies Limited. and Juro Online Limited. focus intensely on legal-specific contract analysis and document management use cases.
Porter's Five Forces analysis — competitive forces assessment
Bargaining power of buyers is moderate to high, as law firms demand customized integrations. Threat of new entrants is mitigated by high switching costs and the specialized regulatory knowledge required to build legally compliant automation bots, though tech giants pose a continuous competitive threat.
SWOT analysis — strengths, weaknesses, opportunities, and threats
Key strengths include massive error reduction in billing and document handling. Weaknesses involve high initial deployment costs. Opportunities lie in expanding cloud deployment across emerging legal markets, while threats include evolving cybersecurity vulnerabilities and stringent regulatory penalties for data breaches.
Value chain analysis — industry structure and value flow from raw materials to end-users
The value chain flows from core AI and OCR technology developers through software vendors and specialized implementation partners, culminating in end-users like law firms and corporate legal departments. Value is added at each stage through custom development, process assessment, and staff training services.
Investment insights — strategic recommendations and high-potential areas
Investors should target providers offering pre-built legal connectors for contract analysis and compliance monitoring. Companies that bridge the gap between complex litigation support requirements and user-friendly cloud interfaces present the highest potential for capturing high-margin enterprise contracts.
Conclusion and key takeaways
The Robotic Process Automation In Legal Service Market represents a critical investment frontier, forecasted to achieve 13.11 Billion by 2033. Organizations that successfully navigate integration hurdles and adopt secure cloud solutions will dominate the next era of legal technology innovation.
Research methodology — detail how baseline estimates are triangulated
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with legal tech CIOs, trade registry data from major global jurisdictions, and secondary macroeconomic indicators tracking enterprise software spending across the legal services sector.
Scope of the report — coverage parameters and limitations
This report covers global adoption trends, vendor market shares, and segment forecasts from 2027 to 2033. Limitations include an exclusion of informal, custom in-house scripts developed by law firms without commercial software vendor involvement.
Recent developments — company announcements, product launches, partnerships, and strategic moves
Recent market activity highlights intense partnership initiatives between general-purpose automation providers like Pegasystems Inc. and legal tech platforms. Companies are frequently launching generative AI-infused document extraction modules to capture the surging demand for automated litigation support and contract review.