What is the market overview and scope of the Specialty Alumina Market?
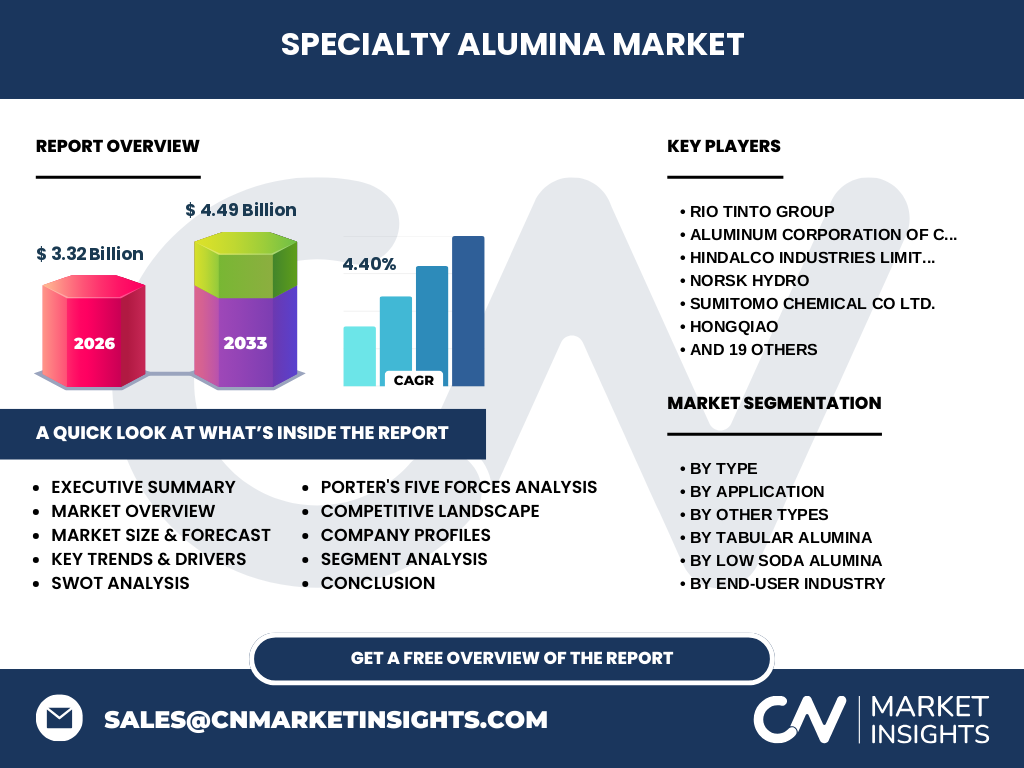
Our research indicates that the Specialty Alumina Market stands at 3.32 Billion in 2026, driven by high-purity applications in technical ceramics and refractories. Based on our analysis, this sector encompasses refined aluminum oxides tailored for extreme thermal, chemical, and electrical endurance across advanced industrial ecosystems.
Structural Growth Drivers and Restraints in the Specialty Alumina Market
The Specialty Alumina Market industry trends point to electrification and lightweighting in automotive manufacturing as primary accelerators. However, strict environmental compliance overseen by agencies like the EPA and EU REACH regarding bauxite residue management acts as a significant operational restraint for producers.
Emerging trends and growth patterns in Specialty Alumina Market
A notable shift toward customized morphology is redefining the Specialty Alumina Market market size potential. Manufacturers are increasingly prioritizing low soda calcined grades to meet stringent dielectric requirements in semiconductor components and high-voltage lithium-ion battery separators.
COVID-19 impact analysis and recovery trajectory
The pandemic severely disrupted global supply chains, yet the Specialty Alumina Market demonstrated remarkable resilience. Recovery has been accelerated by localized sourcing strategies and robust fiscal stimulus injected into aerospace and renewable energy infrastructure projects worldwide.
Competitive Benchmarking in the Specialty Alumina Market
Industry leadership is fiercely contested by giants like Alcoa Corporation, Rio Tinto Group, and Almatis GmbH. These market participants leverage vertically integrated bauxite supply chains and proprietary crystal growth technologies to maintain dominance in high-margin refractory and polishing segments.
Executive Summary of the Specialty Alumina Market
Our analysis projects the Specialty Alumina Market to expand from 3.32 Billion in 2026 to 4.49 Billion by 2033, registering a steady CAGR of 4.40%. This trajectory underscores robust demand across demanding end-use verticals like chemicals and industrial electronics.
Market forecast from 2027 to 2033
Driven by compounding industrial demand, the Specialty Alumina Market is slated to achieve a valuation of 4.49 Billion by 2033. This expansion is fueled by accelerated adoption of advanced technical ceramics within emerging renewable energy infrastructure globally.
Segmentation analysis across product types and applications
The Specialty Alumina Market report categorizes products into Standard Calcined Alumina, Tabular Alumina, White Fused Alumina, Medium Soda Calcined Alumina, and Low Soda Alumina. Applications span Refractories, Ceramics, Abrasives, and Catalysts, with end-users ranging from Automotive to Aerospace.
Regional market analysis and geographic performance
Geographically, the Asia-Pacific region dominates the Specialty Alumina Market due to concentrated manufacturing hubs in China and India. Meanwhile, North America and Europe maintain steady demand fueled by stringent aerospace specifications and advanced chemical processing industries.
In-depth regional review of key growth territories
Regional insights reveal that Asia-Pacific leads consumption, supported by massive capacity additions from players like Aluminum Corporation of China Limited. Conversely, European markets focus heavily on high-purity specialty grades from producers like Nabaltec AG and ALTEO.
Company profiles and strategic positioning
Key industry players utilize distinct moats; for instance, Sumitomo Chemical Co Ltd. and Nippon Light Metal Holdings Company Ltd. focus on ultra-high purity grades for electronics. Simultaneously, regional specialists like Silkem doo and AluChem capture niche industrial applications.
Porter's Five Forces analysis of competitive intensity
The Specialty Alumina Market exhibits moderate-to-high supplier power due to concentrated bauxite reserves, while buyer power is tempered by the specialized, mission-critical nature of high-purity alumina grades utilized in extreme thermal and chemical environments.
SWOT analysis of the Specialty Alumina Market
Strengths include exceptional thermal shock resistance and dielectric properties. Weaknesses involve high energy intensity during calcination. Opportunities lie in EV battery separators, while threats stem from strict carbon emission regulations impacting traditional smelting and refining operations.
Value chain analysis from raw materials to end-users
The value chain initiates with bauxite extraction, processed via the Bayer process into intermediate alumina hydrate, then calcined into specialized grades. Logistics hubs near major ports facilitate global distribution to end-users in automotive, aerospace, and refractory sectors.
Investment insights and high-potential growth areas
Investors should target low soda calcined alumina and reactive alumina producers catering to EV battery components. Our research highlights these sub-segments as high-potential areas offering superior margins compared to traditional commodity-grade refractories.
Conclusion and key takeaways for stakeholders
Reaching 4.49 Billion by 2033 at a 4.40% CAGR, the Specialty Alumina Market presents lucrative avenues. Stakeholders must invest in energy-efficient calcination technologies and sustainable bauxite refining to navigate evolving regulatory landscapes successfully.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary qualitative interviews with C-level executives across major producers, and secondary macroeconomic indicators from global industrial manufacturing associations.
Scope of the report and coverage parameters
This comprehensive Specialty Alumina Market analysis covers historical data from past years, estimated figures for 2026 at 3.32 Billion, and forecasts through 2033. It evaluates global regional dynamics, segmented product categories, and competitive positioning of leading enterprises.
Recent developments, partnerships, and strategic moves
Recent industry dynamics feature major producers such as BASF SE, Hindalco Industries Limited, and Rusal forming strategic joint ventures and expanding calcination capacities to secure stable supply chains for high-purity specialty ceramics and advanced automotive components.