What is the Market overview of the Fuel Oil Market?
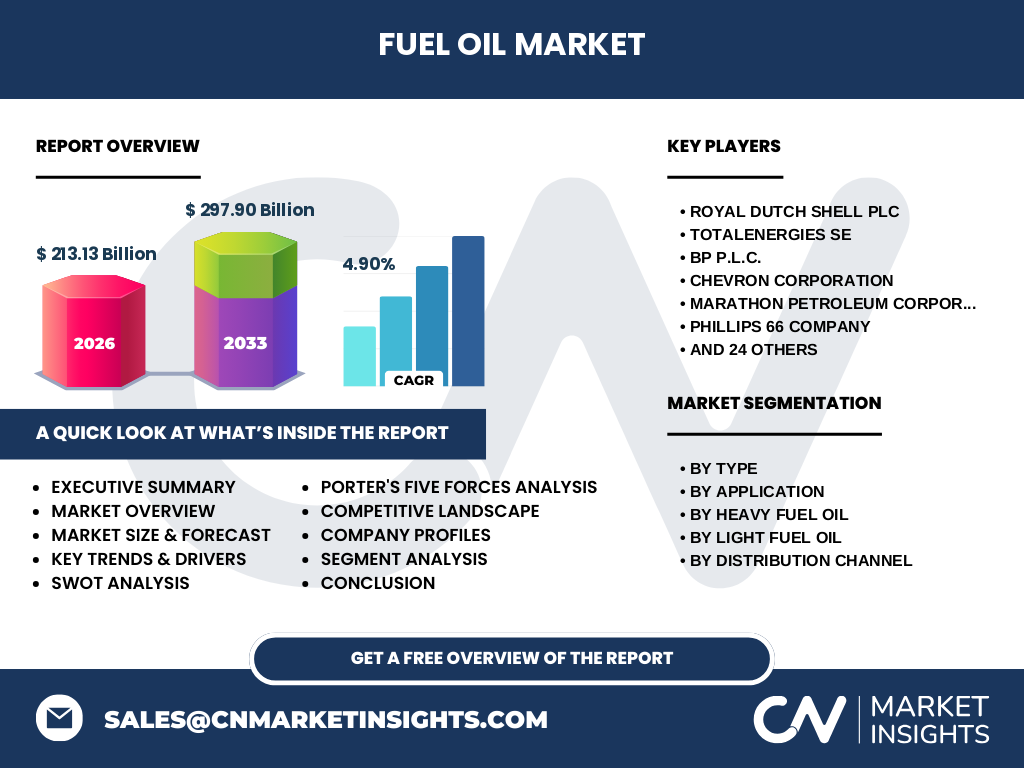
Our analysis indicates that the Fuel Oil Market valuation reached 213.13 Billion, driven by complex refining outputs and heavy industrial demands. This sector encompasses residual and distillate fractions utilized heavily across maritime logistics, thermal power generation, and petrochemical feedstocks globally.
Key market drivers, restraints, challenges, and opportunities shaping Fuel Oil Market
Growth is anchored by rising marine bunker fuel consumption, though stringent International Maritime Organization (IMO) sulfur caps act as a notable restraint. Opportunities lie in upgrading heavy residues into low-sulfur distillates, rewarding refiners with advanced hydroprocessing technologies.
Emerging trends and growth patterns in Fuel Oil Market
The shift toward ultra-low sulfur fuel oils and blended marine bunkers is redefining supply chains. Based on our research, refiners like Exxon Mobil Corporation and Shell are pivoting toward cleaner residue valorization to navigate evolving environmental mandates.
How did COVID-19 impact the Fuel Oil Market and shape its recovery trajectory?
Pandemic-induced travel restrictions caused an unprecedented collapse in aviation and maritime transport, severely compressing refining margins. The recovery trajectory has since been propelled by rebounding industrial activity and a swift normalization of global supply chain bottlenecks.
Competitive Benchmarking and Market Concentration
The Fuel Oil Market exhibits high consolidation among state-owned giants and supermajors. Integrated players like Saudi Aramco, TotalEnergies SE, and BP p.l.c. leverage vast upstream extraction networks and proprietary refining configurations to dominate global trade routes.
Executive summary of key findings about the Fuel Oil Market
Our comprehensive assessment highlights a robust expansion trajectory, projecting the market to reach 297.90 Billion by 2033. Strategic positioning in deep-conversion refining will dictate profitability as environmental regulations tighten across key consumer hubs.
What is the projected market forecast from 2027 to 2033?
The data suggests the sector will expand at a steady 4.90% CAGR between 2027 and 2033. This growth underscores the enduring reliance on heavy fractions within emerging economies lacking immediate electrification infrastructure.
Segmentation analysis across product types and applications
Market segmentation divides offerings into Heavy Fuel Oil (marine, industrial, power) and Light Fuel Oil (heating oil, diesel, kerosene). Application categories span Marine Bunkers, petrochemicals, electricity generation, and domestic waterways, each driven by distinct end-user consumption cycles.
Regional market analysis and geographic performance distribution
Geographic performance is heavily skewed toward regions with dense industrial manufacturing and major shipping corridors. Asia-Pacific leads consumption due to robust manufacturing output, while the Middle East maintains dominance in primary refining and export capacities.
In-depth regional review of key consuming and producing territories
Regional dynamics reveal that North America focuses on upgrading heavy residues into light products, whereas European markets face intense pressure from stringent decarbonization policies, forcing refiners to adopt advanced carbon-reduction strategies.
Strategic positioning of leading companies in the sector
Industry leaders such as Chevron Corporation, Valero Energy Corporation, and Sinopec Corp. optimize their asset portfolios to balance high-margin distillate yields with traditional heavy fuel production, ensuring resilience against commodity price volatility.
Porter's Five Forces analysis of competitive intensity
Bargaining power of suppliers remains moderate due to state-controlled crude reservoirs, while buyer power is high among large shipping consortia. Threat of substitution is elevated by liquefied natural gas (LNG) adoption in maritime transport.
SWOT analysis of the global sector
Strengths include established distribution networks via Oil Pipelines and deep-water terminals. Weaknesses involve high carbon footprints, while opportunities emerge in cleaner marine blends, contrasted by threats from aggressive global renewable energy mandates.
Value chain analysis from raw materials to end-users
The value chain initiates with crude oil extraction, flowing through atmospheric and vacuum distillation units in refineries, and reaching end-users via complex logistics involving Gas Stations, marine bunkering barges, and dedicated distribution stores.
Investment insights and high-potential areas for capital allocation
High-potential capital allocation targets hydrocracking units and sulfur-removal technologies. Investors should favor integrated operators capable of weathering shifting regulatory landscapes while maintaining steady petrochemical feedstock yields.
Conclusion and critical industry takeaways
The sector remains a cornerstone of global energy and maritime transport. Long-term viability depends on technological adaptation, operational efficiency, and strict compliance with international environmental standards governing sulfur and greenhouse gas emissions.
Research methodology and baseline estimation triangulation
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with refinery executives, and secondary macroeconomic indicators from energy ministries and international trade organizations.
Scope of the report and coverage parameters
This report covers global production, consumption trends, pricing dynamics, and regulatory impacts across specified segments from 2027 through 2033, excluding minor unlicensed regional spot-market transactions.
Recent developments, partnerships, and strategic corporate moves
Recent corporate announcements highlight strategic joint ventures among refiners like Reliance Industries Limited and ADNOC to secure long-term feedstock supply agreements and invest in low-carbon marine fuel alternatives to meet future compliance targets.