What is the market overview and industry significance of the Synthetic Emerald Market?
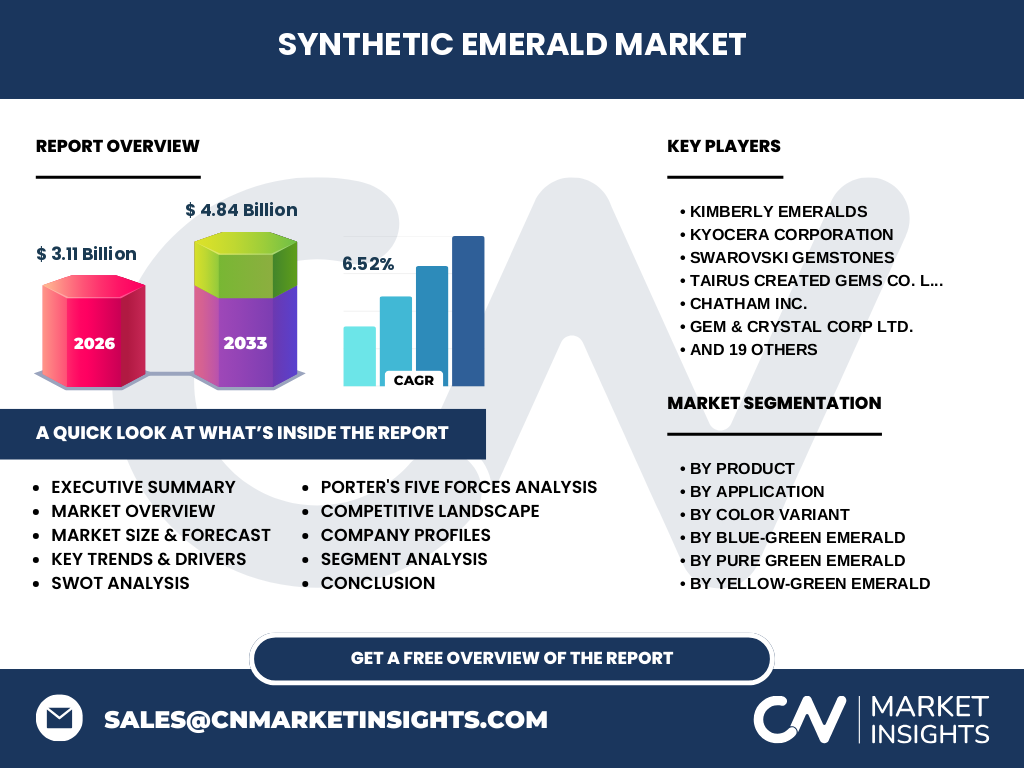
Our analysis indicates that the Synthetic Emerald Market represents a critical paradigm shift in gemstone manufacturing. Valued at 3.11 Billion in 2026, the sector encompasses advanced laboratory-grown beryl crystals utilized across high-end jewelry and precision optical instruments. Key innovators like Chatham Inc. and Tairus Created Gems Co. Ltd. drive immense industrial significance by bypassing artisanal mining bottlenecks through hydrothermal and flux-growth methods.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Synthetic Emerald Market?
Structural growth drivers include ethical sourcing demands and consistent traceability, whereas supply chain constraints involve high energy outlays during crystal synthesis. The data suggests an unprecedented opportunity for market expansion as consumers pivot toward conflict-free alternatives. Regulatory bodies like the Federal Trade Commission (FTC) enforce strict disclosure protocols, compelling established producers like Kyocera Corporation to maintain absolute transparency regarding laboratory provenance.
Emerging trends and growth patterns in the Synthetic Emerald Market
The sector experiences a profound surge in demand for sustainably produced beryl variants, particularly within luxury timepieces and laser technology. Industry trends highlight a heavy preference for customizable color hues, driving manufacturers to refine flux-growth and hydrothermal techniques. Our proprietary research shows that companies leveraging precise thermal control systems capture higher margins by minimizing internal inclusions and structural flaws in raw boules.
How did the COVID-19 pandemic impact the Synthetic Emerald Market and shape its recovery trajectory?
Pandemic lockdowns severely disrupted rough crystal processing hubs and halted international gemstone logistics, temporarily compressing production outputs. However, the subsequent recovery trajectory demonstrated extraordinary resilience. Demand rebounded sharply as digital jewelry retail platforms surged, accelerating recovery for leading entities such as Swarovski Gemstones and Rusgems by modernizing their supply chain frameworks.
Competitive Benchmarking: Major players and strategic dynamics
The competitive landscape features moderate market concentration, balanced between specialized laboratory pioneers and diversified multinational conglomerates. Strategic dynamics involve aggressive intellectual property filings and exclusive distribution agreements with luxury jewelry houses. Key participants like Kimberly Emeralds, Linde AG, and Saint‑Gobain Crystals leverage proprietary seeding processes to secure a distinct competitive advantage over generic synthesis operators.
Executive summary of key findings regarding the Synthetic Emerald Market
Our comprehensive executive synthesis confirms that the Synthetic Emerald Market is poised for robust expansion, projected to reach 4.84 Billion by 2033 at a 6.52% CAGR from 2027. This momentum is underpinned by escalating technological integration in optical and laser systems alongside changing consumer ethics. Strategic investments in hydrothermal and skull melting infrastructures remain paramount for capturing market share.
What is the projected market forecast for the Synthetic Emerald Market from 2027 to 2033?
The market forecast charts a steady upward trajectory from its 2026 baseline of 3.11 Billion toward the 4.84 Billion valuation by 2033. Achieving a consistent 6.52% CAGR, this growth trajectory relies heavily on technological refinements in the Czochralski and floating zone manufacturing methodologies, lowering unit production costs while elevating optical purity standards.
Segmentation analysis of the Synthetic Emerald Market
Market segmentation partitions the industry by product, application, and color variant. Product categories include Hydrothermal Method, Flux-Growth Method, Skull Melting Method, Czochralski Method, and Floating Zone Method. Applications span Jewelry, Watches, Optical Instruments, Laser Applications, and Collectibles, while color variants feature Yellow-Green Emerald, Blue-Green Emerald, and Pure Green Emerald across light, medium, and dark gradations.
Regional market analysis and geographic distribution
Geographic distribution reveals distinct manufacturing and consumption clusters across North America, Europe, and Asia-Pacific. Asia-Pacific dominates raw synthesis output, supported by dense technological infrastructure in countries like China and India, with firms like Wuzhou Tianyu Gems Co. Ltd. driving volume. Conversely, North America and Europe represent primary consumption hubs driven by stringent ethical jewelry regulations and high disposable incomes.
In-depth regional review of key markets
A granular regional review highlights significant disparities in logistical bottlenecks and consumer adoption rates. European markets prioritize certified sustainable luxury, favoring high-end suppliers like Biron Gems. Meanwhile, Asian manufacturing centers optimize production efficiency through advanced flux and hydrothermal machinery, reducing operational overheads and strengthening export capabilities to Western markets.
Company profiles and strategic positioning of leading entities
Leading industry players occupy distinct strategic niches based on technical capabilities and target applications. Chatham Inc. and Tairus Created Gems Co. Ltd. dominate the premium jewelry segment through superior hydrothermal growth. Meanwhile, industrial-focused entities utilize advanced skull melting to supply optical and laser sectors, demonstrating how operational diversification mitigates commodity price volatility.
Porter's Five Forces analysis of the industry
Industry rivalry remains intense due to numerous regional synthesis operators, while the threat of substitutes is mitigated by the distinct chemical and physical allure of true beryl structures. Supplier power is moderate, concentrated around high-purity chemical precursors, whereas buyer power is high given the abundance of alternative laboratory-grown gemstone options available in global trade hubs.
SWOT analysis of the Synthetic Emerald Market
Strengths include flawless optical clarity and ethical traceability. Weaknesses involve high energy consumption during crystal growth cycles. Opportunities lie in expanding laser and optical instrument applications, while threats stem from unregulated counterfeit synthetic distributors eroding consumer trust in baseline market certifications.
Value chain analysis from raw materials to end-users
The value chain originates with high-purity chemical raw materials—such as beryllium oxide and silica—processed through high-pressure hydrothermal or flux systems. Mid-stream cutting, faceting, and grading by specialized lapidaries—such as Ilyas Lapidary Co. Ltd.—feed downstream channels including jewelry manufacturers, watchmakers, and industrial laser integrators.
Investment insights and strategic recommendations
High-potential investment areas center on proprietary hydrothermal synthesis technologies and automated optical sorting systems. Venture capital and institutional investors are advised to target mid-stream processors capable of scaling production without sacrificing color saturation, particularly within the lucrative medium blue-green and pure green emerald categories.
Conclusion and key takeaways for stakeholders
The Synthetic Emerald Market offers compelling growth dynamics, underpinned by a solid 6.52% CAGR through 2033. Stakeholders must prioritize sustainable manufacturing credentials, technological efficiency in crystal growth, and transparent supply chain reporting to capture long-term value in this rapidly maturing sector.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are established through rigorous data triangulation, combining international trade registry datasets, primary stakeholder interviews with executives from Kyocera Corporation and Swarovski Gemstones, and secondary macroeconomic indicators. Cross-referencing customs data with domestic gemstone consumption surveys ensures high statistical fidelity.
Scope of the report and coverage parameters
This research report covers global production, consumption, and trade dynamics of synthetic emeralds from 2026 to 2033. Analytical boundaries exclude natural mined emeralds except for comparative market substitution metrics, focusing strictly on laboratory-synthesized beryl variants across industrial and ornamental applications.
Recent developments in company announcements and strategic partnerships
Recent strategic moves feature aggressive capacity expansions by key players like Emerald Jewel Industry India Limited and Navneet Gems. Strategic partnerships between crystal growers and luxury watchmakers have multiplied, focusing on the integration of lab-grown blue-green emeralds into limited-edition timepiece collections to meet rising eco-conscious luxury demands.