What is the Slag Cement Market overview, scope, and industry significance?
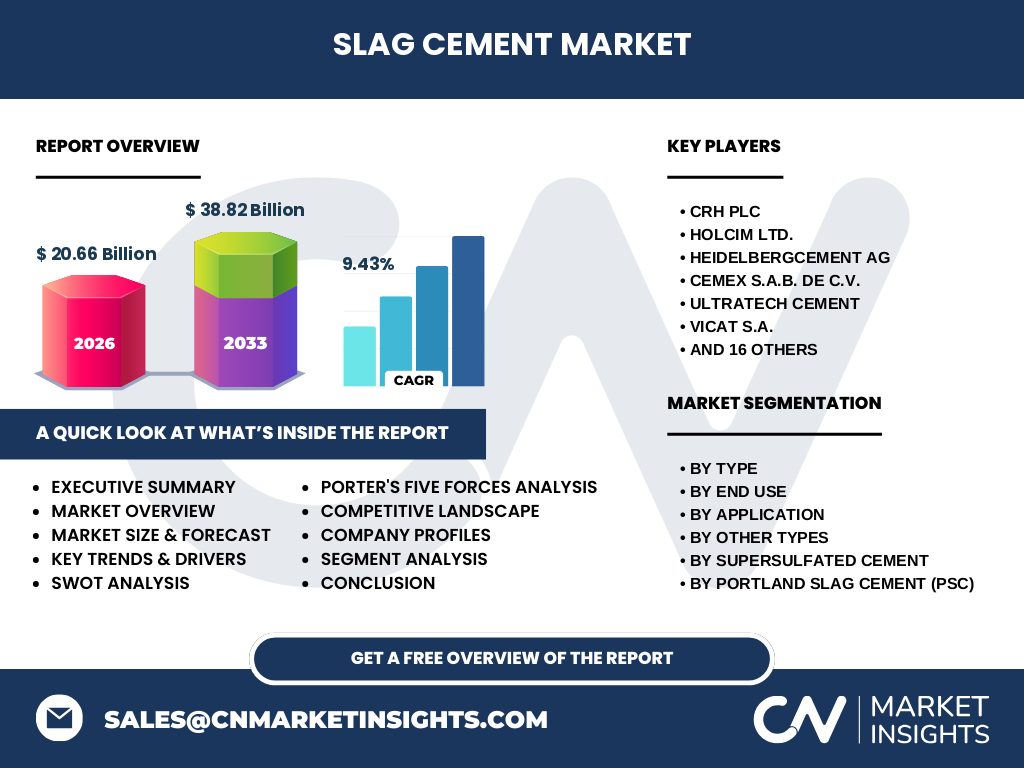
The Slag Cement Market market size is valued at 20.66 Billion in 2026, driven by the co-product utilization of blast furnace slag from iron manufacturing. This sector provides essential supplementary cementitious materials that reduce the clinker factor in Portland cement, lowering embodied carbon for heavy infrastructure projects worldwide.
Key market drivers, restraints, challenges, and opportunities shaping Slag Cement Market
Strict environmental mandates from bodies like the EPA and EU ETS act as core growth catalysts. Decarbonization pressures force producers to adopt Ground Granulated Blast Furnace Slag (GGBFS). However, logistical bottlenecks in raw material transport and high capital expenditure for granulation plants remain primary market constraints.
Emerging trends and growth patterns in Slag Cement Market
The industry is witnessing an accelerated shift toward alkali-activated binders and ultra-low carbon formulations. Major consumers in commercial construction now demand high-performance concrete mixes incorporating specialized blended cements to meet net-zero targets, fundamentally altering regional procurement strategies.
COVID-19 impact analysis and recovery trajectory
Pandemic-era supply chain disruptions severely constricted iron and steel output, directly starving raw slag grinding facilities of feedstocks. Post-COVID recovery has been robustly supercharged by government stimulus packages targeting green infrastructure and massive public works, stabilizing feedstock supply chains.
Competitive benchmarking and strategic market concentration
The Slag Cement Market industry trends highlight a consolidated landscape dominated by multinational giants like Holcim Ltd., CEMEX S.A.B. de C.V., and HeidelbergCement AG. These market leaders leverage extensive vertical integration and localized slag-sourcing networks to maintain pricing power against regional competitors.
Executive summary of key findings
Our analysis indicates that the sector will achieve a remarkable 9.43% CAGR from 2027 to 2033. Driven by stringent carbon regulations and surging demand for sustainable infrastructure, market participants must pivot toward value-added applications like alkali-activated GGBFS to capture premium margins.
Market forecast from 2027 to 2033
Driven by compounding sustainability mandates and massive urbanization initiatives, the Slag Cement Market analysis projects total valuation to expand from 20.66 Billion to 38.82 Billion by 2033. This trajectory reflects an accelerated adoption curve across both mature and emerging economies.
Segmentation analysis across types, end uses, and applications
The market breaks down by type into Ground Granulated Blast Furnace Slag (GGBFS), Portland Slag Cement (PSC), Supersulfated Cement, and Other Types. End uses span residential, commercial, and industrial construction, with infrastructure development claiming the largest share of high-performance ready-mix concrete applications.
Regional market analysis and geographic distribution
Geographic performance is heavily skewed toward regions with high steel production capacity, notably Asia-Pacific. Localized environmental policies and massive investments in coastal mass concrete applications determine how rapidly regional supply chains can absorb processed blast furnace slag.
In-depth regional review of key growth zones
Asia-Pacific leads consumption due to aggressive infrastructure expansion in developing economies, supported by domestic steel giants. Meanwhile, Europe enforces strict carbon taxation, compelling ready-mix concrete producers to maximize supplementary cementitious materials usage through specialized Portland Slag Cement variants.
Company profiles and strategic positioning of leading players
Industry leaders such as UltraTech Cement, JSW Cement Limited, and Vicat S.A. deploy aggressive capacity expansions and strategic co-processing partnerships with steel mills. Their competitive advantage stems from secure, long-term access to blast furnace slag feedstocks.
Porter's Five Forces analysis of competitive pressures
Supplier power remains moderate due to dependence on steel mill outputs, while threat of substitutes is mitigated by unique durability attributes in marine-grade and high-sulfate environments. Competitive rivalry is intensely high among established multinational cement producers.
SWOT analysis of the sector
Strengths include superior sulfate resistance and lower embodied carbon. Weaknesses involve high freight logistics costs. Opportunities lie in alkali-activated binders for industrial construction, whereas threats stem from potential volatility in steel production cycles restricting raw slag availability.
Value chain analysis from raw materials to end-users
The value chain originates with steel manufacturing blast furnace slag generation, progressing through granulation, specialized grinding, and blending facilities operated by firms like Buzzi Unicem S.p.A. and Dalmia Cement Limited, before reaching ready-mix concrete batching plants.
Investment insights and high-potential growth areas
High-potential capital allocation targets fine ground granulated blast furnace slag and proprietary alkali-activated systems. Investors should prioritize asset-backed cement producers with secured steel-mill off-take agreements to insulate against raw material supply shocks.
Conclusion and key takeaways
The Slag Cement Market market size expansion to 38.82 Billion underscores a structural transformation in construction materials. Companies that successfully decouple production from traditional clinker while optimizing logistics will capture disproportionate market share.
Research methodology for baseline estimates
Baseline estimates are triangulated using a rigorous mix of trade registry data, primary stakeholder interviews with cement plant executives, and macroeconomic construction output indicators from bodies such as the World Steel Association and local building authorities.
Scope of the report and coverage parameters
This Slag Cement Market analysis covers global consumption trends, regional manufacturing capacities, and product segmentations spanning 2026 to 2033. Excluded from this scope are non-slag mineral admixtures such as fly ash and natural pozzolans.
Recent developments in partnerships and product launches
Recent strategic moves feature major collaborations between cement manufacturers and steel producers to establish localized, low-carbon granulation hubs. Innovations focus on rapid-hardening Portland Slag Cement formulations designed to accelerate formwork turnaround times in commercial building projects.