Market overview and structural significance of the Gypsum Market
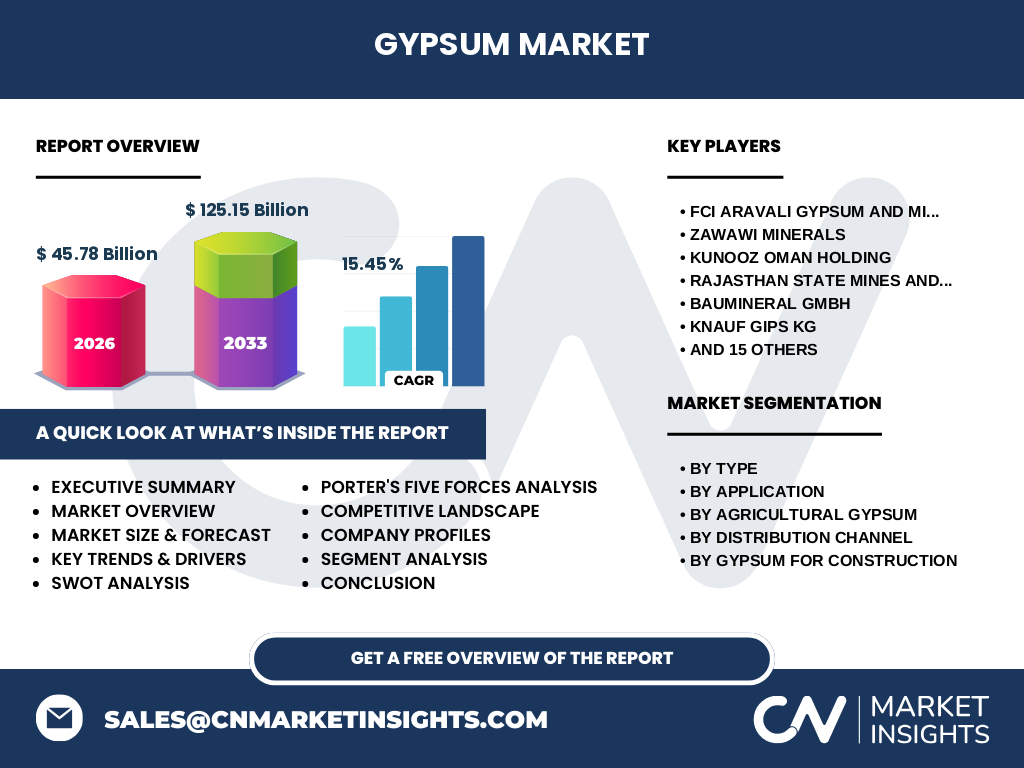
Our analysis indicates the Gypsum Market reached a baseline valuation of 45.78 Billion in 2026, driven by its critical role in modern construction and agricultural soil stabilization. This sector encompasses mineral extraction, processing, and distribution of natural and synthetic calcium sulfate dihydrate, serving as a foundational commodity for global infrastructure development and high-efficiency farming practices.
What are the key market drivers, restraints, challenges, and opportunities shaping the Gypsum Market?
Growth is propelled by surging urbanization and the rising demand for lightweight construction materials, though strict environmental regulations regarding flue gas desulfurization (FGD) byproducts present ongoing compliance challenges. Strategic opportunities lie in expanding agricultural gypsum applications for sodic soil reclamation, offsetting high logistics costs associated with bulk mineral transport.
Emerging trends and growth patterns in the Gypsum Market
The industry is witnessing an accelerated shift toward circular economy models, with major producers increasingly integrating recycled synthetic gypsum from industrial waste streams. Furthermore, technological advancements in calcination kilns are reducing carbon footprints, directly benefiting eco-conscious manufacturers aiming for net-zero carbon building certifications.
COVID-19 impact analysis and recovery trajectory
The pandemic caused severe supply chain disruptions and temporary project halts across global construction hubs, yet the Gypsum Market rebounded aggressively due to government-backed infrastructure stimulus packages. Pent-up residential housing demand and accelerated remote-work suburban relocations drove rapid post-lockdown volume recovery across all major distribution tiers.
Competitive benchmarking and market concentration
The competitive landscape features a mix of multinational conglomerates and localized mining enterprises, resulting in moderate market concentration. Industry leaders such as Knauf Gips KG and British Gypsum leverage extensive vertical integration, while regional players like Rajasthan State Mines and Minerals Limited dominate localized raw material extraction.
Executive summary of key findings
Our comprehensive evaluation projects the Gypsum Market to expand from 45.78 Billion in 2026 to 125.15 Billion by 2033, registering a robust CAGR of 15.45%. This exceptional trajectory is anchored by rapid urbanization across emerging economies and heightened adoption of advanced drywall systems and soil amendment protocols.
Market forecast from 2027 to 2033
Driven by sustained commercial real estate investments and agricultural modernization, the market is poised for exponential expansion, surging from 2027 through 2033 to achieve the projected 125.15 Billion valuation. This trajectory reflects a stellar 15.45% CAGR, outperforming historical growth rates due to rising material efficiency and automated manufacturing.
Segmentation analysis across core operational categories
The market divides into two primary pillars: Gypsum For Construction—encompassing Gypsum Board (Drywall), Gypsum Plaster, and Gypsum Blocks—and Agricultural Gypsum, subdivided into Soil Amendment Gypsum and Fertilizer Gypsum. Application segments include Underground Mining and Surface Mining, serviced via Direct Sales, Wholesaler Network, and E‑Commerce Channels.
Regional market analysis and geographic performance
Geographic performance highlights Asia-Pacific as the dominant consumption center, propelled by massive residential megaprojects in emerging economies, while North America and Europe maintain steady demand centered on renovation projects and stringent building safety codes. Logistics corridors and proximity to key ports heavily influence regional trade balance and pricing power.
In-depth regional review of key markets
Middle Eastern and African territories are experiencing unprecedented demand for raw binders, supported by entities like Zawawi Minerals and Kunooz Oman Holding. Meanwhile, North American markets heavily prioritize high-performance drywall solutions, creating lucrative operational environments for established producers such as National Gypsum and Harrison Gypsum.
Strategic company profiles within the Gypsum Market
Key industry participants occupy distinct strategic niches: ETEX Group focuses on advanced architectural envelopes, while FCI Aravali Gypsum and Minerals and United Mining Industries Company Limited secure robust upstream supply security through extensive quarry operations. European players like Baumineral GmbH specialize in high-grade industrial mineral processing and synthetic gypsum valorization.
Porter's Five Forces analysis of competitive intensity
Rivalry within the sector is intense due to high capital expenditure requirements for quarry acquisition, though supplier power remains moderate given the abundance of global mineral reserves. Threat of substitutes is mitigated by gypsum's unmatched fire-retardant and acoustic properties in wallboard construction, solidifying its irreplaceable structural status.
SWOT analysis of the global sector
Strengths include abundant natural reserves and superior thermal insulation properties, counterbalanced by weaknesses such as high transportation weight and carbon-intensive calcination processes. Opportunities abound in agricultural soil remediation and green building materials, while regulatory carbon pricing mechanisms present a persistent operational threat.
Value chain analysis from raw materials to end-users
The value chain initiates with open-cast or underground extraction by entities like Rajasthan State Mines and Minerals Limited, progressing through crushing, thermal dehydration, and pulverization. Finished binders move through Wholesaler Network and Direct Sales channels to end-use construction sites and agricultural cooperatives.
Investment insights and high-potential areas
Investors should target technological innovators focusing on low-temperature calcination and synthetic gypsum upcycling to capture premium margins amid tightening environmental mandates. Geographically, investments in Middle Eastern extraction hubs and Asian distribution networks offer exceptional yield potential matching the 15.45% CAGR.
Conclusion and key takeaways
The Gypsum Market represents a high-growth, essential industrial sector projected to reach 125.15 Billion by 2033. Success for market participants hinges on balancing aggressive production scaling with sustainable, low-carbon manufacturing innovations across both construction and agricultural segments.
Research methodology for baseline estimation
Our research methodology triangulates data by synthesizing customs trade registries, primary qualitative interviews with C-suite mining executives, and secondary macroeconomic indicators from global construction indices. This multi-layered approach ensures precise sizing of the Gypsum Market market size and validated growth trajectories.
Scope of the report and coverage parameters
This report covers global revenue performance and volume shipments from 2027 to 2033, analyzing all major product grades, application verticals, and distribution channels. Limitations include unpredictable geopolitical shifts impacting maritime freight rates and localized regulatory changes regarding mining concessions.
Recent developments and strategic industry movements
Recent market activities feature aggressive capacity expansions by Knauf Gips KG and strategic cross-border supply partnerships forged by regional miners like Cerro Cazador SA and Awam Group LLC. These moves underscore a broader industry trend toward supply chain resilience and localized processing capabilities.