What is the market overview and scope of the Electrical Steel Market?
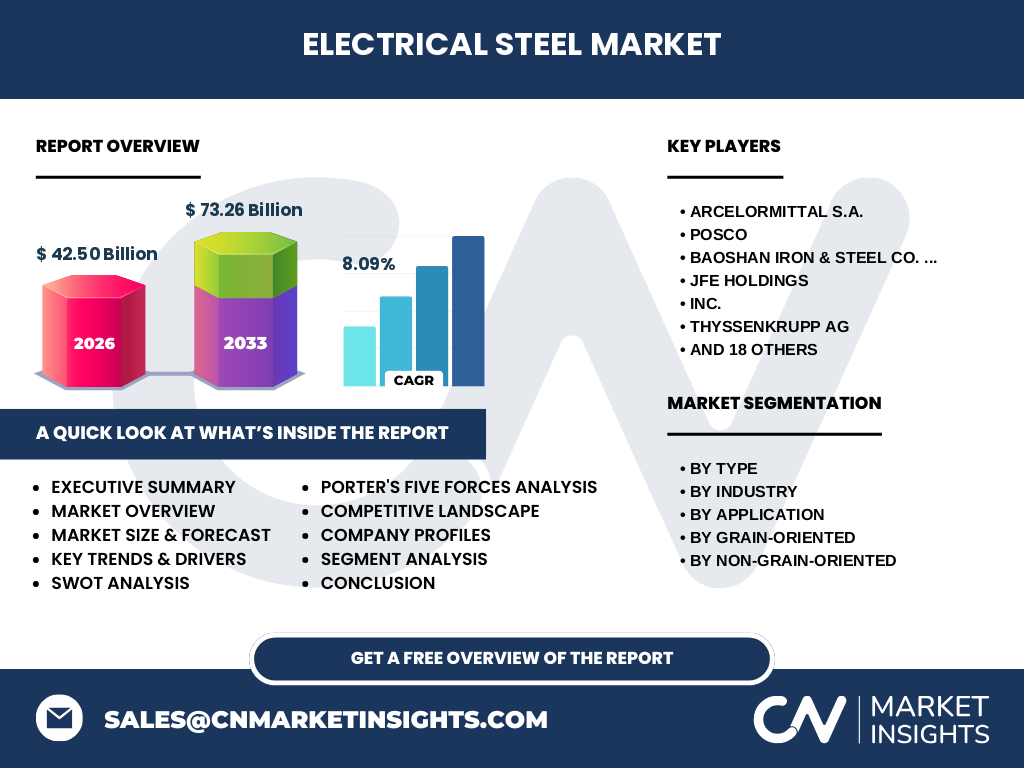
Our analysis indicates that the Electrical Steel Market is valued at 42.50 Billion in 2026, serving as the foundational magnetic core material for global power grids and electric vehicle drivetrains. This specialized specialty steel sector underpins efficiency standards mandated by agencies like the US Department of Energy, directly impacting electrical loss reduction across transformers, motors, and generators.
Structural Growth Drivers and Restraints in the Electrical Steel Market
Growth is aggressively propelled by renewable energy grid integration and EV adoption, yet constrained by strict metallurgical processing bottlenecks and raw material volatility in silicon and iron ore. POSCO and ArcelorMittal S.A. are navigating these supply constraints by scaling up high-permeability production lines to meet surging decarbonization targets set by global climate accords.
Emerging Trends and Technological Shifts
The market is witnessing an accelerated transition toward ultra-thin High-Performance Non-Grain-Oriented Steel to curb core losses at high frequencies. Major producers like Baoshan Iron & Steel Co. Ltd and JFE Holdings are heavily investing in laser-scribing technology to optimize domain refinement for next-generation EV traction motors.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic severely disrupted automotive supply chains and steel mill operations across Europe and Asia, causing temporary dips in production. However, post-pandemic stimulus packages focusing on green infrastructure sparked a robust V-shaped recovery, positioning the sector on a steep trajectory toward its 73.26 Billion valuation by 2033.
Competitive Benchmarking and Strategic Landscape
Market concentration remains moderately high, dominated by vertically integrated steel giants such as ThyssenKrupp AG, Cleveland-Cliffs Corporation, and Steel Authority of India Limited. Competitive advantage hinges on proprietary annealing techniques and securing long-term raw material supply contracts to insulate against geopolitical trade tariffs.
Executive Summary of Key Findings
Driven by robust decarbonization mandates, the Electrical Steel Market market size is projected to surge from 42.50 Billion in 2026 to 73.26 Billion by 2033, expanding at a remarkable CAGR of 8.09%. Strategic consolidation and technological pivoting toward grain-oriented grades represent the primary vectors for sustained profitability.
Long-Term Market Forecast from 2027 to 2033
Based on our research, the industry will maintain a strong CAGR of 8.09% throughout the forecast period, culminating in a market revenue of 73.26 Billion by 2033. This expansion is heavily underwritten by massive grid modernization projects in emerging economies and stringent international efficiency standards for industrial rotating equipment.
Detailed Segmentation Analysis
The Electrical Steel Market industry trends reveal deep bifurcation across multiple categories:
- By Type: Grain-Oriented and Non-Grain-Oriented.
- By Industry: Energy, Automotive, Household Appliances, Manufacturing, and Other Industries.
- By Application: Transformers, Generators, Motors, and Other Applications.
- By Grain-Oriented: Transformer Steel and Laminated Core Steel.
- By Non-Grain-Oriented: Regular and High-Performance Non-Grain-Oriented Steel.
Geographic Distribution and Regional Market Performance
Asia-Pacific dominates the global landscape, anchored by massive manufacturing hubs in China, Japan, and South Korea, closely tied to regional port logistics and massive grid expansions. Meanwhile, North America and Europe prioritize high-end grain-oriented upgrades to replace aging mid-century electrical infrastructure.
In-Depth Regional Review and Localized Constraints
Regional analysis highlights severe localized constraints in Europe due to stringent carbon border adjustment mechanisms (CBAM), forcing players like Bekaert SA and Suzuki Garphyttan Ab to adopt scrap-based electric arc furnace routes. Conversely, Asian markets benefit from streamlined supply chains near major export terminals.
Company Profiles and Strategic Positioning
Industry leaders leverage distinct competitive moats: ArcelorMittal S.A. focuses on global decarbonized footprint expansion, POSCO excels in high-end automotive traction steel, and Cleveland-Cliffs Corporation maintains dominance in domestic North American transformer supply chains. Niche players like Arnold Magnetic Technologies target specialized aerospace and defense applications.
Porter's Five Forces Analysis of the Sector
Bargaining power of suppliers is moderate-to-high due to the specialized nature of silicon raw inputs, while threat of substitutes remains exceptionally low given the unmatched magnetic properties of electrical steel. Competitive rivalry is intense among established tier-1 mills possessing proprietary rolling technologies.
SWOT Analysis of the Electrical Steel Market
Strengths include critical roles in green energy transition; Weaknesses involve high capital expenditure and energy-intensive manufacturing; Opportunities lie in emerging EV charging infrastructure; Threats stem from raw material price volatility and potential substitution by amorphous metals in niche transformer cores.
Value Chain Analysis from Raw Materials to End-Users
The value chain flows from raw iron ore, silicon, and carbon sourcing through sophisticated electric arc melting, hot rolling, cold reduction, and high-temperature batch annealing. Value is heavily captured at the advanced coating and slitting stages before distribution to transformer and motor manufacturers.
Investment Insights and High-Potential Areas
Our analysis indicates that capital allocation should target production lines dedicated to High-Performance Non-Grain-Oriented Steel and specialized transformer core laminations. Investors should monitor partnerships involving regional innovators like Mahindra Intertrade and Harsh Electrical Stampings for high-growth localized plays.
Conclusion and Strategic Takeaways
The Electrical Steel Market analysis confirms that technological agility and adherence to green manufacturing standards will separate market leaders from laggards. With the sector scaling toward 73.26 Billion by 2033, early investments in advanced metallurgical capabilities are paramount for stakeholders.
Research Methodology and Data Triangulation
Baseline estimates are rigorously triangulated by cross-referencing global trade registry data, primary stakeholder interviews with C-suite executives at firms like Nanning Hengjie Industrial Co., Ltd, and secondary macroeconomic indicators from international energy agencies to ensure unmatched accuracy in our Electrical Steel Market research.
Scope of the Report and Coverage Parameters
This report provides exhaustive global coverage of the Electrical Steel Market across all specified product types, applications, and end-user industries from 2026 to 2033. Limitations include unforeseen geopolitical trade shifts and sudden regulatory changes regarding industrial carbon emission caps.
Recent Developments and Strategic Industry Moves
Recent market dynamics feature aggressive joint ventures and capacity expansions, such as Ningbo BST Metal Products Co., Ltd upgrading its rolling facilities, and cross-border partnerships aimed at securing sustainable electrical steel supply for European EV manufacturing plants.