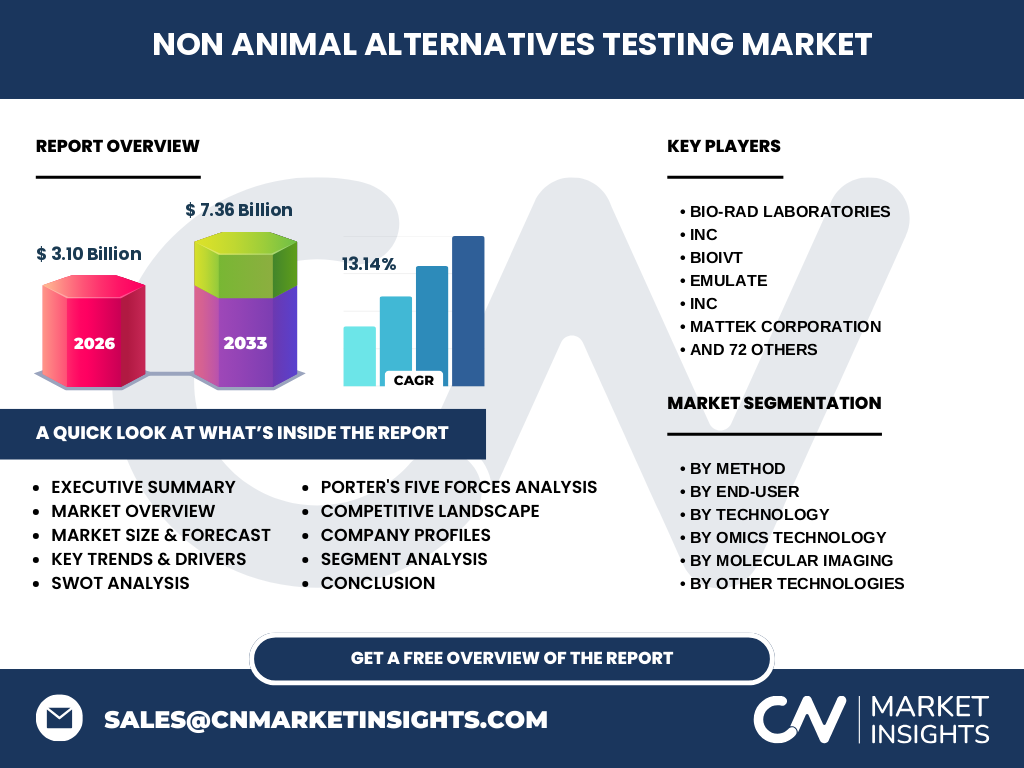
Market overview and structural scope of the Non-Animal Alternatives Testing Market
Our analysis indicates that the Non-Animal Alternatives Testing Market is valued at 3.10 Billion in 2026. This sector encompasses advanced methodologies like cellular assays, biochemical assays, and in silico modeling designed to replace traditional animal experimentation in pharmaceutical and chemical safety assessments.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Non-Animal Alternatives Testing Market industry trends?
Strict mandates from regulatory bodies like the FDA and EMA act as a primary driver, while high initial setup costs for complex platforms such as organ-on-a-chip models remain a key restraint. Opportunities abound for tech innovators integrating omics technology to improve predictive toxicology.
Emerging trends and technological growth patterns in the Non-Animal Alternatives Testing Market
The shift toward human-relevant testing systems is accelerating, particularly through the adoption of 3D cell cultures and high throughput technology. Companies like Emulate and Mimetas are pioneering advanced microfluidic platforms that simulate physiological responses more accurately than legacy animal models.
COVID-19 impact analysis and recovery trajectory for the Non-Animal Alternatives Testing Market analysis
The pandemic caused temporary supply chain disruptions for critical biological raw materials and cell culture reagents. However, the crisis ultimately accelerated the adoption of in silico and remote computational testing platforms, securing a robust post-pandemic recovery trajectory across the life sciences sector.
Competitive landscape and strategic dynamics in the Non-Animal Alternatives Testing Market
The market features a mix of specialized innovators and diversified life science giants. Industry leaders such as Thermo Fisher Scientific, Merck (EMD Millipore), and Charles River Laboratories are actively acquiring niche organ-on-a-chip and omics providers to fortify their non-animal assay portfolios.
Executive summary of key findings in the Non-Animal Alternatives Testing Market
Our research forecasts exponential expansion, projecting the market to surge from 3.10 Billion in 2026 to 7.36 Billion by 2033 at a notable CAGR of 13.14%. This growth is heavily underpinned by ethical shifts and stringent global regulations against animal testing in cosmetics and chemical safety.
Market forecast trajectory from 2027 to 2033
Driven by compounding investments in alternative methods, the sector is set to achieve a remarkable 13.14% CAGR, reaching 7.36 Billion by 2033. This trajectory reflects increasing commercial reliance on multiplexed assays and automated screening systems for rapid drug discovery pipelines.
Segmentation analysis across methods, technologies, and end-users
Segmentation spans multiple dimensions: by method (Cellular Assay, Biochemical Assay, In Silico, Ex-Vivo), technology (Omics, Molecular Imaging, Cell Culture), and end-user (Pharmaceutical, Cosmetics, Chemicals). The pharmaceutical industry dominates demand, utilizing these tools for early-stage pharmacokinetic screening.
Regional market distribution and geographic performance dynamics
North America and Europe currently dominate revenue share due to rigorous regulatory frameworks like the EU Cosmetics Regulation. Meanwhile, Asia-Pacific represents the fastest-growing frontier, propelled by expanding pharmaceutical research hubs in Japan, China, and India adopting advanced transcriptomics.
In-depth regional review of key geographic markets
European adoption is heavily enforced by legislative bans on animal-tested cosmetics, forcing local contract research organizations to transition rapidly. In North America, heavy funding from agencies like NIH into microfluidics technology drives rapid commercialization of complex human cell models.
Company profiles and strategic positioning of leading market participants
Key players like MatTek Corporation specialize in 3D human tissue models, while firms such as Cyprotex and Gentronix Limited provide specialized in vitro and genetic toxicity screening services. Their strategic focus centers on expanding assay throughput and physiological relevance.
Porter's Five Forces analysis of the Non-Animal Alternatives Testing Market
The threat of new entrants is moderate to high due to low barriers for software-based in silico startups, though wet-lab tissue engineering requires heavy capital. Buyer power is substantial among large pharmaceutical firms, driving vendors to offer highly customized genomics and proteomics services.
SWOT analysis evaluating sector strengths, weaknesses, opportunities, and threats
Strengths include high predictive accuracy and ethical compliance. Weaknesses involve complex standardization hurdles. Opportunities lie in personalized medicine screening, while threats stem from potential validation bottlenecks by regulatory bodies hesitant to fully phase out legacy animal protocols.
Value chain analysis from raw materials to end-users
The value chain begins with raw material providers supplying specialized cell culture media and biochemical reagents. Mid-stream technology developers integrate these into automated screening platforms, which are ultimately deployed by contract research organizations and pharmaceutical end-users for toxicology profiling.
Investment insights and high-potential areas for capital allocation
High-potential investment pockets include companies specializing in metabolomics data analytics and multi-organ microfluidic platforms. Investors should prioritize firms demonstrating strong cross-sector validation data that satisfy both pharmaceutical and chemical safety regulations.
Conclusion and core strategic takeaways
The Non-Animal Alternatives Testing Market represents a transformative shift in life sciences, driven by a 13.14% CAGR toward 7.36 Billion by 2033. Stakeholders must embrace multi-technology integration—combining in silico modeling with 3D cell cultures—to capture maximum market share.
Research methodology and data triangulation framework
Our baseline estimates are rigorously triangulated by combining secondary macroeconomic indicators, exhaustive trade registry data, and primary stakeholder interviews with C-level executives across leading testing laboratories, regulatory affairs experts, and pharmaceutical R&D heads.
Scope of the report and analytical boundaries
This report covers global revenue performance, segment breakdowns, and competitive benchmarking from 2026 to 2033. Limitations include inherent macroeconomic volatilities and varying regional speeds in adopting non-animal regulatory frameworks across developing economies.
Recent developments, strategic partnerships, and product launches
Recent industry momentum features prominent collaborations between organ-on-a-chip innovators and major pharmaceutical corporations aimed at streamlining clinical trial attrition rates. Furthermore, strategic acquisitions of bioinformatics startups by major life science conglomerates highlight an industry-wide consolidation trend.