What is the market overview of the Inventory Management Software Market?
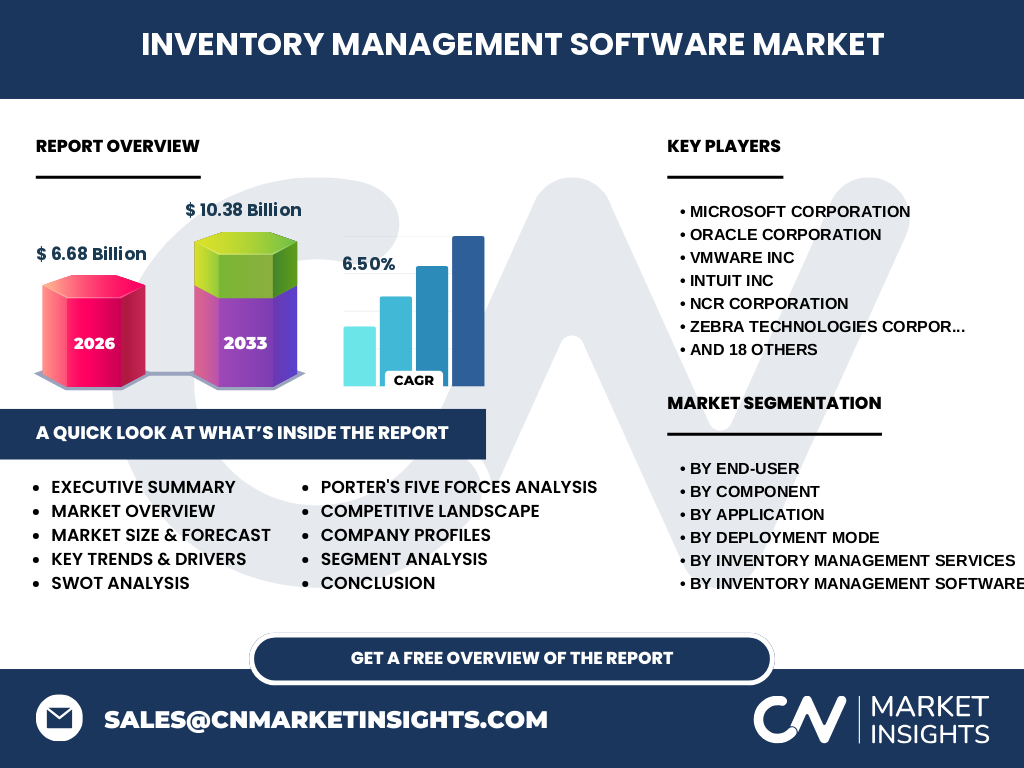
Our analysis indicates the Inventory Management Software Market valuation reaches $6.68 Billion in 2026. This sector encompasses critical solutions for raw material tracking, finished goods oversight, and regulatory compliance across complex supply chains.
Key market drivers, restraints, challenges, and opportunities shaping Inventory Management Software Market
Primary growth drivers include supply chain volatility and stringent FDA/GSI compliance mandates. Conversely, high implementation costs restrain smaller enterprises. The primary opportunity lies in integrating IoT sensors with solutions from Zebra Technologies Corporation and SAP SE.
Emerging trends and growth patterns in Inventory Management Software Market
The shift toward cloud deployment and real-time RFID tracking dominates Inventory Management Software Market industry trends. Enterprises increasingly demand mobile-first applications to mitigate labor shortages in major distribution hubs and maritime ports.
COVID-19 impact analysis on the Inventory Management Software Market
The pandemic exposed severe supply chain fragility, forcing organizations to accelerate digital transformation. Based on our research, this disruption catalyzed rapid recovery, elevating cloud adoption to prevent future stockouts across global manufacturing networks.
Competitive Benchmarking and Market Concentration
The competitive landscape features heavyweight innovators like Oracle Corporation, Microsoft Corporation, and Infor, alongside specialized players such as Fishbowl Manufacturing and Cin7 Ltd. Market concentration remains moderately fragmented among SMB solutions.
Executive Summary: High-Level Synthesis of Key Findings
The Inventory Management Software Market market size is set for expansion, driven by omnichannel retail pressures. Strategic agility and cloud migration represent the core differentiators for market leaders navigating macroeconomic headwinds.
Market forecast for the Inventory Management Software Market from 2027 to 2033
Our projections show the market expanding to $10.38 Billion by 2033, exhibiting a robust CAGR of 6.50% from 2027. This growth trajectory reflects surging demand for automated stock replenishment and predictive analytics.
Segmentation analysis across end-users, components, and applications
The market segments by end-user into Manufacturing, Retail, Healthcare, Energy, and Automotive. Component breakdown includes Software and Services. Application categories span Order Management, Asset Tracking, Services Management, Product Differentiation, and Inventory Optimization.
Regional market analysis and geographic distribution
Geographic performance highlights North America as the revenue leader, supported by advanced retail infrastructures. Meanwhile, Asia-Pacific exhibits the fastest adoption rate due to expanding manufacturing ecosystems in Southeast Asia and robust logistics hubs.
In-depth regional review of key markets
North America benefits from early cloud technology adoption and strict FDA tracking rules in healthcare. Europe follows closely, driven by stringent sustainability regulations impacting reverse logistics and warehousing waste reduction initiatives.
Company profiles and strategic positioning of leading innovators
Industry leaders leverage distinct advantages: SAP SE and Oracle Corporation dominate enterprise ERP-integrated inventory, while Zoho Corporation Pvt Ltd and QuickBooks Commerce target agile small businesses with scalable, user-friendly SaaS platforms.
Porter's Five Forces analysis of competitive pressures
Rivalry is intense due to numerous SaaS vendors. Supplier power remains low given abundant cloud infrastructure providers, while buyer power is high because of low switching costs among entry-level inventory platforms.
SWOT analysis of the Inventory Management Software Market
Strengths include high scalability of cloud systems. Weaknesses involve integration friction with legacy ERPs. Opportunities center on AI-driven forecasting, while threats stem from rising cybersecurity vulnerabilities in interconnected warehouse networks.
Value chain analysis from raw materials to end-users
The value flow originates with raw material suppliers feeding component data into software engines, passing through cloud hosting providers, value-added resellers, and concluding with end-users optimizing warehouse picking efficiency.
Investment insights and high-potential areas
Investors should target niche providers offering mobile-first barcode and RFID capabilities. Companies addressing healthcare serialization and automated stock replenishment present the highest risk-adjusted return potential.
Conclusion and key takeaways for stakeholders
Sustained growth through 2033 underscores the transition from basic record-keeping to intelligent supply chain orchestration. Stakeholders must prioritize cloud scalability and advanced analytics integration to maintain competitive differentiation.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level supply chain executives, trade registry filings, and secondary macroeconomic indicators from global trade organizations.
Scope of the report and coverage parameters
This report covers global software deployments across six primary end-user verticals, evaluating cloud and on-premise solutions. Limitations exclude bespoke proprietary inventory systems built internally by Fortune 500 enterprises.
Recent developments in corporate strategy and product launches
Recent strategic moves feature Acumatica Inc. enhancing its distribution edition with AI forecasting, and Manhattan Associates Inc. forging partnerships to optimize omnichannel fulfillment routing across international ports.