What is the scope and industry significance of the Dark Store Market?
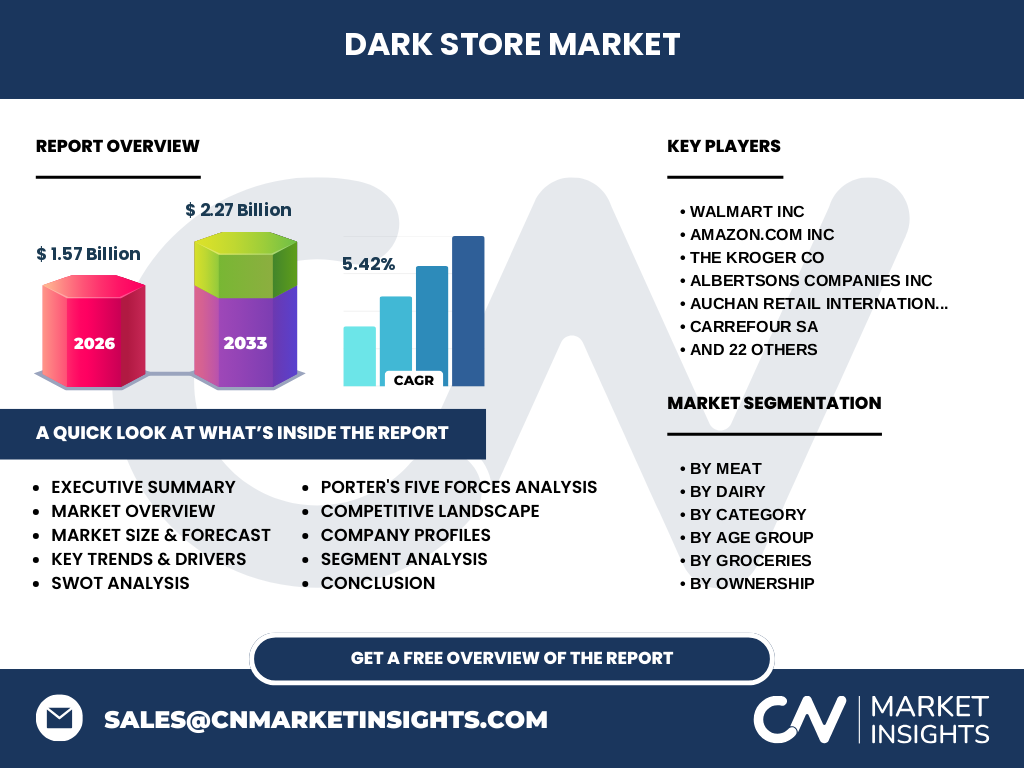
Our analysis indicates that the Dark Store Market represents a fundamental restructuring of urban retail logistics, featuring micro-fulfillment hubs optimized exclusively for digital orders rather than walk-in shoppers. Operating with a projected 2026 market size of $1.57 Billion, these facilities integrate high-density inventory racking with automated conveyor systems to drastically compress last-mile delivery windows across dense metropolitan environments.
Structural Growth Drivers and Restraints
The sector's trajectory is propelled by surging consumer demand for hyper-convenience, offset by severe zoning restrictions and municipal pushback regarding urban traffic congestion. High real estate acquisition costs in core city centers act as a primary constraint, forcing operators to optimize spatial layouts utilizing vertical storage infrastructure to maximize revenue per square foot.
Emerging Trends in Micro-Fulfillment
A defining shift involves the integration of predictive artificial intelligence for automated stock replenishment and micro-zoning of perishable goods like fresh produce. Industry leaders are deploying dark-store-as-a-service models, allowing traditional grocers such as The Kroger Co and Ahold Delhaize to scale digital capacity without constructing dedicated physical facilities from scratch.
COVID-19 Impact Analysis and Recovery Trajectory
The pandemic served as an unprecedented catalyst, forcing rapid deployment of contact-free fulfillment networks as lockdown mandates halted traditional retail operations. While initial hyper-growth has normalized, the market has established a resilient recovery trajectory, cementing quick-commerce behaviors permanently into post-pandemic consumer routines across global metropolitan hubs.
Competitive Benchmarking and Market Concentration
The competitive landscape features intense rivalry among specialized quick-commerce disruptors and legacy supermarket chains scaling digital infrastructure. Key participants like Getir, Gorillas, and Instacart compete aggressively on delivery speed, while traditional giants leverage extensive supply chain networks to capture sustainable long-term market share.
Executive Summary of Key Findings
Our comprehensive report reveals a robust market expansion driven by surging digital commerce adoption. The Dark Store Market is poised to achieve consistent growth, reaching $2.27 Billion by 2033 at a steady CAGR of 5.42% from 2027 onward, underlining the permanent viability of localized micro-fulfillment infrastructure.
Market Forecast Projections from 2027 to 2033
Driven by compounding urbanization and refinement of automated picking technologies, the market will expand from its 2026 baseline of $1.57 Billion to reach $2.27 Billion by 2033. This expansion represents a steady CAGR of 5.42%, reflecting maturing operational models and enhanced unit economics across tier-one cities.
Segmentation Analysis of the Fulfillment Ecosystem
The ecosystem is categorized across multiple dimensions to capture operational nuances. By category, it spans groceries and fresh proteins. The grocery sector is further divided into packaged foods, beverages, fresh produce, and frozen foods, while meat segments encompass poultry, beef, pork, and seafood. Dairy segments include milk alternatives, cheese, yogurt, and butter. Target demographics cover children, adults, and elderly populations, served via independently owned and chain-owned dark stores utilizing in-store pickup, curbside pickup, and home delivery channels.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, dictated by urban density, municipal zoning laws, and local labor costs. Western Europe and North America currently dominate revenue generation due to high smartphone penetration and dense urban populations, whereas Asia-Pacific markets exhibit the fastest adoption rates propelled by hyper-dense residential infrastructure.
In-Depth Regional Review
North American urban centers face strict zoning hurdles, prompting operators to locate micro-fulfillment centers in secondary commercial districts. Conversely, European markets experience intense competition governed by stringent labor regulations, forcing rapid adoption of automated picking solutions by major players like Tesco PLC and Carrefour SA to maintain operational margins.
Company Profiles and Strategic Positioning
Market leaders exhibit diverse strategic approaches to capture urban demand. Walmart Inc and Amazon.com Inc leverage massive balance sheets and integrated logistics networks, while dedicated quick-commerce operators like Zepto, Gopuff, and Wolt Enterprises Oy focus on ultra-fast fulfillment windows and hyper-localized inventory management.
Porter's Five Forces Analysis
Competitive rivalry remains intense due to low differentiation among rapid delivery apps, while supplier power is moderated by the vast purchasing scale of supermarket chains like Costco Wholesale Corporation and Coles Group Limited. The threat of substitution is low, but the threat of new entrants persists through niche local grocery startups.
SWOT Analysis of the Fulfillment Sector
Key strengths lie in unmatched delivery speed and proximity to urban consumers, countered by weaknesses in high initial capital expenditures and thin delivery margins. Opportunities abound in tier-two city expansion and automated picking integration, while regulatory crackdowns on delivery rider safety pose critical ongoing threats.
Value Chain Analysis from Sourcing to End-User
The value chain originates with agricultural producers and FMCG manufacturers supplying centralized distribution hubs, which then restock localized dark stores. The final link utilizes sophisticated routing software and gig-economy delivery fleets managed by firms like Deliveroo and Swiggy to execute final handoff to the end consumer.
Investment Insights and High-Potential Areas
Investors should direct capital toward software solutions optimizing automated pick-and-pack workflows and temperature-controlled storage for perishable dairy and seafood categories. High-potential opportunities exist in partnering with established retail chains such as Ahold Delhaize and Woolworths Group Limited to retrofit existing underutilized urban real estate.
Conclusion and Strategic Takeaways
The Dark Store Market is transitioning from a venture-funded growth experiment into a disciplined, margin-focused logistics sector. Achieving profitability requires operators to master automated inventory forecasting, reduce last-mile delivery costs, and strategically align with retail giants to secure long-term viability through 2033.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining official trade registry data, financial filings of publicly traded entities like Ocado Group plc and J Sainsbury PLC, primary stakeholder interviews with supply chain directors, and secondary macroeconomic indicators tracking urban real estate pricing and e-commerce penetration rates.
Scope of the Report and Coverage Parameters
This report evaluates the global Dark Store Market across specified categories, ownership models, and distribution channels, focusing on commercial facilities dedicated entirely to digital order processing. Excluded from this scope are traditional brick-and-mortar storefronts that process online orders from customer-facing retail sales floors.
Recent Industry Developments and Strategic Partnerships
Recent market activity is characterized by strategic consolidation and technological joint ventures. Major platforms, including Flink SE and Rappi, have formed logistics alliances with traditional grocery conglomerates to share fulfillment infrastructure, reduce overhead expenses, and accelerate expansion into suburban residential catchments.