What is the market overview and industry significance of the Non-Ferrous Scrap Recycling Market?
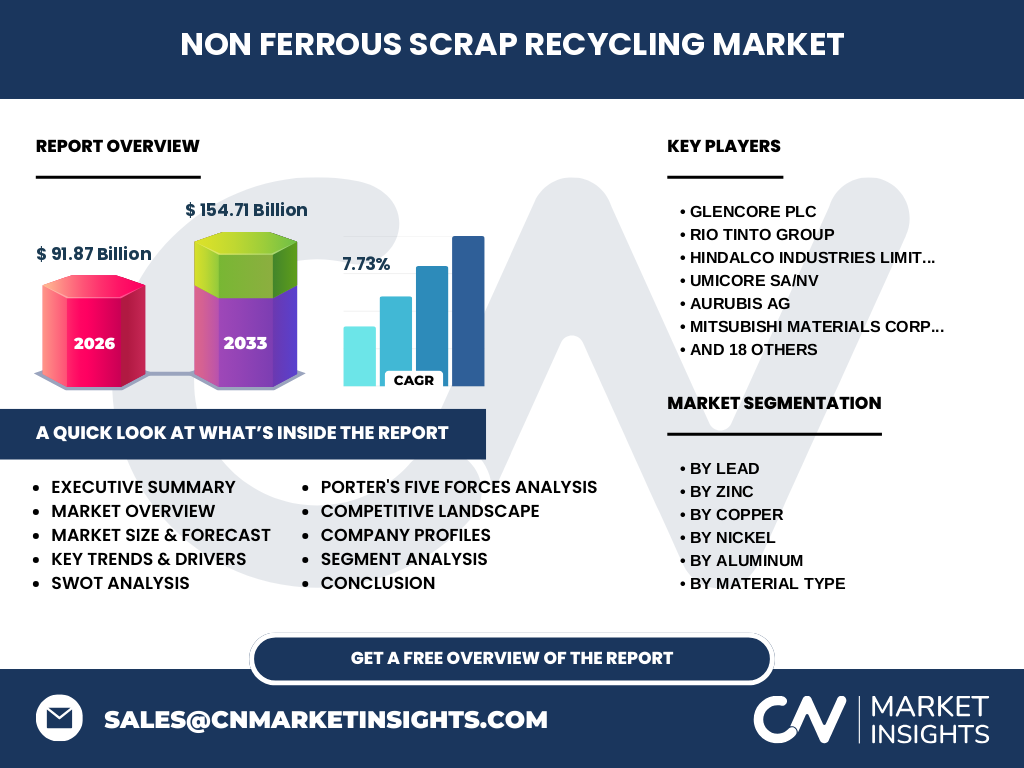
Our analysis indicates that the Non-Ferrous Scrap Recycling Market is valued at $91.87 Billion in 2026. This sector holds critical industrial significance by processing high-value materials like aluminum, copper, and nickel, reducing reliance on primary extraction and mitigating supply chain bottlenecks for critical infrastructure and manufacturing sectors worldwide.
Structural Growth Drivers and Market Restraints
The market is propelled by stringent environmental regulations from bodies like the EPA and EU directives, paired with volatile primary metal pricing. However, logistical hurdles in scrap collection and contamination issues in post-consumer streams act as notable restraints, forcing operators to invest heavily in advanced sorting technologies.
Emerging Trends Shaping the Sector
The shift toward closed-loop recycling programs and the adoption of AI-driven X-ray fluorescence (XRF) sorting are redefining operational efficiencies. Major processors like Aurubis AG and Glencore plc are increasingly integrating hydrometallurgical techniques to recover high-purity battery-grade materials from complex electronic scrap.
COVID-19 Impact Analysis and Recovery Trajectory
Pandemic-induced industrial shutdowns temporarily paralyzed scrap generation across automotive and construction end-use segments. Robust post-pandemic stimulus measures and aggressive decarbonization targets rapidly accelerated recovery, positioning the market on a steep expansion path toward projected valuations.
Competitive Landscape and Strategic Dynamics
Market concentration is moderately fragmented, featuring global giants such as Rio Tinto Group, Umisore SA/NV, and Sims Limited competing alongside specialized regional processors. Strategic alliances with automotive OEMs ensure secure, captive feedstock streams for secondary aluminum and copper production.
Executive Summary of Key Findings
Our comprehensive assessment highlights a robust expansion trajectory, driven by circular economy mandates and surging electrification demands. The Non-Ferrous Scrap Recycling Market is projected to reach $154.71 Billion by 2033, expanding at a robust CAGR of 7.73% from 2027.
Market Forecast from 2027 to 2033
Driven by accelerating EV adoption and renewable energy infrastructure deployment, the market will scale from its 2026 baseline of $91.87 Billion to reach $154.71 Billion by 2033. This growth represents a steady compound annual growth rate of 7.73% over the forecast period.
Segmentation Analysis of Non-Ferrous Scrap
The market breaks down across material types including Aluminum, Copper, Lead, Nickel, and Zinc. Sources span industrial, post-consumer, construction, aerospace, automotive, and electrical scrap, processed via mechanical, pyrometallurgical, or hydrometallurgical recycling to supply demanding end-use manufacturing sectors globally.
Regional Market Analysis and Geographic Distribution
Geographically, industrialization and stringent carbon reduction mandates dictate regional performance. Asia-Pacific dominates volume consumption driven by electronics manufacturing, while North America and Europe prioritize advanced automated sorting infrastructure to meet strict Basel Convention compliance and domestic remelting requirements.
In-Depth Regional Review
Europe maintains leadership in regulatory enforcement regarding end-of-life vehicles, directly benefiting regional players like European Metal Recycling Limited (EMR) and Boliden AB. Meanwhile, North American markets experience high scrap generation from robust automotive and aerospace manufacturing hubs.
Company Profiles and Strategic Positioning
Key industry participants leverage distinct operational footprints. Hindalco Industries Limited and Commercial Metals Company focus on integration with primary smelting, whereas Sims Limited and Remondis SE & Co. KG specialize in global municipal and industrial waste collection networks.
Porter's Five Forces Analysis
Bargaining power of suppliers is moderate due to fragmented scrap generation sources, while buyer power is high among major metal consumers. Threat of substitution remains low due to mandatory recycled content laws, though high capital requirements for sorting plants effectively limit new entrant threat.
SWOT Analysis of the Industry
Strengths include established global logistics networks and high material recovery rates. Weaknesses involve high energy consumption during pyrometallurgical processing. Opportunities lie in secondary battery metal recovery, while threats stem from international trade policy shifts and scrap export restrictions.
Value Chain Analysis from Source to End-User
The value flow begins at diverse collection points—ranging from Automotive Scrap to Electrical Scrap—moving through shredding, sorting, and upgrading by firms like Trafigura Group Pte. Ltd. before reaching end-use foundries and mills for high-grade alloy production.
Investment Insights and High-Potential Areas
Strategic investments should target advanced sensor-based sorting technologies and hydrometallurgical recycling facilities. Companies focusing on nickel and lithium-ion battery scrap recovery present exceptional alpha generation potential as EV production scales exponentially through 2033.
Conclusion and Key Takeaways
The Non-Ferrous Scrap Recycling Market transitions from a waste management function into a vital pillar of the critical mineral supply chain. Achieving a valuation of $154.71 Billion by 2033 underscores the immense commercial imperative for technological modernization and strategic feedstock acquisition.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary executive interviews with key stakeholders at firms like Matalco Inc. and Steel Dynamics Inc., and secondary macroeconomic indicators regarding global metal demand and industrial output.
Scope of the Report and Coverage Parameters
This report covers global market dynamics for non-ferrous scrap across five primary material categories and six distinct recycling processes. Limitations include confidential private company financials and localized informal sector data which are estimated via econometric modeling.
Recent Developments and Strategic Moves
Recent market activities feature major capacity expansions and joint ventures in battery recycling. Companies like Umicore SA/NV and Dowa Holdings Co. Ltd. have announced strategic partnerships to secure long-term automotive shredder residue and electronic scrap supply contracts.