Market overview and industry significance of the Hydrogen Plants Market
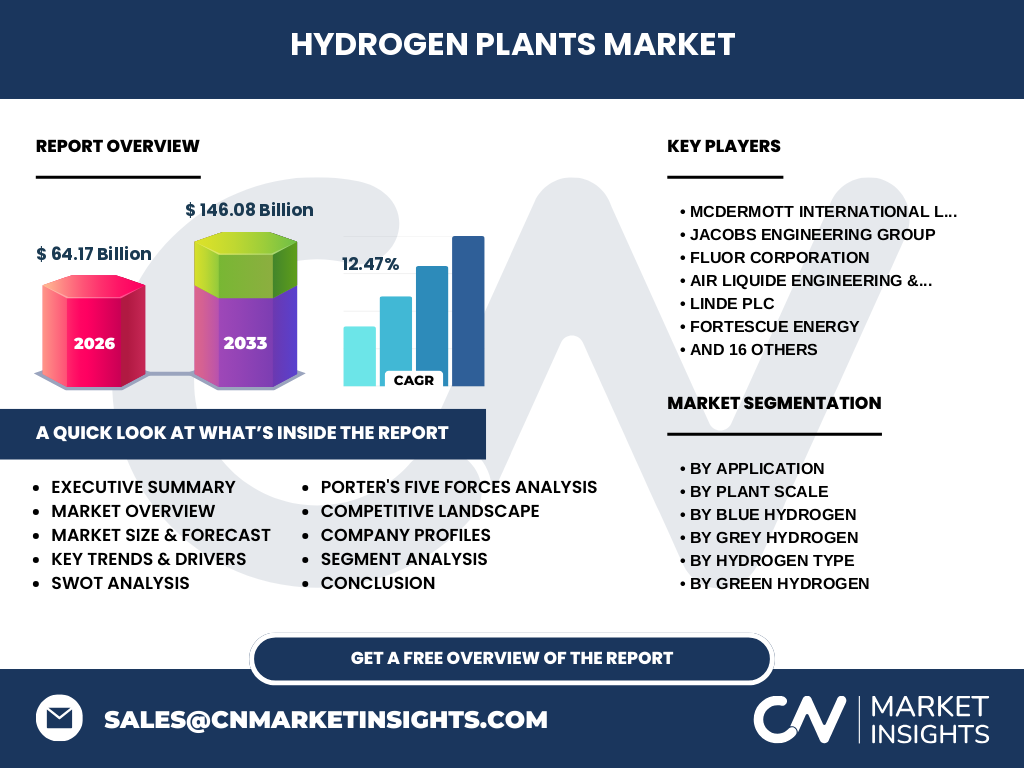
Our analysis indicates the Hydrogen Plants Market size stands at $64.17 Billion in 2026, serving as the foundational infrastructure for global decarbonization. This sector encompasses capital-intensive facilities utilizing steam methane reforming, water electrolysis, and coal gasification to supply low-carbon and industrial gas feedstocks for petroleum refining, green steel manufacturing, and heavy chemical synthesis.
Structural Growth Drivers and Market Restraints
The market is propelled by stringent net-zero mandates from regulatory bodies like the European Union and the U.S. Department of Energy. However, high capital expenditure for carbon capture retrofits and electrolyzer stacks acts as a primary restraint. Supply chain bottlenecks for critical raw materials such as iridium and platinum further constrain rapid capacity expansion across major industrial hubs.
The Shift Toward Low-Carbon Industrial Processes
Emerging growth patterns highlight a massive pivot toward Green Hydrogen and Blue Hydrogen production facilities. Industrial operators are systematically phasing out unabated grey hydrogen. Companies leveraging proton exchange membrane electrolysis and autothermal reforming with carbon capture are capturing dominant market share as buyers demand certified low-carbon feedstock.
COVID-19 Impact Analysis and Pandemic Recovery Trajectory
The pandemic severely disrupted global supply chains, delaying engineering, procurement, and construction schedules for large-scale hydrogen plants. Post-pandemic recovery has been heavily stimulated by aggressive government fiscal packages, such as the U.S. Inflation Reduction Act, accelerating project pipelines and driving unprecedented capital deployment across the entire hydrogen value chain.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape features a blend of traditional engineering giants and pure-play clean energy innovators. Industry leaders like Linde plc, Air Liquide Engineering & Construction, and Technip Energies N.V. dominate through proprietary technological know-how in SMR and cryogenic separation, while firms like Nel ASA and ITM Power scale up modular water electrolysis units.
Executive Summary of the Hydrogen Plants Market
Our comprehensive evaluation confirms the Hydrogen Plants Market is undergoing a generational transformation. Driven by heavy industry decarbonization requirements, the market is poised for massive expansion, presenting lucrative opportunities for technology providers, EPC contractors, and project developers positioned at the intersection of energy transition and industrial gas production.
Market Forecast and Long-Term Trajectory from 2027 to 2033
Based on our research, the Hydrogen Plants Market is projected to surge from $64.17 Billion in 2026 to reach $146.08 Billion by 2033, expanding at a robust CAGR of 12.47%. This accelerated growth trajectory reflects expanding commercial-scale deployments and decreasing levelized costs of production.
Segmentation Analysis Across Technology and Application
The market bifurcates across critical operational vectors: By Application (Industrial, Energy Sector, Transportation, Residential and Commercial Heating); By Plant Scale (Small, Medium, and Large-Scale); and By Production Method (Steam Methane Reforming, Electrolysis, Thermochemical, Biological). Large-scale SMR with carbon capture and advanced alkaline water electrolysis plants represent the highest revenue-generating segments.
Regional Market Analysis and Geographic Distribution
Geographic performance varies significantly, with Europe leading in green hydrogen adoption driven by the European Green Deal. Meanwhile, North America accelerates through tax credits, and the Asia-Pacific region, anchored by heavy industrial demand in China and South Korea, dominates grey and blue hydrogen capacity additions alongside emerging large-scale green export hubs.
In-Depth Regional Review of Key Production Hubs
Regional execution is heavily dictated by local feedstock availability and pipeline infrastructure. The Middle East leverages cheap natural gas and solar power for competitive blue and green hydrogen projects. Simultaneously, European ports like Rotterdam act as critical import terminals, shaping logistics networks for global hydrogen trade and bunkering operations.
Company Profiles and Strategic Positioning
Market participants deploy distinct growth strategies. EPC heavyweights like McDermott International Ltd, Fluor Corporation, and Jacobs Engineering Group secure mega-projects through integrated EPC execution. Pure-play electrolyzer developers like HydrogenPro and Fortescue Energy focus on gigawatt-scale manufacturing capacity to capture surging green energy demand.
Porter's Five Forces Analysis of the Hydrogen Sector
The industry exhibits high capital intensity, creating substantial barriers to entry for new merchant plant developers. Bargaining power of suppliers is moderate-to-high for specialized catalysts and electrolyzer stacks, while buyer power remains constrained by long-term offtake agreements required to finance multi-billion-dollar production facilities.
SWOT Analysis of the Hydrogen Plants Industry
Strengths lie in advanced process engineering and supportive policy frameworks. Weaknesses include high initial capital expenditure and intermittent renewable power supply for electrolysis. Opportunities abound in maritime bunkering and steel decarbonization, whereas threats involve regulatory uncertainty and delays in hydrogen pipeline grid buildouts.
Value Chain Analysis from Raw Materials to End-Users
The value chain originates with raw material extraction—such as natural gas, coal, and critical minerals for catalysts—flowing through specialized engineering firms like Topsoe, KBR Inc., and Hatch Ltd. It culminates at industrial end-users in oil refining, chemical processing, and green steel manufacturing via high-pressure pipelines or cryogenic tankers.
Investment Insights and High-Potential Strategic Areas
Our analysis indicates that high-potential investment clusters reside in localized hydrogen valleys and industrial clusters utilizing shared carbon capture infrastructure. Investors should prioritize partnerships with established EPC firms such as Wood Group PLC and Black & Veatch Holding Company to mitigate project execution and technology integration risks.
Conclusion and Key Takeaways for Market Stakeholders
The Hydrogen Plants Market represents a critical pillar of the global energy transition. With a forecasted market size of $146.08 Billion by 2033, success requires strategic alignment with low-carbon mandates, robust supply chain partnerships, and early adoption of modular, scalable plant architectures designed for future demand surges.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by synthesizing proprietary trade registry data, primary stakeholder interviews with executives at firms like Nel ASA and Air Liquide, and secondary macroeconomic indicators from international energy agencies. This multi-layered approach ensures precise market sizing and growth forecasting.
Scope of the Report and Coverage Parameters
This report covers global production facilities across five primary hydrogen types, categorized by plant scale, production methodology, and end-user application. Geographic analysis spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, explicitly focusing on commercial merchant and captive hydrogen generation assets.
Recent Developments, Partnerships, and Strategic Moves
Recent industry momentum is characterized by strategic joint ventures between energy majors and technology providers. Collaborations involving firms like ACWA Power, Aker Solutions, and Splitwaters highlight a concerted effort to co-develop gigawatt-scale green hydrogen and green ammonia facilities to service international offtake markets.