What is the structural definition and economic scope of the Arts Market?
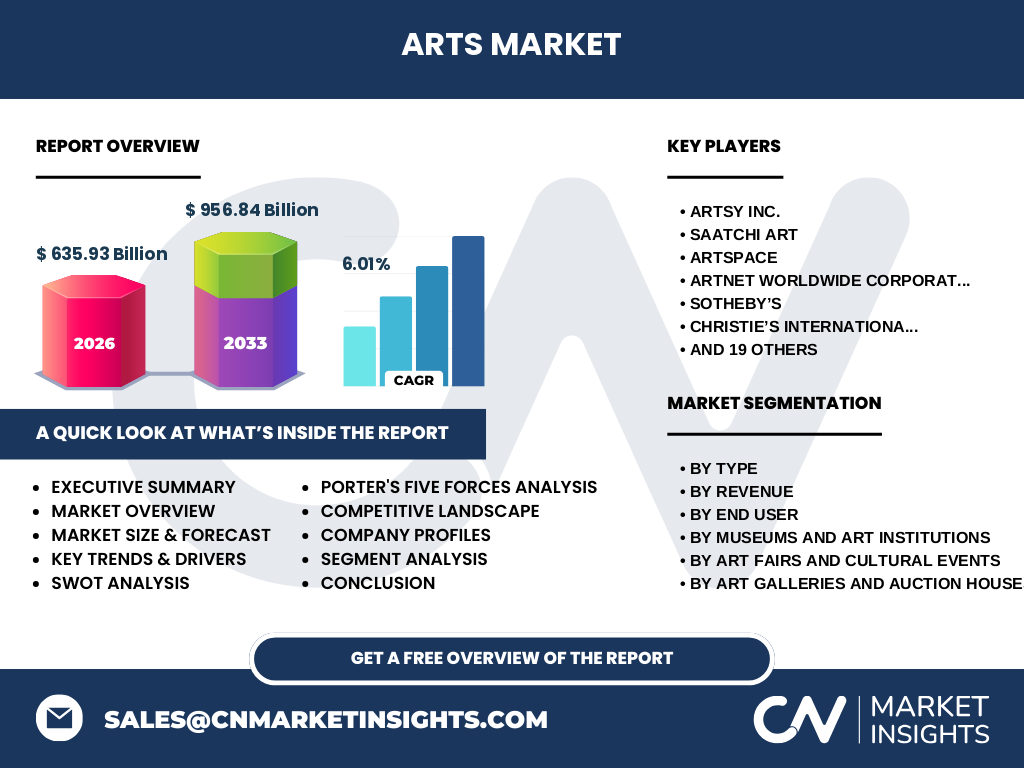
Our analysis indicates that the Arts Market is valued at 635.93 Billion in 2026. This dynamic sector encompasses museums, independent artists, auction houses, and digital platforms navigating complex logistical frameworks for high-value physical logistics and cultural preservation standards globally.
Key market drivers, restraints, challenges, and opportunities shaping the Arts Market
Growth is propelled by digital art adoption and cross-border e-commerce, while high shipping costs and strict cultural export regulations act as primary restraints. Industry players face significant logistical hurdles in secure fine art transit, creating monetization opportunities via fractional ownership and blockchain-backed provenance.
The Shift Toward Digital Infrastructure and Emerging Industry Trends
The landscape is experiencing a structural pivot toward virtual showrooms and decentralized platforms. Digital-first curators and online marketplaces are democratizing access, forcing traditional brick-and-mortar institutions to modernize their digital inventory management systems to capture younger, digitally native demographics.
COVID-19 impact analysis and pandemic recovery trajectory in the Arts Market
The pandemic drastically accelerated the transition to virtual viewing rooms and online auctions. While physical foot traffic plummeted, digital resilience allowed agile participants to sustain revenue streams, paving the way for a robust post-pandemic recovery characterized by hybrid physical-digital engagement models.
Competitive Benchmarking and Strategic Dynamics
Market concentration varies widely across tiers. Elite auction houses like Sotheby's and Christie's International PLC dominate high-end physical sales, whereas agile platforms like Artsy Inc., Saatchi Art, and Singulart capture the mid-market and emerging collector segments through innovative recommendation algorithms.
Executive Summary: High-Level Synthesis of Key Findings
Our comprehensive research confirms a thriving ecosystem projected to reach 956.84 Billion by 2033. Driven by a solid CAGR of 6.01% from 2027 to 2033, stakeholder success increasingly depends on seamless omnichannel integration, robust digital provenance verification, and targeted monetization strategies.
Market Forecast and Long-Term Growth Projections (2027 to 2033)
The Arts Market market size is projected to expand robustly from 635.93 Billion in 2026 to reach 956.84 Billion by 2033. This trajectory represents a steady compound annual growth rate of 6.01%, fueled by rising disposable incomes and expanding digital art consumption across emerging economies.
Comprehensive Segmentation Analysis of the Sector
The sector breaks down by type into Museums And Art Institutions, Independent Visual And Performing Artists, Art Galleries And Auction Houses, and Art Fairs And Cultural Events. Revenue streams flow through Media Rights, Merchandising, Tickets, and Sponsorship, serving both Individual and Corporate end users.
Regional Market Analysis and Geographic Performance
Geographic distribution reveals distinct performance metrics. North America and Europe currently command the largest share of transactional volume, supported by established institutional frameworks, while the Asia-Pacific region demonstrates the fastest regional growth rate driven by emerging contemporary collector hubs.
In-Depth Regional Review of Key Geographic Markets
Western European markets remain anchored by historic institutional prestige and major cultural capitals, whereas North American hubs lead in online gallery adoption and venture-backed art tech innovations. Meanwhile, localized regulatory constraints in Asia require tailored compliance strategies for international auction houses entering new territories.
Strategic Positioning and Company Profiles of Leading Entities
Market leaders deploy highly differentiated strategies. Sotheby’s and Christie’s leverage elite global prestige for high-ticket physical auctions, whereas platforms like Artnet Worldwide Corporation provide vital data analytics, and curated marketplaces like 1stdibs.com, Inc. and Minted LLC capture diverse consumer segments.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers is moderate to high due to price transparency online, while supplier power among top-tier artists remains elevated. The threat of substitution is low for authenticated masterworks but high for mass-produced decor, intensifying competitive rivalry among digital art marketplaces.
SWOT Analysis of the Global Arts Market
Strengths include rich cultural heritage and high-net-worth investor interest, balanced against weaknesses like illiquidity and opaque pricing. Opportunities lie in digital fractionalization and emerging Asian wealth, while threats involve macroeconomic downturns, tightening anti-money laundering regulations, and complex cross-border logistics.
Value Chain Analysis: From Raw Materials to End-Users
The value chain originates with raw material suppliers providing pigments and canvases to artists, progresses through galleries, curators, and auction houses handling logistics and valuation, and ultimately delivers value to individual collectors, corporate buyers, and institutional repositories through exhibitions and digital storefronts.
Investment Insights and High-Potential Strategic Areas
Investors should focus on art-tech infrastructure, digital provenance verification protocols, and platforms bridging emerging artists with global buyers. Companies possessing proprietary logistics networks and advanced data analytics capabilities offer superior risk-adjusted returns within this expanding valuation landscape.
Conclusion and Strategic Takeaways for Industry Stakeholders
Navigating the Arts Market industry trends requires embracing digital transformation without abandoning physical curation. Stakeholders who successfully integrate data-driven valuation tools with traditional gallery prestige will capture disproportionate market share as the sector scales toward 956.84 Billion by 2033.
Research Methodology and Data Triangulation Protocols
Our baseline estimates are rigorously triangulated by combining customs trade registry data, primary stakeholder interviews with gallery owners and auctioneers, and secondary macroeconomic indicators from cultural ministries to ensure absolute precision in sizing the market and forecasting growth rates.
Scope of the Report: Coverage Parameters and Analytical Limitations
This report covers global revenue flows across physical and digital art sectors from 2026 through 2033. Exclusions include informal grey-market private sales and unrecorded street art transactions, focusing exclusively on verifiable institutional, commercial gallery, and authenticated online marketplace revenues.
Recent Developments: Strategic Moves, Partnerships, and Product Launches
Recent industry momentum is defined by strategic tech acquisitions, expanded digital viewing room capabilities, and cross-border logistics partnerships. Major players like Art Basel and online entities are increasingly utilizing integrated augmented reality features to enhance remote collector engagement and transaction security.