What is the market overview of the Training, Education And Other Market?
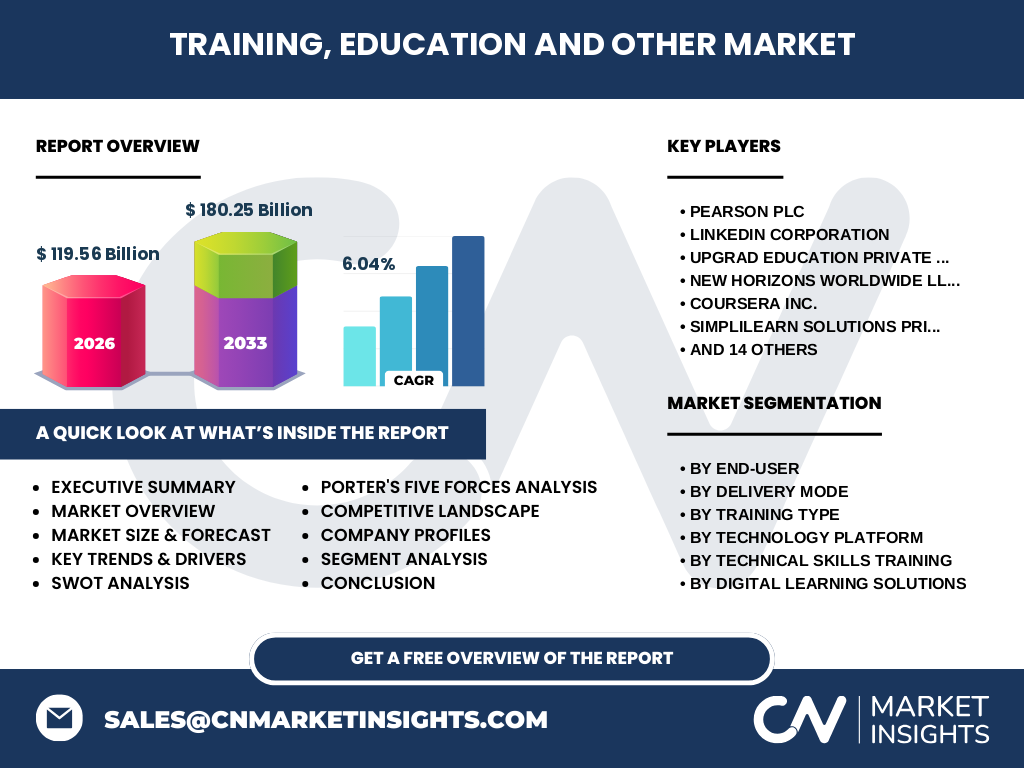
Our analysis indicates that the Training, Education And Other Market size stands at 119.56 Billion in 2026. This sector encompasses comprehensive enterprise upskilling, regulatory compliance certifications, and digital learning solutions. Industry significance stems from its critical role in bridging technical skills gaps across manufacturing, technology, and governance frameworks worldwide.
What are the key market drivers, restraints, challenges, and opportunities shaping the landscape?
The data suggests that rapid automation acts as a primary catalyst, driving demand for advanced Information Technology Technical Skills Training. Conversely, budget constraints in small enterprises restrain rapid procurement. Opportunities flourish in AI-driven adaptive learning frameworks, helping firms like Coursera Inc. and Simplilearn Solutions Private Limited capture high-margin corporate contracts.
Emerging trends and growth patterns in the Training, Education And Other Market
The shift toward microlearning and gamified platforms is redefining workforce development. Enterprises increasingly favor bite-sized, mobile-accessible modules over traditional multi-week seminars. This trend directly benefits agile innovators such as Edstellar Solutions Private Limited and Allen Interactions Inc., which specialize in high-engagement, interactive digital learning formats.
How did COVID-19 impact the sector and what is the recovery trajectory?
Pandemic-induced remote work accelerated digital platform adoption by half a decade. While physical instructor-led sessions plummeted, virtual classroom platforms experienced exponential surges. The post-pandemic recovery trajectory stabilized into a hybrid model, anchoring the robust growth moving toward our 2027-2033 forecasts.
Competitive benchmarking and strategic market dynamics
Market concentration features a mix of legacy publishing giants like Pearson Plc and specialized technology trainers such as Koenig Solutions Private Limited. Strategic positioning heavily relies on proprietary learning management systems and accredited professional certifications that guarantee measurable return on investment for enterprise clients.
Executive summary of key findings
Our comprehensive research confirms a projected market expansion from 2027 to 2033, reaching 180.25 Billion at a steady 6.04% CAGR. Corporate Information Technology Training and compliance modules dominate corporate budgets, driven by evolving data privacy regulations and cloud migration initiatives globally.
Market forecast and long-term valuation projections
Based on our econometric modeling, the market is set to expand from its 2026 baseline to 180.25 Billion by 2033. This growth trajectory is underpinned by a 6.04% CAGR, fueled by enterprise demands for continuous upskilling in artificial intelligence, cloud computing, and advanced manufacturing practices.
Segmentation analysis by end-user and delivery mode
Segmentation spans Enterprises, Small And Medium-Sized Enterprises, Government Organizations, Educational Institutions, and Corporate Training Centers. Delivery modes range from traditional Instructor-Led Training to E-Learning and Blended Learning. Enterprises capture the largest revenue share due to mandatory continuous professional development programs.
Regional market analysis and geographic performance distribution
Geographic performance indicates strong dominance in North America, supported by high tech-sector adoption. Meanwhile, the Asia-Pacific region demonstrates the fastest expansion rate, driven by massive government investments in digital literacy and rapidly growing corporate technology hubs in India and Southeast Asia.
In-depth regional review of high-growth territories
Regional deep-dives reveal that regulatory mandates in the European Union heavily boost spending on workplace safety and data privacy training. Conversely, North American markets prioritize artificial intelligence and machine learning enterprise integration programs, creating lucrative niches for specialized advisory firms.
Company profiles and strategic positioning of leading participants
Industry leaders maintain distinct competitive moats. Pearson Plc leverages vast academic content libraries, whereas LinkedIn Corporation monetizes professional networking data for targeted upskilling. Meanwhile, NIIT Learning Systems Limited and QA Limited focus on bespoke corporate technology transformation programs.
Porter's Five Forces analysis of competitive intensity
Supplier power remains moderate due to an abundance of independent subject matter experts. However, buyer power is high as enterprise procurement teams demand customized, outcome-based learning contracts. Threat of substitutes is mitigated by the rising necessity of accredited professional certifications.
SWOT analysis of the industry ecosystem
Strengths include high scalability of digital learning solutions. Weaknesses involve content obsolescence in fast-moving tech domains. Opportunities lie in emerging AI-based learning platforms. Threats stem from macroeconomic volatility impacting enterprise discretionary training budgets.
Value chain analysis from content creation to end-users
The value chain flows from foundational instructional design and content curation to platform hosting via Learning Management Systems, culminating in enterprise deployment. Companies owning proprietary Learning Experience Platforms capture significantly higher margins by controlling the direct end-user interface.
Investment insights and high-potential strategic areas
High-potential investment targets include niche platforms offering simulation-based learning and AI-driven skill gap analytics. Venture capital and private equity firms should focus on B2B SaaS providers catering to regulated sectors like healthcare certification and financial compliance training.
Conclusion and core takeaways for industry stakeholders
The Training, Education And Other Market presents a compelling growth narrative, scaling toward 180.25 Billion by 2033. Success requires pivoting away from static modules toward adaptive, tech-enabled digital learning solutions that deliver verifiable workforce competencies.
Research methodology and baseline estimation techniques
Our baseline estimates are rigorously triangulated by combining trade registry data, primary qualitative interviews with Chief Learning Officers, and secondary macroeconomic indicators. This multi-tiered validation ensures accurate market sizing across all delivery modes and technology platforms.
Scope of the report and coverage parameters
This report covers global market dynamics across twenty leading industry players, six delivery modes, and seven distinct training types. Limitations exclude informal, unrecorded peer-to-peer tutoring and unstructured consumer-facing educational content outside enterprise or institutional frameworks.
Recent developments, strategic partnerships, and product launches
Recent market activities highlight aggressive M&A strategies and platform integrations. Firms like Learning Technologies Group plc and Emeritus Institute of Management have launched joint university-corporate pathways, while Franklin Covey Co. expanded its digital leadership development suites to capture hybrid workforce demand.