What is the structural scope and industry significance of the Gate Openers Market?
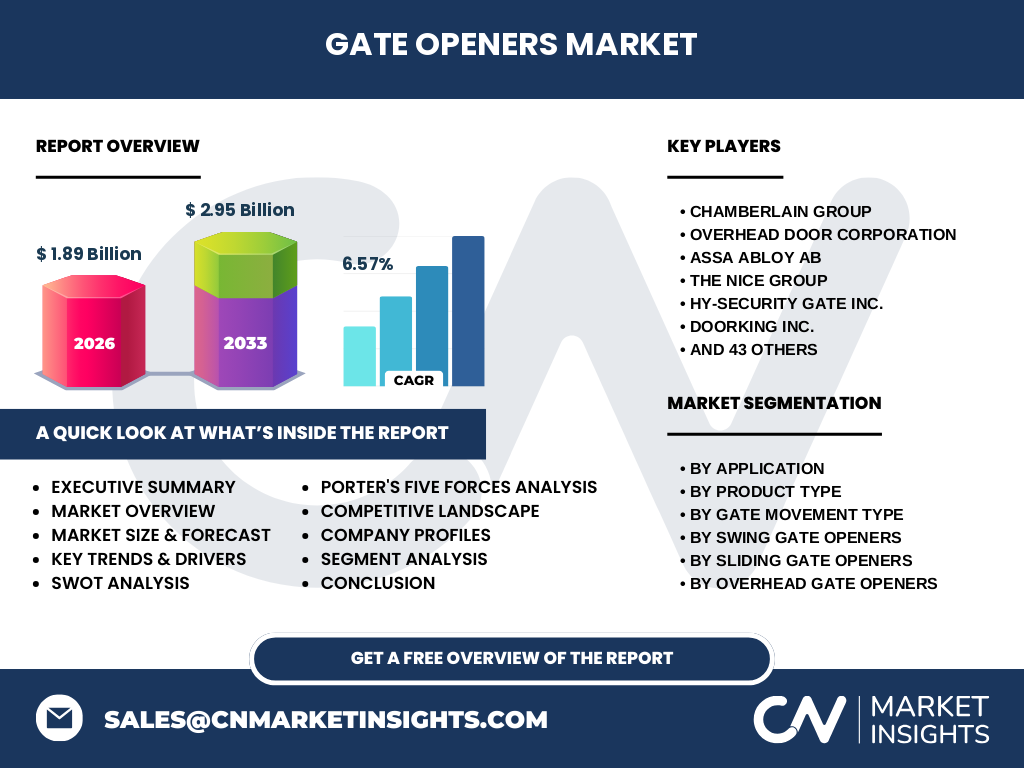
Our analysis indicates that the Gate Openers Market valuation reached 1.89 Billion in 2026, driven by rising perimeter security demands across residential, commercial, and industrial sectors. This infrastructure sector encompasses advanced automated gate systems, electro-mechanical actuators, and smart access controllers. Industry significance stems from its critical role in managing vehicular and pedestrian access while integrating with broader building management frameworks regulated by international safety standards.
Structural Growth Drivers and Restraints shaping the Gate Openers Market
Based on our research, rapid urbanization and commercial real estate expansion act as primary growth catalysts for the industry. Conversely, strict compliance mandates enforced by bodies like UL 325 regarding entrapment protection present operational hurdles for manufacturers. Supply chain bottlenecks involving specialty raw materials such as rare-earth magnets for brushless DC motors further constrain rapid output scaling for key market participants.
Emerging trends and growth patterns in the Gate Openers Market
The data suggests a decisive pivot toward Internet of Things (IoT) connectivity and solar-powered integration, particularly within remote agricultural and rural installations. Innovators like TOPENS and Mighty Mule are leading the charge in solar sliding gate openers, capitalizing on consumer demand for energy-efficient, off-grid automated security solutions that reduce long-term electrical operational expenditures.
COVID-19 impact analysis and recovery trajectory
The pandemic initially triggered severe supply chain disruptions and component shortages across major manufacturing hubs in Fujian province, temporarily stalling production lines for firms like Zhejiang Xianfeng Machinery. However, the subsequent post-pandemic recovery trajectory accelerated robustly, fueled by a surge in residential home-renovation spending and heightened enterprise investments in contactless, automated access control infrastructure.
Competitive Benchmarking and Strategic Dynamics
The competitive landscape is characterized by moderate market concentration, featuring global conglomerates alongside agile regional specialists. Industry giants like Assa Abloy AB, Chamberlain Group, and The Nice Group leverage aggressive mergers, acquisitions, and proprietary software ecosystems to maintain dominance. Meanwhile, specialized manufacturers such as Hy-Security Gate Inc. and DoorKing focus on heavy-duty industrial applications requiring high-cycle durability and rugged mechanical resilience.
Executive Summary of the Gate Openers Market
This comprehensive overview projects the Gate Openers Market to expand from 1.89 Billion in 2026 to reach 2.95 Billion by 2033, registering a solid CAGR of 6.57%. Stakeholders must navigate evolving safety regulations, technological integrations, and regional demand disparities. Strategic positioning within solar-powered and IoT-enabled segments remains essential for capturing high-margin growth opportunities.
Market Forecast and Trajectory through 2033
Our analysis indicates sustained expansion, forecasting the market to scale from 1.89 Billion in 2026 to 2.95 Billion by 2033 at a steady CAGR of 6.57%. This steady upward trajectory is underpinned by rising infrastructure investments across emerging economies and replacement cycles for aging electro-mechanical gate hardware in developed commercial districts.
Segmentation Analysis by Application, Product Type, and Movement
The market divides by application into Residential, Commercial, Industrial, and Other Applications. Product types span Linear Ram, Underground, Articulated Ram, Sliding, and Other Product Types. Gate movement types categorize into Sliding Gate Openers, Swing Gate Openers, and Overhead Gate Openers. Sub-segments include single and dual swing variations, electric and solar sliding systems, as well as rolling and sectional overhead configurations.
Regional market analysis and geographic distribution
Geographic performance varies significantly, with North America and Europe demonstrating high adoption rates for smart, connected residential units. Conversely, Asia-Pacific represents the fastest-growing regional market, propelled by massive industrialization and smart-city initiatives in countries like China and India, where localized manufacturing hubs cater to surging domestic real estate developments.
In-depth regional review of key international markets
Regional evaluations reveal distinct operational dynamics; for instance, Latin American markets are heavily influenced by established regional players like PPA S.A. and CAME Group Colombia. In the Middle East, high-security infrastructure projects drive demand for robust solutions distributed by firms such as Al-Bahar Gate Automation and Toshiba Johnson Elevators Qatar, prioritizing extreme weather resistance and sand-intrusion protection.
Company profiles and strategic market positioning
Leading industry participants deploy distinct growth strategies. Hörmann and FAAC SPA focus on premium architectural integration and heavy-duty industrial engineering. LiftMaster and Chamberlain Group dominate consumer mindshare through smart-home ecosystem compatibility. Concurrently, regional innovators like Centurion Systems and ET Systems maintain formidable market share in Africa by engineering rugged systems tailored to erratic local electrical grids.
Porter's Five Forces analysis of the industry
The threat of new entrants remains moderate due to high initial tooling costs and stringent regulatory safety certifications. Bargaining power of suppliers is constrained by numerous alternative sources for structural metals and copper windings, whereas buyer power is high, driven by extensive distributor networks and price transparency in the commercial sector.
SWOT analysis of the Gate Openers Market
Key strengths include robust mechanical durability and expanding IoT compatibility. Weaknesses involve complex installation requirements and ongoing maintenance overheads. Opportunities lie in rural solar electrification and smart-city integration. Threats center on macroeconomic inflationary pressures impacting raw material acquisition costs for aluminum and steel.
Value chain analysis from raw materials to end-users
The value chain initiates with upstream raw material providers supplying aluminum, steel, and electronic semiconductors. Midstream manufacturers assemble actuators, control boards, and wireless receivers. Downstream distribution occurs through specialized dealers, system integrators, and e-commerce platforms like Door Superstore, ultimately serving residential homeowners and industrial facility managers.
Investment insights and high-potential areas
High-potential investment zones center on proprietary cloud-connected access platforms and solar-reliant mechanical drives. Capital allocators should target firms possessing robust intellectual property in obstacle-detection software and remote diagnostics, as facility managers increasingly prioritize predictive maintenance capabilities to minimize costly operational downtime.
Conclusion and key takeaways for industry stakeholders
The Gate Openers Market presents lucrative prospects for forward-thinking enterprises, backed by a projected valuation of 2.95 Billion by 2033. Success requires balancing stringent safety compliance with rapid technological innovation in solar and IoT connectivity, ensuring competitive advantage across both mature and emerging regional landscapes.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by synthesizing customs trade registry data, primary qualitative interviews with C-suite executives across major firms like Assa Abloy and Nice Group, and secondary macroeconomic indicators. Quantitative models cross-reference historical shipment volumes with projected real estate construction indexes to ensure absolute market sizing accuracy.
Scope of the report and coverage parameters
This report covers global market dynamics for the Gate Openers Market from 2027 through 2033, utilizing 2026 as the baseline validation year. The scope encompasses detailed unit shipments and revenue evaluations across all specified product categories, movement types, and end-user verticals, excluding custom proprietary military-grade perimeter fortifications.
Recent developments, partnerships, and strategic moves
Recent industry momentum highlights strategic acquisitions and product rollouts focusing on smartphone integration. Major players have forged OEM partnerships with leading smart-home platform providers to streamline remote diagnostics. Furthermore, localized expansions by firms like BFT Mexico and BENINCA Group Israel underscore a broader industry push to secure localized supply chain resilience and responsive regional distribution.