What is the market overview and industry significance of the Computer Vision For Retail Market?
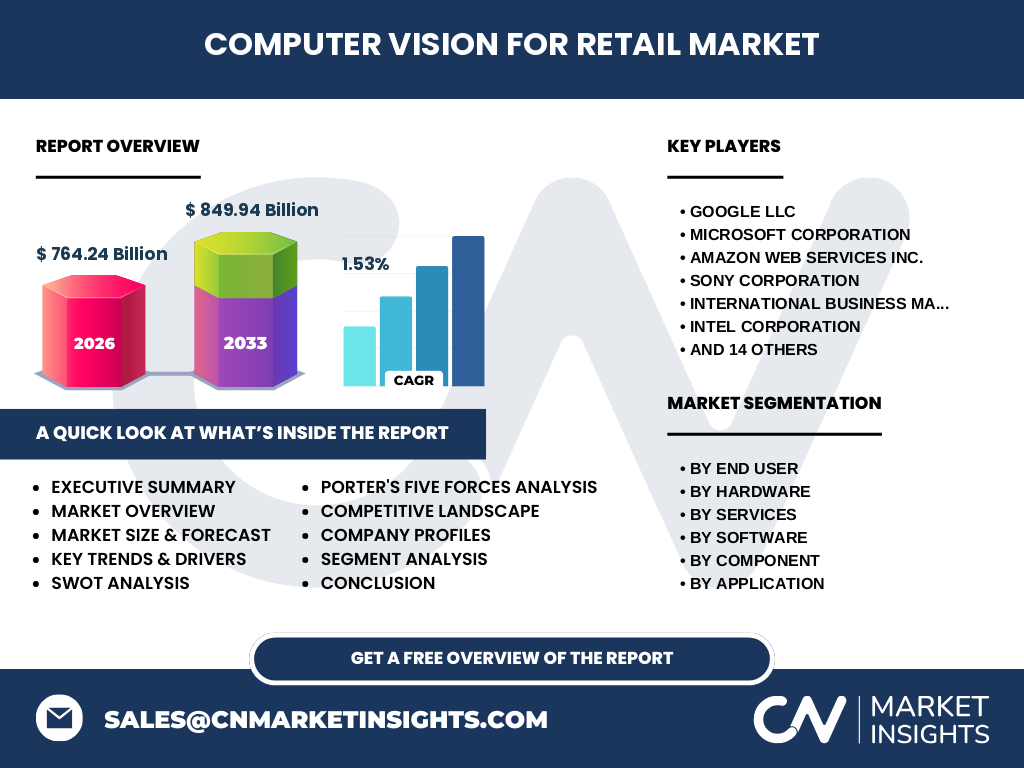
Our analysis indicates that the Computer Vision For Retail Market is valued at $764.24 Billion in 2026. This foundational ecosystem encompasses advanced hardware like specialized cameras and sensors combined with sophisticated software, driving unprecedented automation and consumer analytics across global brick-and-mortar storefronts and digital fulfillment centers.
What are the key market drivers, restraints, challenges, and opportunities shaping the Computer Vision For Retail Market?
Structural growth stems from escalating demand for cashierless checkout and loss prevention. However, high initial capital expenditures for edge processors and strict regional data privacy mandates like GDPR act as major market restraints, challenging large enterprises and SMEs alike.
Emerging trends and growth patterns in the Computer Vision For Retail Market
The shift toward cloud-based analytics tools and edge-computed artificial intelligence algorithms is redefining retail operations. Industry leaders are increasingly deploying generative video analytics software to optimize inventory replenishment cycles and personalize shopper interactions in real time.
How did the COVID-19 pandemic affect the Computer Vision For Retail Market and shape its recovery trajectory?
Pandemic-era supply chain bottlenecks and social distancing mandates accelerated touchless retail adoption. Our research shows that post-pandemic recovery relies heavily on automated checkout optimization, compelling retailers to invest permanently in contactless infrastructure.
Competitive benchmarking and strategic dynamics in the Computer Vision For Retail Market
The competitive landscape features dominant tech giants alongside agile specialists. Companies like Google LLC, Microsoft Corporation, and Amazon Web Services Inc. leverage massive cloud ecosystems, while innovators like Trigo Vision Ltd. and Standard AI Inc. pioneer autonomous checkout solutions.
Executive summary of key findings regarding the Computer Vision For Retail Market
The market demonstrates resilience, projected to reach $849.94 Billion by 2033 at a steady CAGR of 1.53%. Investment priorities are shifting toward integrated managed services and high-precision image recognition software to combat shrink and elevate customer experiences.
Market forecast and projected growth trajectory from 2027 to 2033
Driven by steady adoption across supermarkets and hypermarkets, the market will scale from its 2026 baseline to $849.94 Billion by 2033. This trajectory reflects a conservative yet stable 1.53% CAGR as hardware costs normalize.
Segmentation analysis across hardware, software, services, and end users
The market divides by component into hardware, software, and services. Software categories include video analytics and artificial intelligence algorithms, while end users span large enterprises and resource-constrained small and medium enterprises demanding scalable cloud deployments.
Geographic distribution and regional market analysis for computer vision solutions
Regional performance varies based on local retail density and labor costs. North America dominates adoption due to robust IT infrastructure, whereas Asia-Pacific exhibits rapid growth spurred by expanding convenience store chains and hypermarket digitization.
In-depth regional review of high-growth retail automation zones
Metropolitan retail hubs in North America and Western Europe lead in hardware integration, particularly sensors and display units. Meanwhile, localized market constraints in developing economies favor lightweight cloud-based analytics tools over costly on-premises server installations.
Company profiles and strategic positioning of leading market participants
Industry titans such as NVIDIA Corporation and Intel Corporation provide foundational processors, whereas specialized players like Trax Technology Solutions Pte. Ltd. and Vispera Information Technologies Inc. dominate retail shelf monitoring and stock-out prevention.
Porter's Five Forces analysis of the Computer Vision For Retail Market
Bargaining power of hardware suppliers remains moderate due to specialized processor manufacturing requirements. Meanwhile, competitive rivalry is intense, forcing software developers to continuously refine their artificial intelligence algorithms to secure enterprise contracts.
SWOT analysis evaluating industry strengths, weaknesses, opportunities, and threats
Key strengths include unmatched loss prevention capabilities and precise customer analytics. However, high implementation costs represent a notable weakness, while strict cross-border regulatory compliance frameworks pose persistent external threats to data management platforms.
Value chain analysis detailing industry structure from raw materials to end-users
The value chain originates with semiconductor and sensor raw material suppliers, progressing through hardware assemblers and software developers. Integrators then deliver customized installation and maintenance services directly to supermarkets, online retailers, and specialty stores.
Strategic investment insights and high-potential focus areas
High-potential opportunities lie in training and implementation services as retailers struggle with internal technical skill gaps. Investors should prioritize firms offering scalable, subscription-based cloud analytics tools targeting small and medium enterprises.
Conclusion and critical takeaways for retail technology stakeholders
With the market slated to reach $849.94 Billion by 2033, computer vision is no longer optional for competitive retail. Stakeholders must focus on seamless installation and robust data management to capture long-term enterprise value.
Research methodology for baseline estimates and data triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with retail CIOs, and secondary macroeconomic indicators to ensure high-fidelity market sizing for the Computer Vision For Retail Market.
Scope of the report and analytical coverage parameters
This report covers global deployment modes including on-premises and cloud infrastructures across eight distinct retail types. Limitations exclude unverified pilot projects and informal mom-and-pop storefronts lacking digital telemetry.
Recent developments, strategic partnerships, and product launches
Recent industry momentum highlights strategic partnerships between cloud providers and retail conglomerates. Companies like Zebra Technologies Corporation and Scandit AG. continue to launch integrated enterprise mobile vision tools, accelerating checkout optimization worldwide.